The Top 5 Retirement Planning Questions Clients Ask (and How to Answer Them)
June 18, 2026
Key Takeaways
- Pre-retiree expectations are shifting fast and advisors are fielding more personalized, complex questions than ever.
- Setting retirement to age 65 gives a baseline probability of success while live adjustments to contributions, spending, and Social Security timing show clients what's actually possible.
- Modeling how spending could change over retirement can produce a more accurate plan than a flat inflation-adjusted assumption.
- Optimizing the withdrawal sequence and using Roth conversions during low-tax years can increase assets passed to heirs and cut lifetime taxes.
- Integrations, Data Import, and AI-powered Smart Import pull client details from statements, reports, and transcripts automatically, so advisors using RightCapital can build a plan without putting the burden on the client.
According to the Advisor Authority study by Nationwide Retirement Institute, “59% of pre-retirees said their expectations for retirement have changed significantly in the last five years,” and 64% say the traditional norm of retiring at age 65 "doesn't apply to people like them."
With more pre-retirees rethinking when and how they'll retire and fewer relying on traditional rules of thumb, the questions landing on advisors' desks are more personalized and complex than ever. Modern financial planning software answers the specific questions of pre-retirees interactively, turning complex projections into clear conversations clients actually understand.
What are the most common retirement planning questions?
Some of the most common pre-retirement questions advisors hear are about retirement timing, lifestyle goals, tax efficiency, and how much effort a financial plan requires from the client. The sections below walk through each question and how you can address client concerns within your financial planning software, even making changes live during a client meeting.
When a client asks if they can retire by age 65
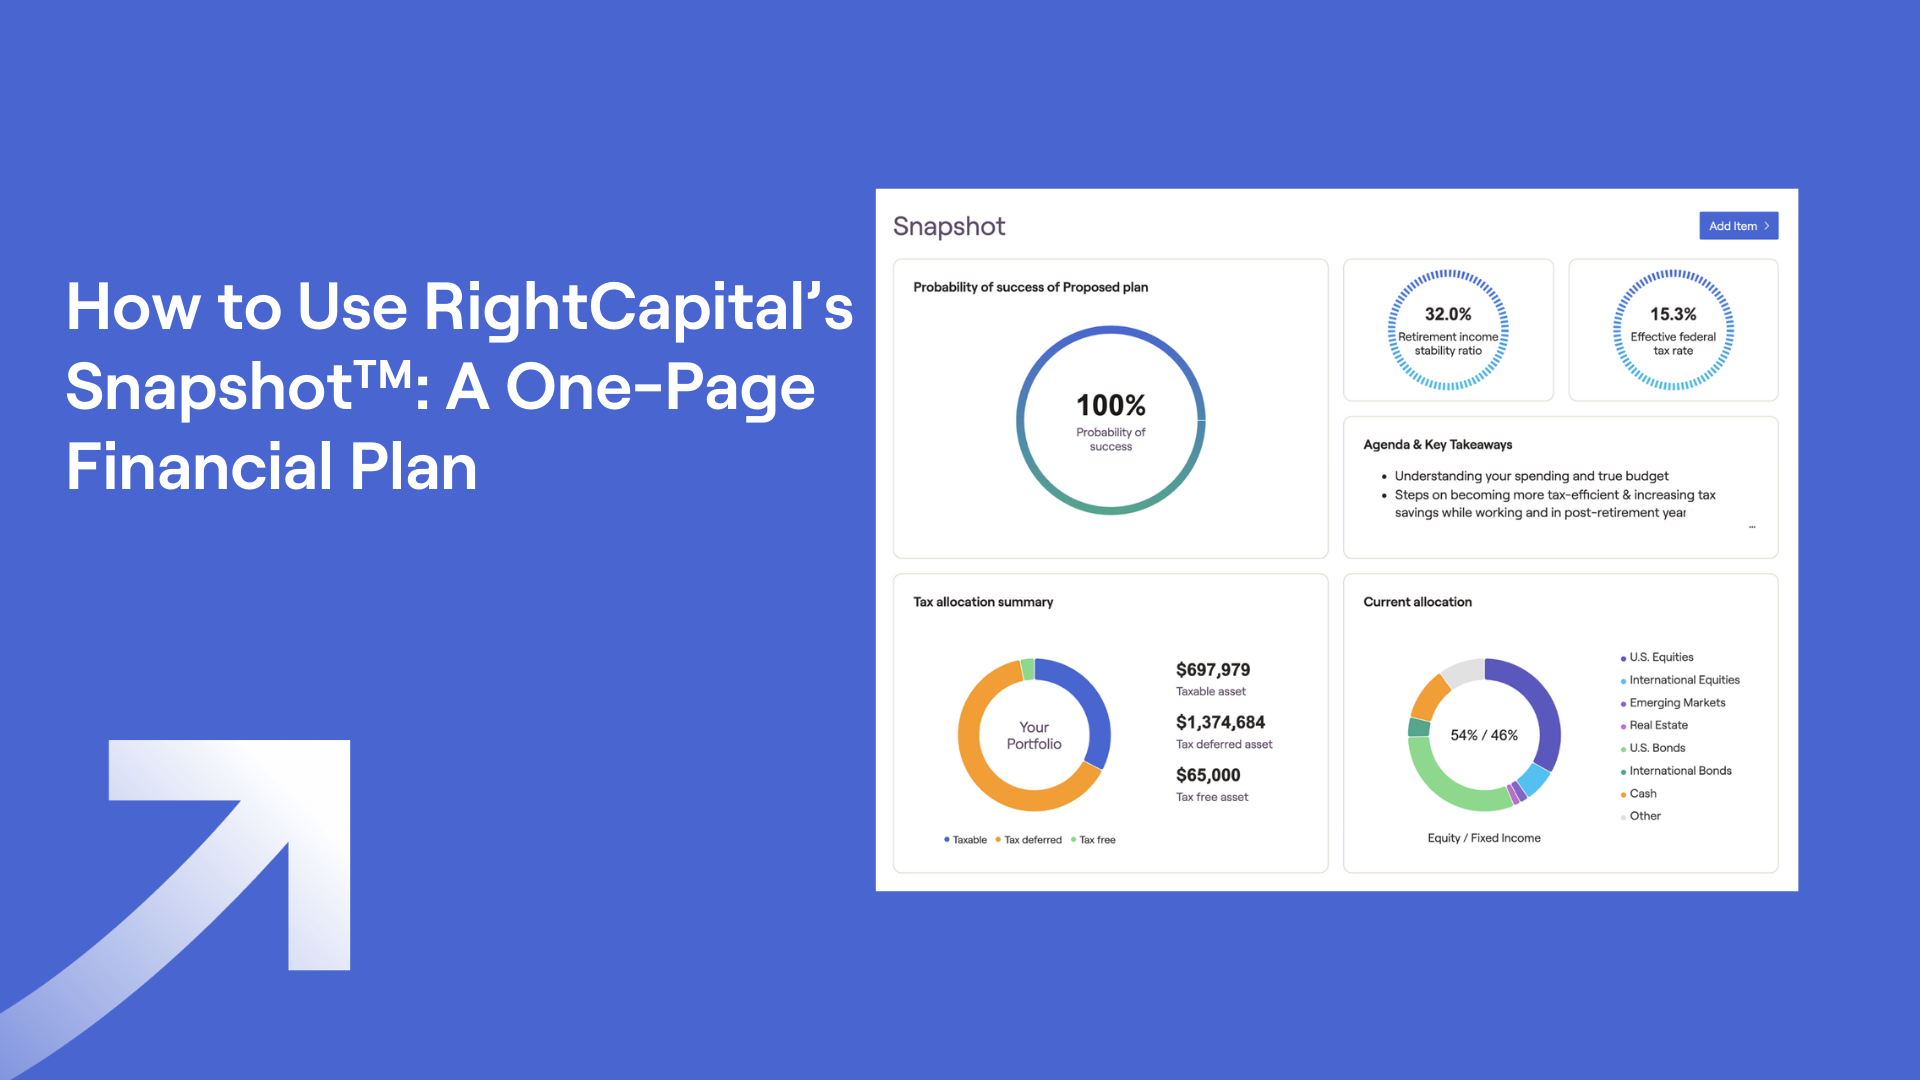
Determine a baseline probability of success
Setting a retirement age to a standard 65 provides a baseline probability of success for your client's plan. As the probability of success runs Monte Carlo simulations (1,000 trials of market volatility) and reports the percentage of trials in which the client reaches the end of the plan without running out of money, it serves as a strong gauge of future financial well-being.
Demonstrate alternatives to the current plan with small changes
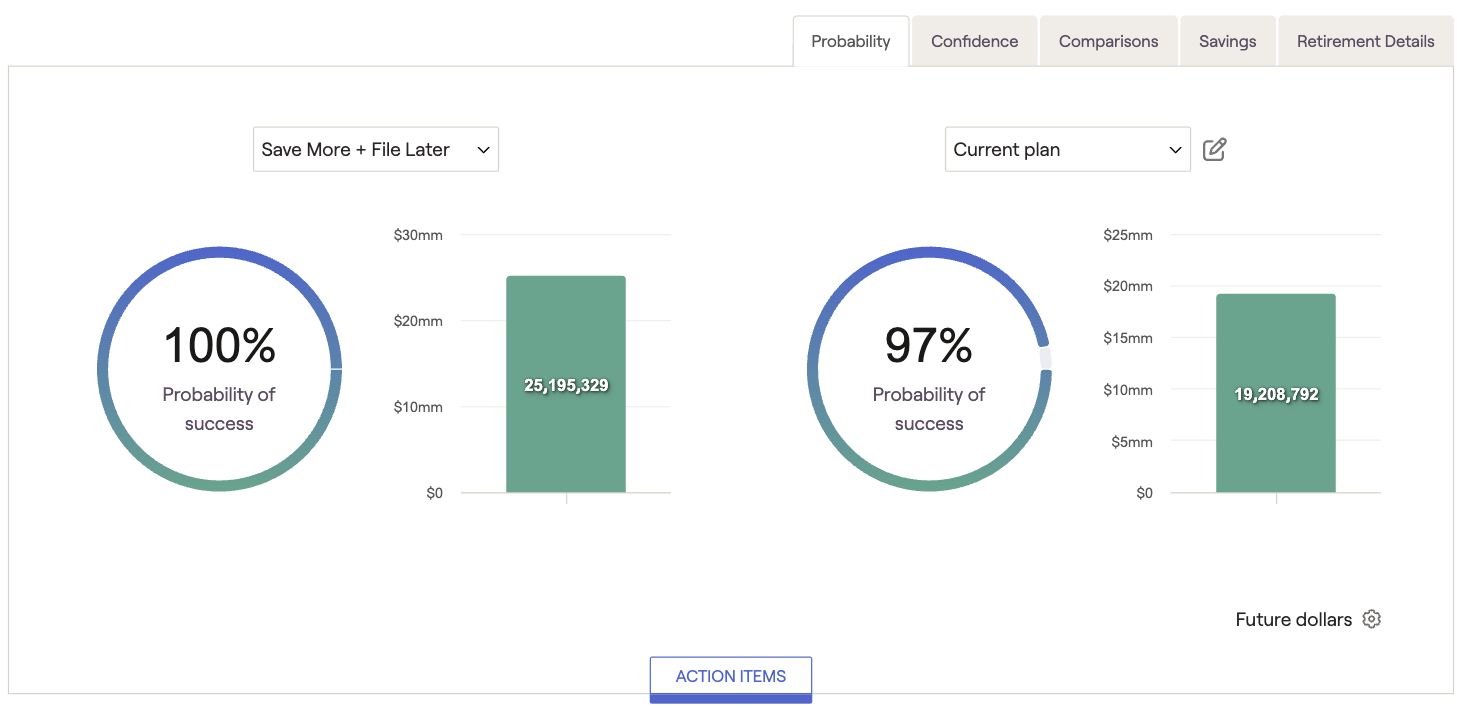
- 401(k) contributions
- Pre-retirement and/or retirement spending
- Social Security timing
Refresh the screen and the impact of your proposed adjustments on the probability of success appears immediately. When the baseline number is lower than a client hoped, this is where you show what's actually possible, whether that's a few targeted changes that close the gap, or an honest conversation about adjusting the timeline. If the baseline number is higher than expected, you can give your client the confidence to spend more or add a few dreams to the agenda.
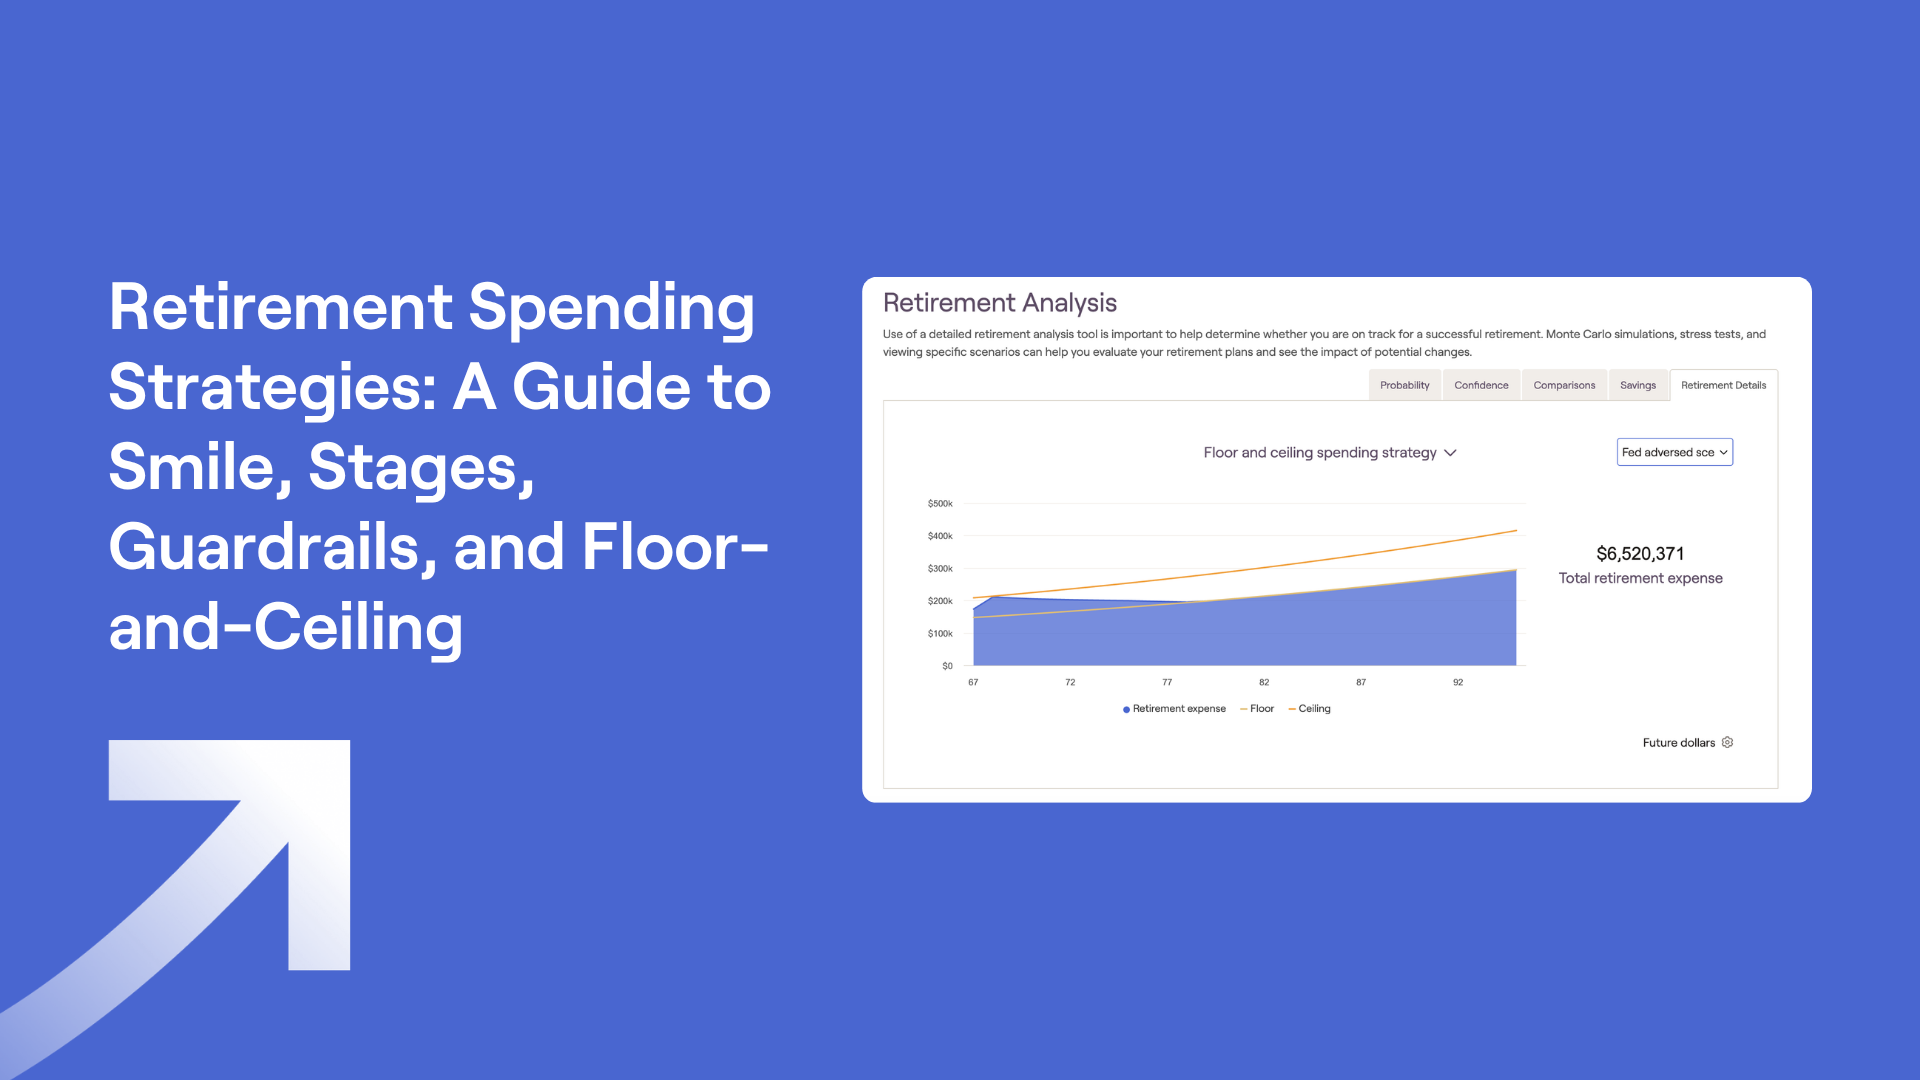
Use a more realistic retirement spending strategy
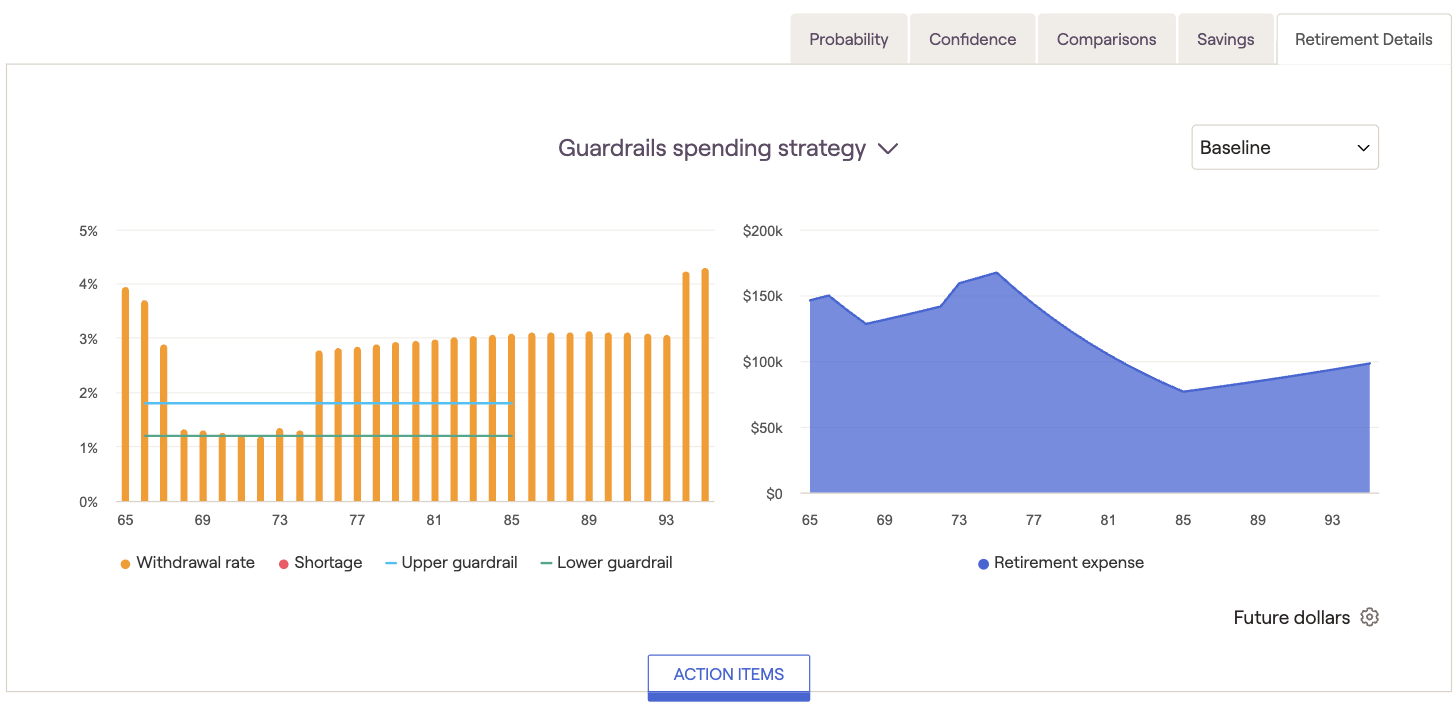
- Retirement spending stages (often called "go-go, slow-go, no-go"): Greater expenses in the first few years of retirement when they are most active and slowed down spending in later years
- Retirement spending smile: Household expenditures declining slowly but steadily throughout retirement while healthcare costs increase over time; resulting in an expense chart resembling a “smile” pattern as expenses dip mid-retirement before rising again
- Guardrails: Retirement spending set to adapt automatically if it expands past designated withdrawal rate guardrails
- Floor and ceiling: Spending to fluctuate with market performance, increasing in strong market years (no higher than a designated ceiling) and decreasing in down markets (no lower than a specified floor)
When a client asks what they can afford to spend on their goals
Add goals to current and proposed plans
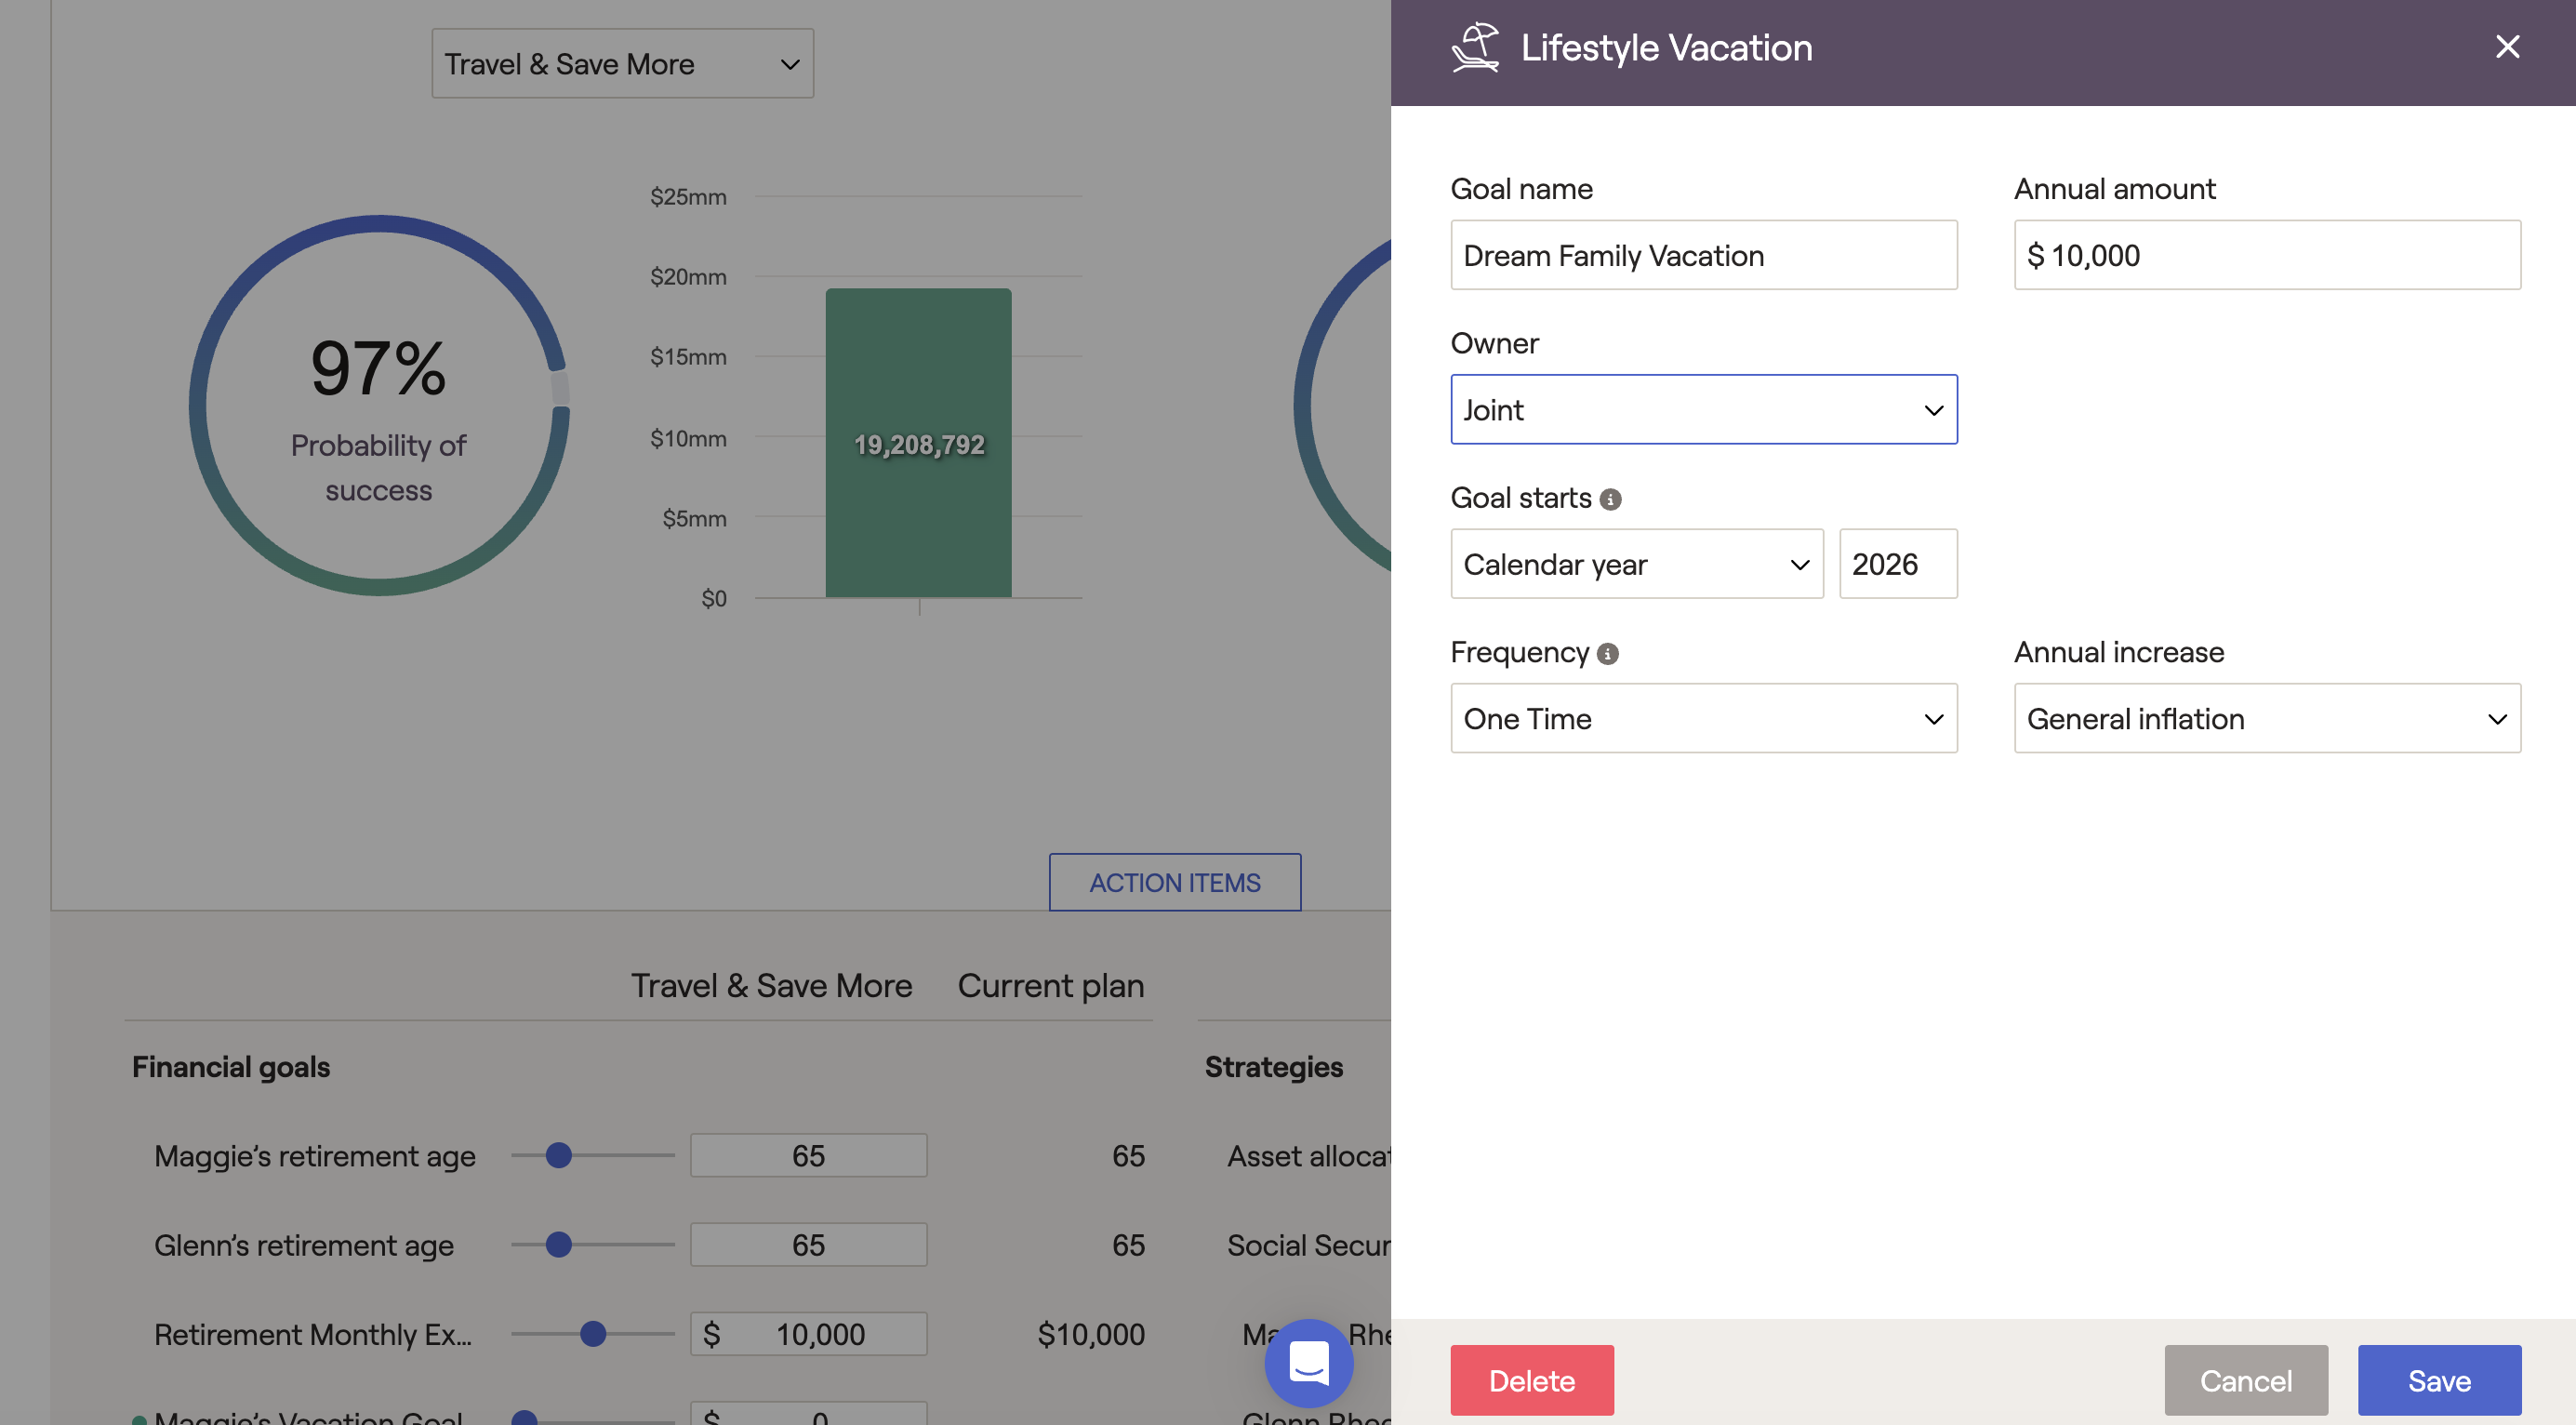
Of course dreams vary and these goals could be anything your client desires, from a vacation home on the Jersey Shore to following Springsteen on his next tour. Play around with multiple scenarios to help your clients bring their vision boards to life.
When a client asks how to be tax-efficient in retirement
 Choose a software that stays up-to-date with tax law
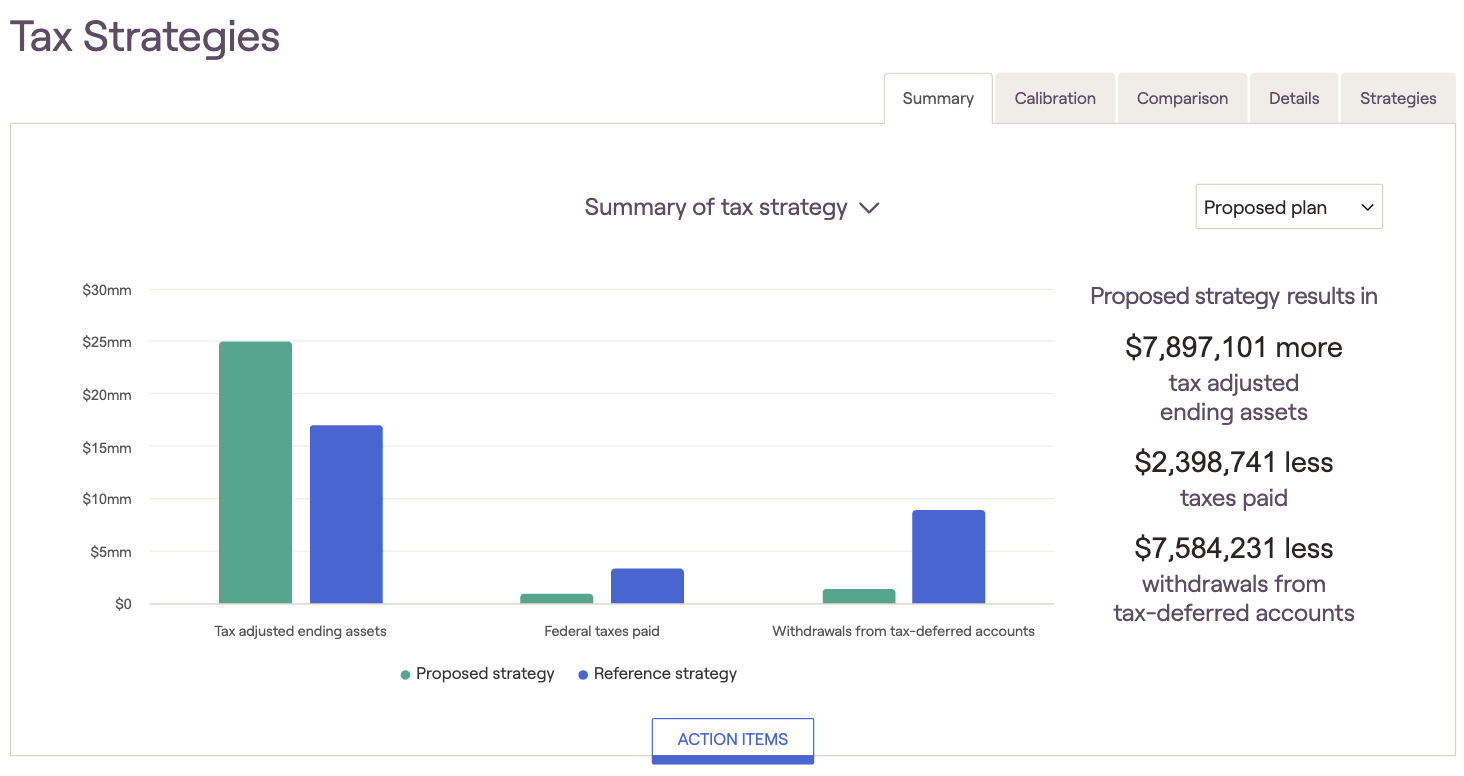
It’s most convenient when your financial planning software builds current tax law into the calculations so that your distribution method proposals are realistic and optimal. When state, federal, and FICA taxes are calculated automatically from the client's information, it becomes easy to discuss the best way to draw down assets.
Show the difference visually
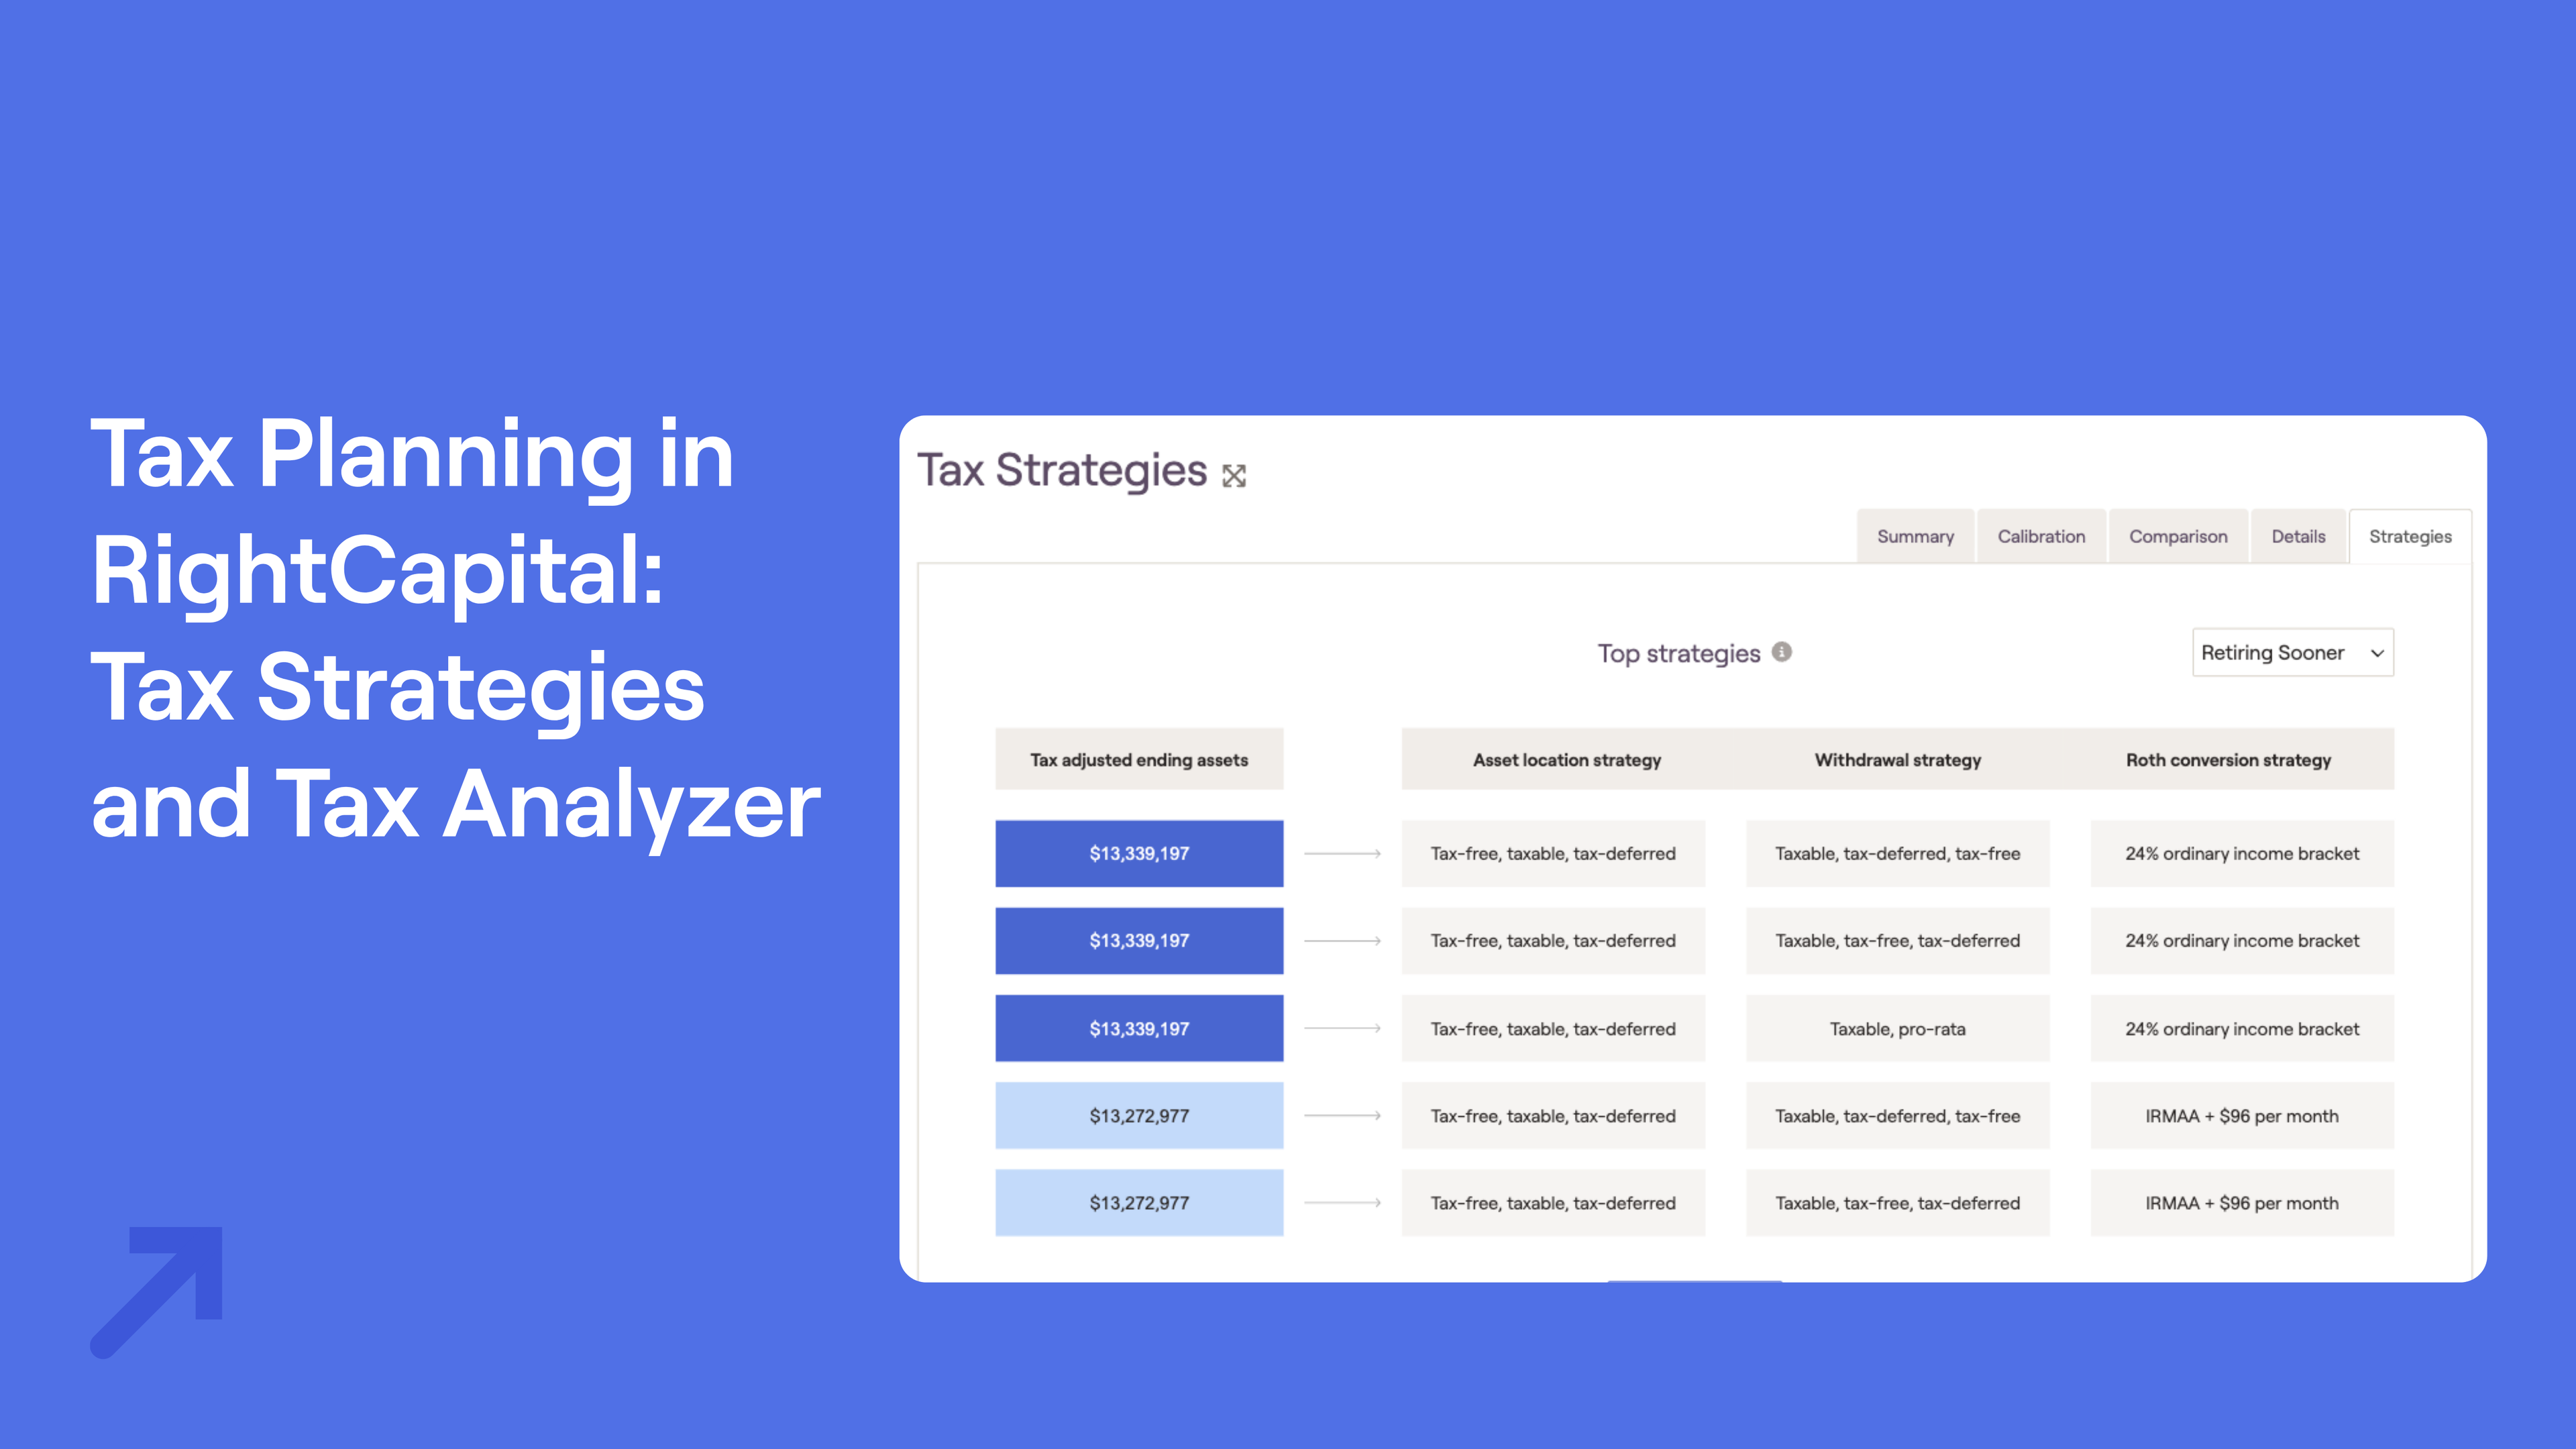
Using visuals within your financial planning software, you will be able to demonstrate the value of tax strategies such as Roth conversions.
For example, a chart that shows the ordinary income tax bracket over time may have the client in a lower tax bracket between the year they retire and the years that they start collecting Social Security and RMDs. These low-tax years are ideal for Roth conversions. Using a slider to fill up the tax brackets, the system calculates what to convert each year to take advantage of the lower tax rate without pushing the client into a higher bracket at the same time.
This typically results in a significant increase in projected assets passed to heirs and tax savings over the life of the plan. Best of all, the optimization applies to any scenario to maximize what the client keeps over their lifetime, including the proposed plans you created to meet their dream goals.
When a client asks how to be more tax-smart now
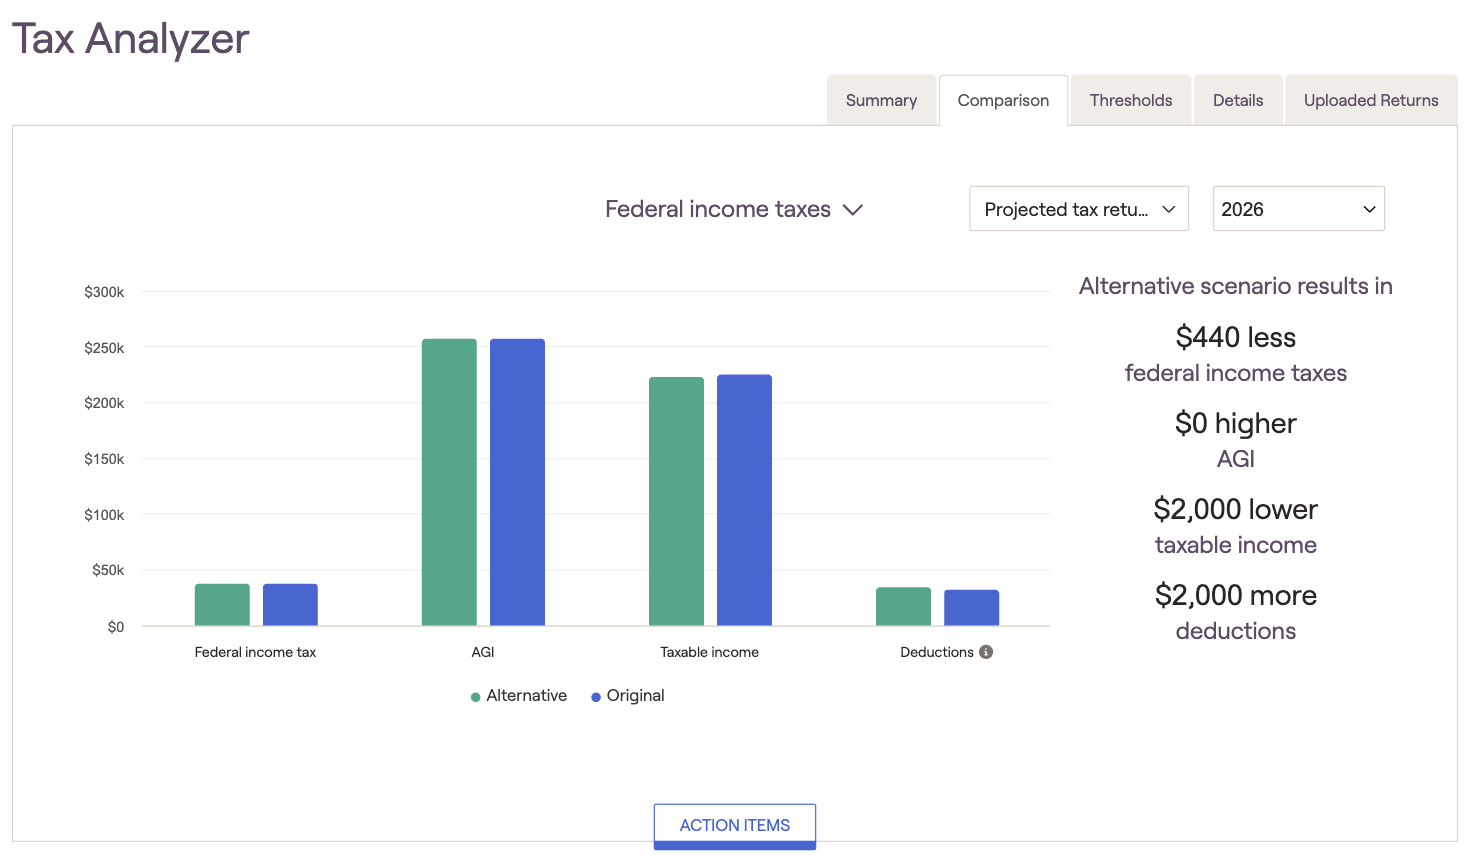
From there, you can model a change (say, $45,000 in Roth conversions and $2,000 in charitable contributions) while everything else stays the same, then weigh the expected bump in taxes and any impact on key thresholds. A side-by-side view shows where you begin, the change you're making, and the impact down the line. You can also model adjustments to future projected tax years to identify changes today to help the client later.
When a client asks how much work is needed on their end
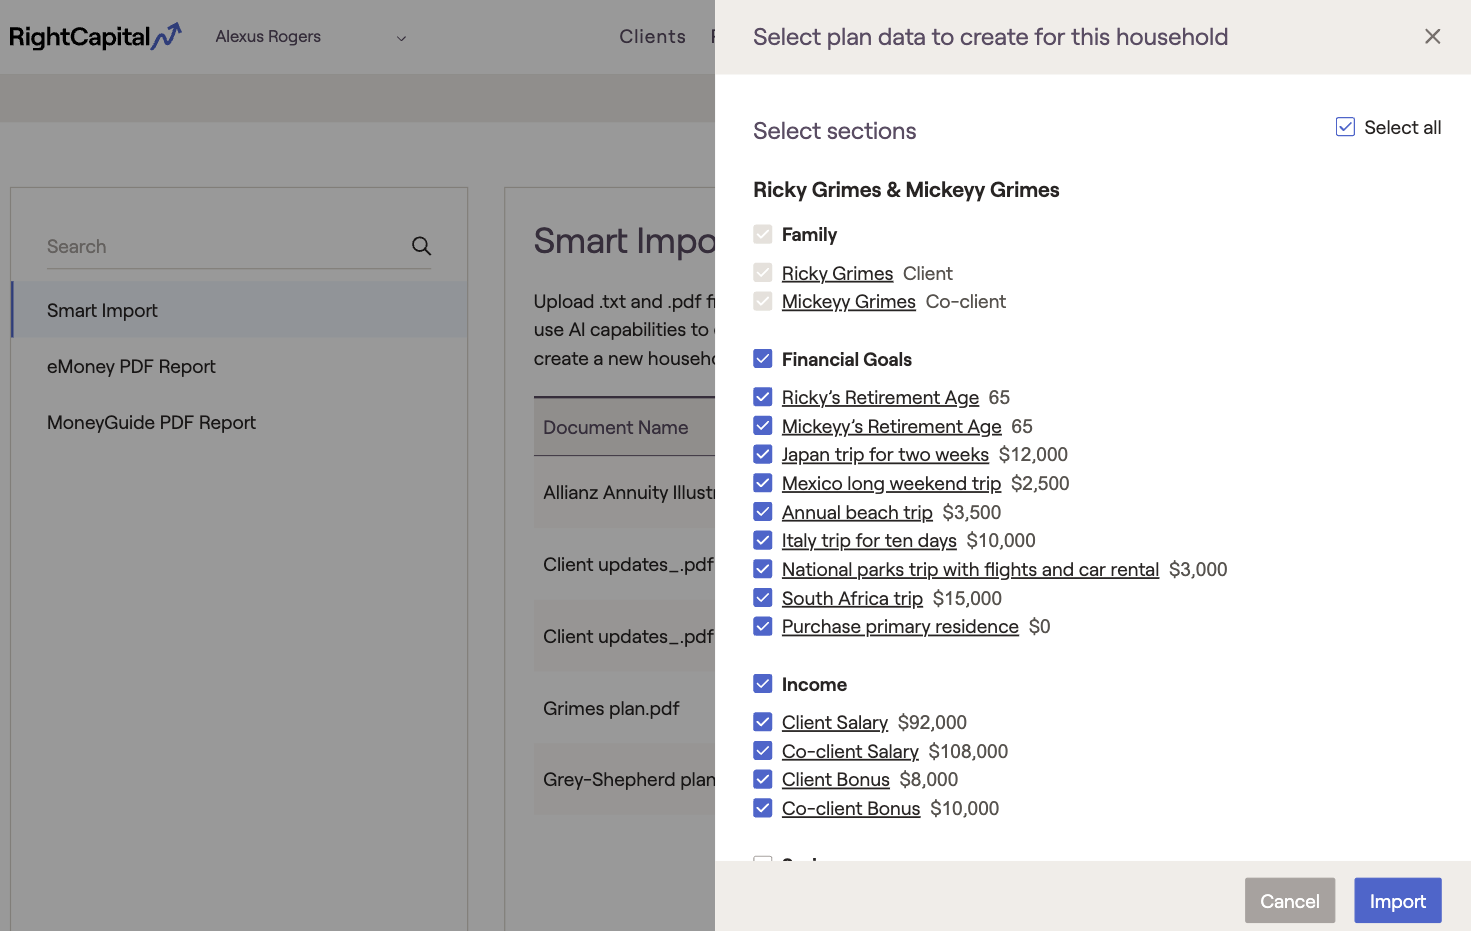
- Integrations: Syncing with 40+ platforms including major custodians, reporting tools, and CRMs, with data updating daily
- Data Import: Pulling family details, assets, and properties directly from eMoney or MoneyGuide reports when advisors are transitioning platforms to be reviewed for inclusion in a new or existing client plan
- Smart Import: AI scanning of PDF or text files with client information, including meeting transcripts, third-party reports, and account statements; extraction of key financial data for your review to include in a client plan
The bottom line
Today’s clients are looking for financial advice, not just portfolio management. Clients need to understand what's possible given their goals, and they yearn for the confidence that comes from seeing the numbers. The right planning approach turns complex conversations into something clients can actually understand. And once they understand, they have buy-in, conviction, and follow-through, because real value lies wherever finances and life intersect.
Answer your clients' toughest questions with confidence. Schedule a demo of RightCapital today.
Frequently asked questions
It's a spending approach that reflects common retiree spending patterns: more in the first years of retirement, less through the mid-to-late 70s, and less still in the 80s. Modeling this can be more realistic than assuming flat, inflation-adjusted spending for 25 to 30 years.
Converting during low-income years (often between retiring and starting Social Security and RMDs) allows clients to fill up lower tax brackets without bumping them into a higher one. This can increase the assets passed to heirs and reduce taxes paid over the life of the plan.
Very little. Through integrations, data import from other planning tools, and AI-powered Smart Import that scans statements, reports, and meeting transcripts, advisors can populate most of a plan automatically while also minimizing the legwork on the client side.