How Financial Advisors Can Add Value for High-Net-Worth Clients
October 22, 2026
Key Takeaways
- Households with more than $5 million held 57% of U.S. investable assets in 2025, up from 30% in 2010, according to Cerulli Associates.
- Only 36% of households with more than $5 million in financial assets have a comprehensive plan built by an advisor (Cerulli).
- HNW clients increasingly expect advisors to go beyond investment management with estate, tax, charitable, and business planning.
- The right planning technology helps advisors deliver that depth of planning efficiently, without juggling separate tools.
- RightCapital brings HNW planning into one platform with estate flow charts, 10+ trust types, tax strategy modeling, charitable giving, equity compensation, business planning, Iris™ AI financial planning agent, and more.
Financial advisors add value for high-net-worth (HNW) clients by going beyond investment management to deliver estate, tax, charitable, and business planning. According to research from Cerulli Associates, only 36% of households with more than $5 million in financial assets have a comprehensive advisor-built plan.
What is a high-net-worth client?
A high-net-worth client typically has at least $1 million in investable assets, not counting a primary residence. Capgemini's World Wealth Report uses this definition and splits the group into three tiers: $1–5 million, $5–30 million, and ultra-high-net-worth (UHNW) at $30 million or more.
Firms set their own thresholds, so the label varies. What HNW households tend to share is complexity, with concentrated stock, trusts, multiple properties, business interests, and estate tax exposure. You may also know this as “mo’ money, mo’ problems.”
Why are high-net-worth clients a growing opportunity for advisors?
High-net-worth clients control a growing share of U.S. wealth, and many still don't have a comprehensive financial plan. According to Cerulli Associates, households with more than $5 million held 30% of U.S. investable assets in 2010. By 2025, that share had grown to 57%. Over the same period, households with more than $20 million went from holding 10% of investable assets to more than a quarter (27%).
As wealth concentrates, the households holding it tend to have more complex needs. Advisors who can answer estate, tax, and charitable questions in one place are in a strong position to win and keep these clients.
What services do high-net-worth clients expect from financial advisors?
High-net-worth clients increasingly expect estate, charitable/philanthropic, trust, and tax planning alongside investment management. According to Cerulli Associates, the share of HNW practices offering estate planning rose from 56% to 73% between 2017 and 2024.
These services can also deepen the relationship. A plan that maps out a client's estate, taxes, and giving often brings up assets held elsewhere and questions the client hasn't asked yet, which gives the advisor more ways to help.
What stops advisors from offering more HNW planning?
Capacity is often the biggest barrier. HNW planning involves more scenarios, more documents, and more coordination with outside professionals. According to Cerulli Associates, 58% of advisors say their planning technology lacks critical features or integrations.
Juggling separate tools for estate, tax, and charitable scenarios means more time on data entry and less time with clients.
RightCapital brings these planning areas into one platform. The table below shows the HNW client questions it helps advisors answer, followed by more detail on each.
Client question | What RightCapital helps you show |
|---|---|
"Where will my estate go, and how much will taxes take?" | Estate flow chart with federal and state estate tax |
"Would a trust help my family?" | 10+ trust types, compared side by side with the current plan |
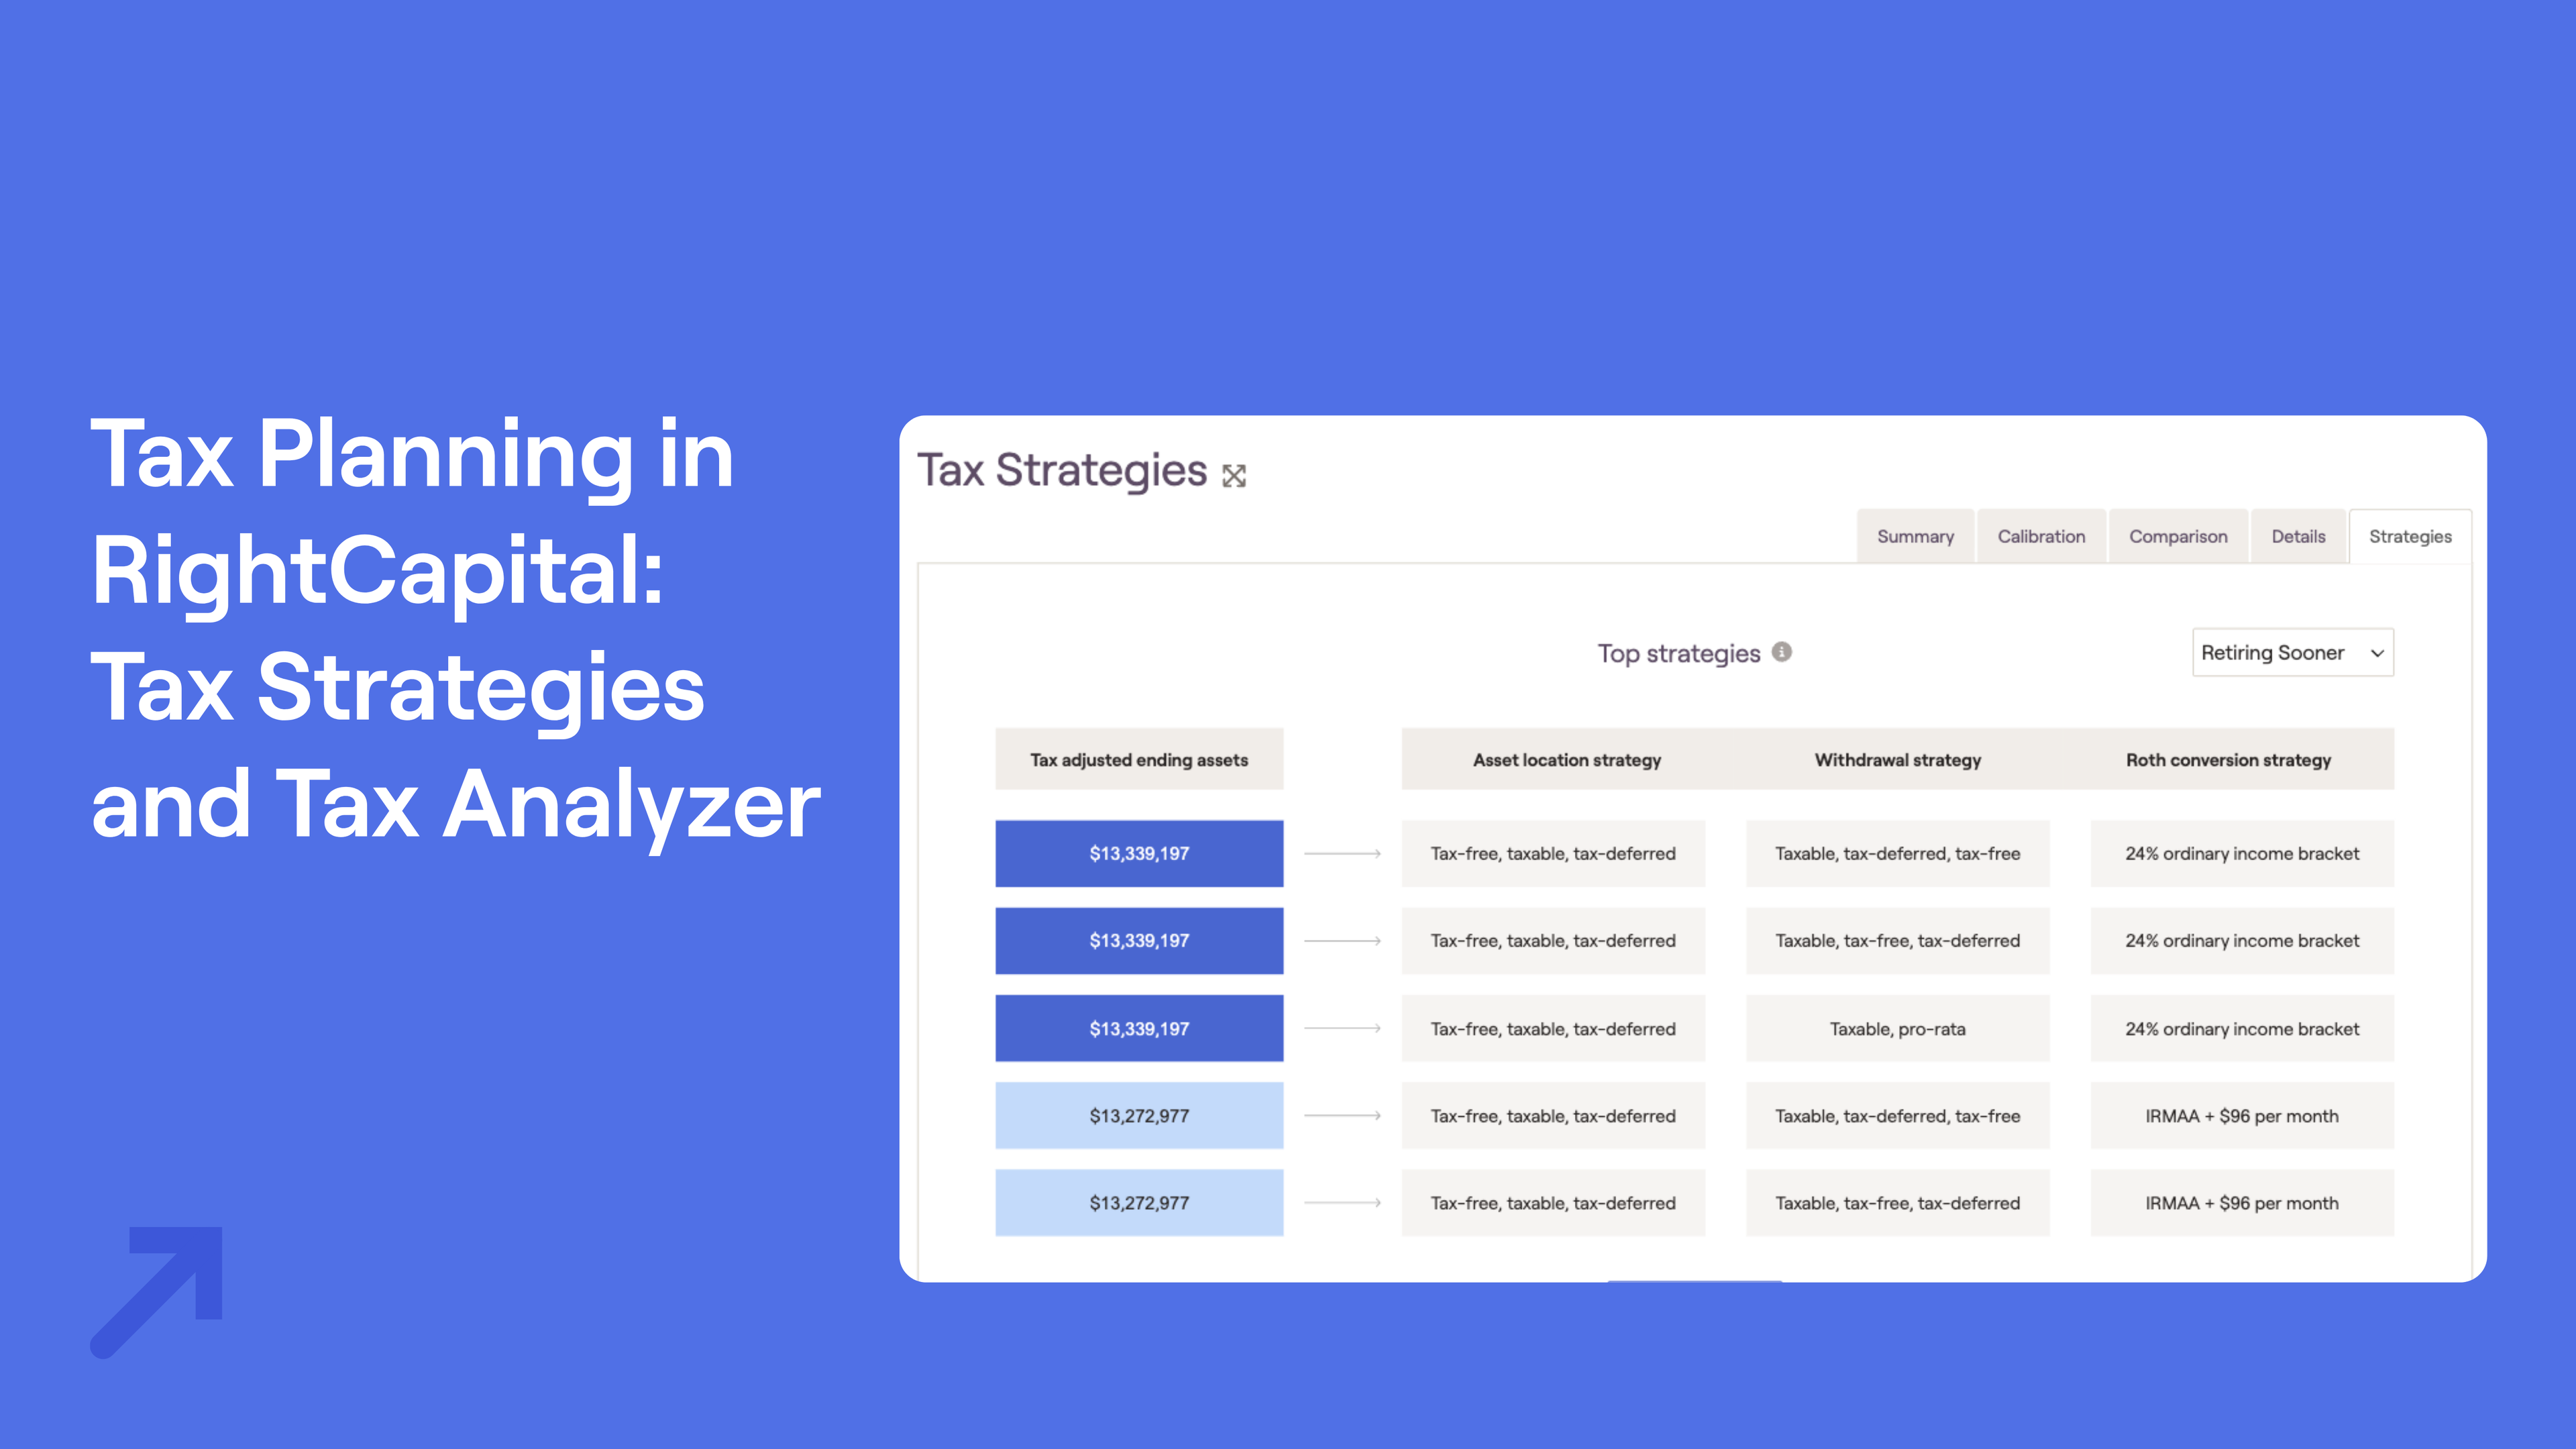
"How can I pay less in taxes over my lifetime?" | Roth conversion, withdrawal, and asset location strategies within the Tax Strategies tool, plus charitable strategy modeling |
"What's the smartest way to give?" | Cash, appreciated assets, donor-advised funds (DAFs), and qualified charitable distributions (QCDs) |
"What should I do with my stock options?" | Exercise and liquidation strategies for incentive stock options (ISOs), non-qualified stock options (NQOs), restricted stock units (RSUs), and restricted stock, with dedicated module for current path & proposed strategy analysis |
"What happens when I sell my business?" | Robust business modeling, including a dedicated business module illustrating businesses’ net worth, impacts of sale proposals, distribution strategies, and more |
"Is my family protected?" | Life insurance protection need vs. current and proposed coverage, and income replacement need with human life value calculator |
How can advisors show clients where their estate will go?
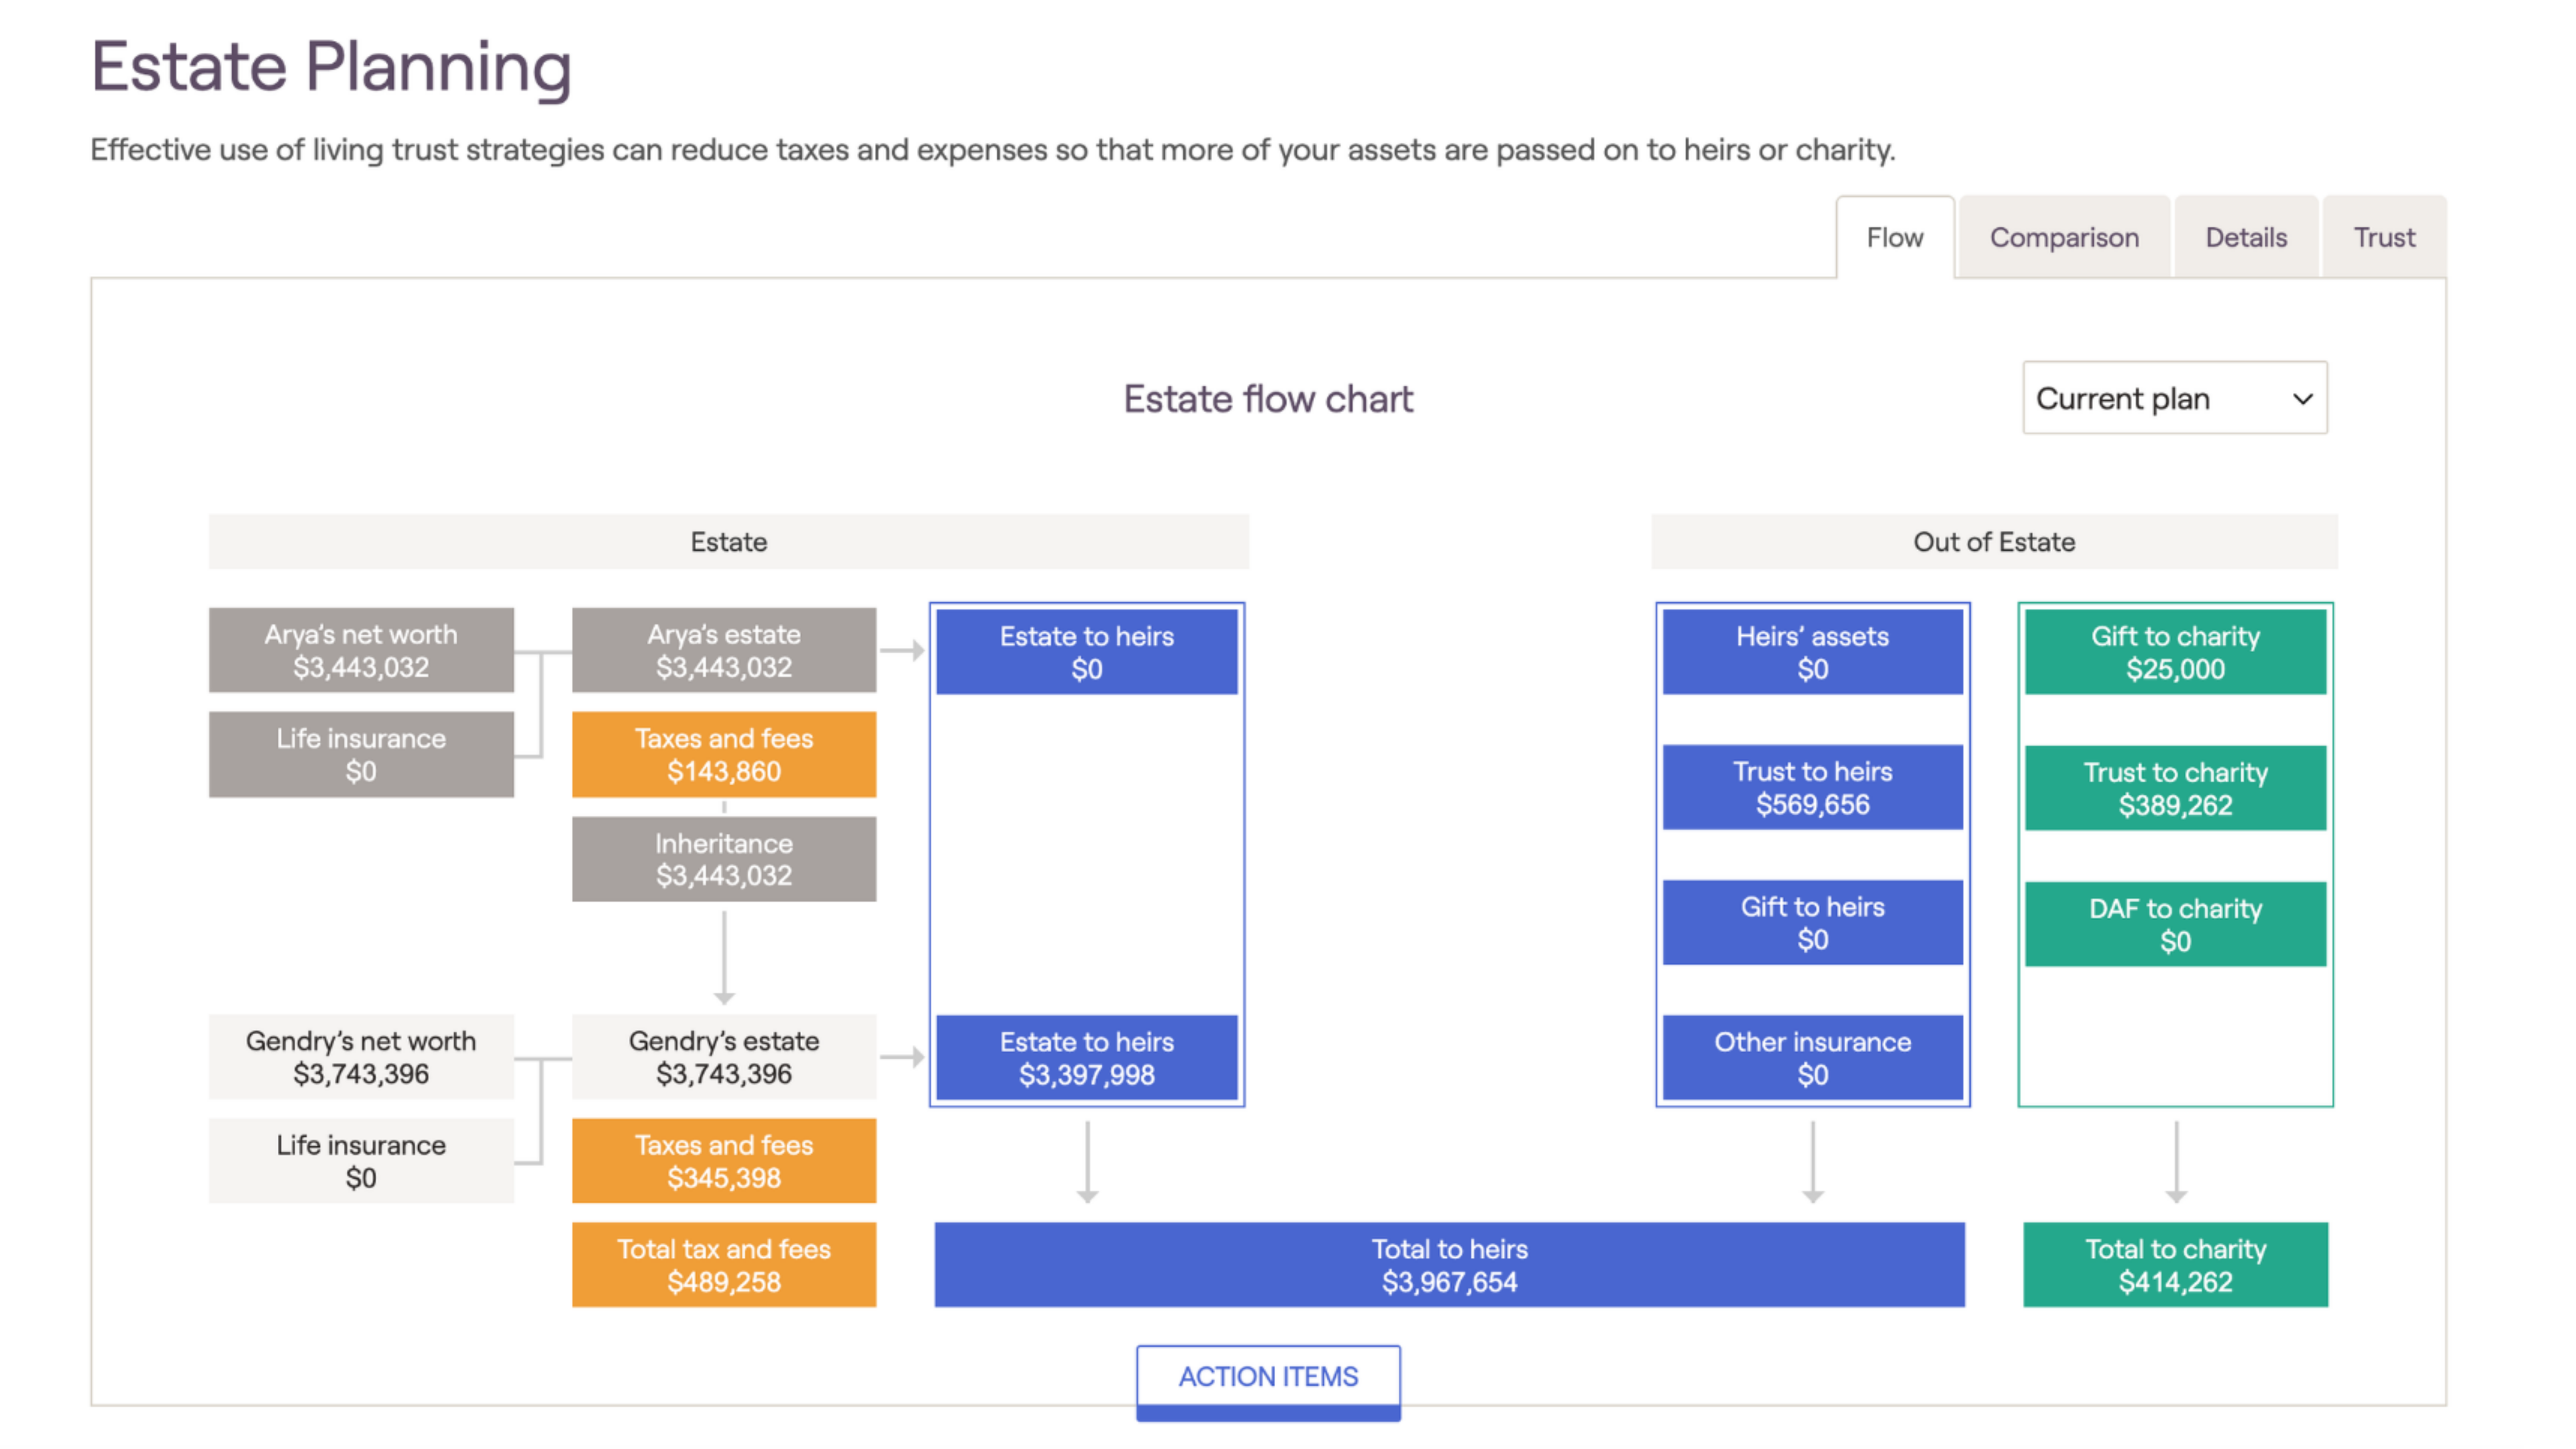
Visuals make estate conversations easier for clients to follow. RightCapital calculates state estate tax based on the client's state of residence at the end of the plan, including a planned move. Only 12 states and the District of Columbia have their own estate tax, so where a client lives at the end of the plan can make a big difference. For clients who stay in a state with an estate tax, the exposure can be significant, because those taxes often apply at much lower thresholds than the federal exemption. RightCapital also captures tax that may be due to other states on vacation or rental properties held there.
Advisors can also show how timing changes the picture by adjusting planning horizons, funeral and probate expenses, prior lifetime gifts, and Deceased Spousal Unused Exclusion (DSUE). For blended families, you can set the share of each account type that passes to the surviving spouse, so the plan reflects assets that go directly to children from a previous relationship.
Patrick Williford, CRPC®, of Carolina Financial Advisors, who works mainly with high-net-worth families, uses RightCapital’s estate module to start legacy conversations:
We can give them a number, 'based on these assumptions, your heirs are looking at $X million.' Are you okay with that? Do you want to leave them more? Less? That's a tool we use a significant amount.
Which trusts can advisors model for high-net-worth clients?
RightCapital supports more than 10 trust types. Advisors can model existing trusts or propose new ones and show the effect on heirs, charity, and estate taxes.
Trust types supported in RightCapital include:
- Credit shelter trusts (CST)
- Charitable remainder trusts (CRT) and charitable lead trusts (CLT)
- Irrevocable life insurance trusts (ILIT)
- Spousal lifetime access trusts (SLAT)
- Qualified terminable interest property trusts (QTIP)
- Qualified personal residence trusts (QPRT)
- Grantor retained annuity trusts (GRAT)
- Intentionally defective grantor trusts (IDGT) and other irrevocable grantor trusts
You can propose several trusts at once, demonstrate funding them now or in a future year, and include or exclude each one to show clients the difference. A side-by-side comparison shows the current plan next to the proposal, including what heirs receive, what goes to charity, total taxes and fees, and retirement income. Each irrevocable trust also gets an annual cash flow projection of balances, returns, taxes, fees, and distributions.
For some clients, this side-by-side view is far clearer than a spreadsheet. Thomas Marki, CPA, CEPA®, of AXIOM Founders Family Office recalls:
We had a client looking at a $15 million CRAT [charitable remainder annuity trust] and donor-advised fund combination. The Excel models from the outside team made his eyes glaze over. I went into RightCapital and in less than 20 minutes showed him both strategies, side by side, with real numbers.
How does the One Big Beautiful Bill Act change estate planning for HNW clients?
The One Big Beautiful Bill Act (OBBBA) permanently raised the federal estate and gift tax exemption to $15 million per individual and $30 million for married couples starting in 2026, indexed for inflation. Here, "permanent" means there's no longer a scheduled sunset. Future legislation could still change the exemption.
Estate planning is also about more than federal tax. Clients with estates near or above $30 million, or who live in states with their own estate tax, still benefit from regular reviews of trust and gifting strategies.
How do advisors keep estate documents and beneficiaries organized?
RightCapital's Estate Checklist is a space to keep track of whether clients have key documents, such as a will, power of attorney, living will, healthcare proxy, and living trust. It also records details such as executor and guardian names and when each document was last updated. A Beneficiary page has a customizable list to indicate primary and contingent beneficiaries for each account.
Advisors can add custom checklist sections for items specific to a household. Beneficiary options include household members, a charity, a trust, all children, all grandchildren, or a custom recipient. Clients can store finalized documents in RightCapital's secure Vault, so everything is in one place when the family needs it.
How can advisors reduce lifetime taxes for high-net-worth clients?
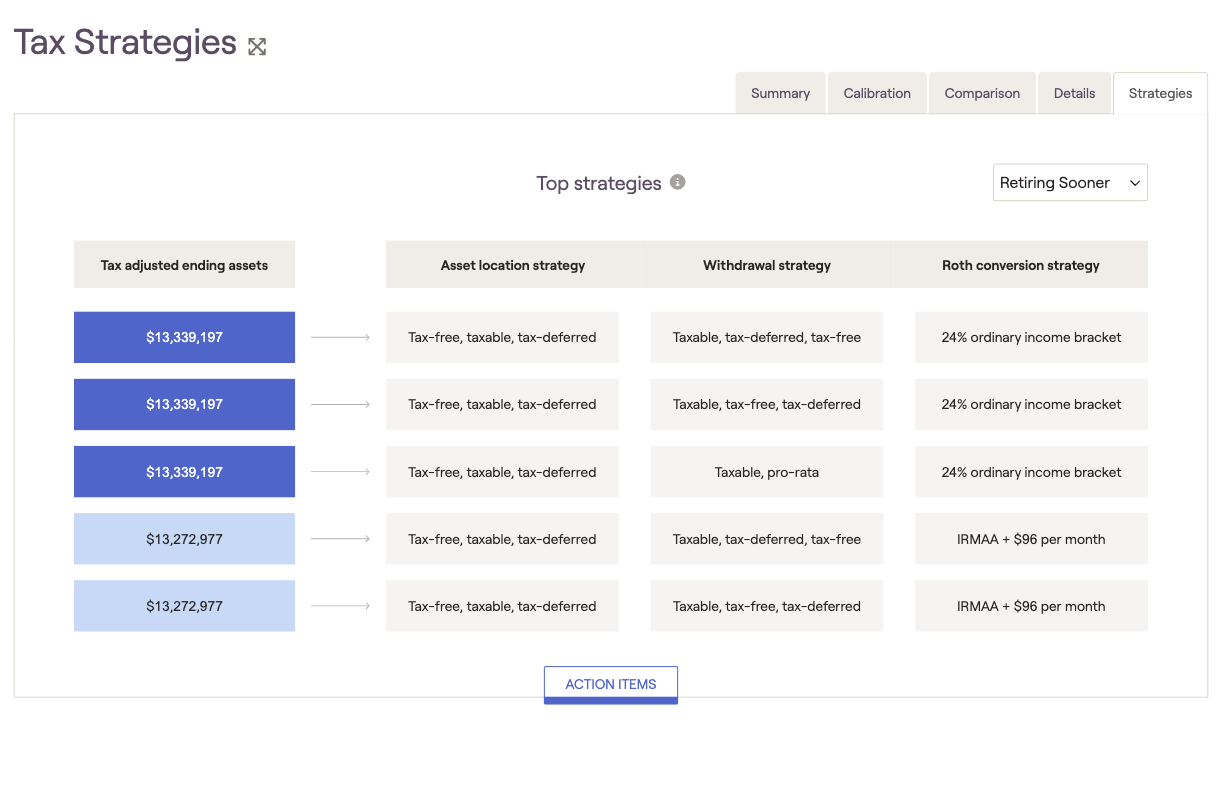
- Roth conversions and distributions: Convert or withdraw as much as possible without crossing a chosen bracket. Targeting Medicare income-related monthly adjustment amount (IRMAA) thresholds, or avoiding them altogether, helps clients avoid surprise Medicare surcharges.
- Withdrawal sequence: Test which order of drawing from taxable, tax-deferred, and tax-free accounts leaves the client with more.
- Asset location: Show how placing equities in taxable, tax-deferred, or tax-free accounts changes long-term results, which can be valuable for clients in high brackets today.
Advisors can compare a proposed strategy side by side with the client's current one, including the effect on federal taxes paid, required minimum distributions (RMDs), invested assets, and tax-adjusted ending wealth. For clients focused on legacy, an estimated terminal tax rate accounts for the tax heirs would still owe on inherited tax-deferred accounts. Advisors who aren't sure where to start can let RightCapital solve for the top five strategy combinations at once, then apply the chosen strategy to the client's retirement plan.
Roth conversions are a core part of Williford's work with high-net-worth families:
Most clients in the affluent, high-net-worth sphere have heard about Roth conversions from their friends. But when they see the tax allocation chart saying 'this much is pre-tax, this much is tax-free, this much is taxable,' it can be surprising. They've got a tax bomb waiting to go off if we don't do something about it.
How can advisors lower a high-net-worth client's taxes this year?
For HNW clients still in their earning years, tax-smart savings is often a great place to start:
- Maximizing pre-tax contributions to a 401(k) or similar workplace plan
- Contributing to a health savings account (HSA), which is pre-tax going in and can be tax-free for qualified medical expenses
- Grouping deductions in a single year to get past the standard deduction and itemize
Pre-tax savings lower adjusted gross income (AGI), which matters more for high earners under the OBBBA. The state and local tax (SALT) deduction cap rose to $40,400 in 2026, but it phases down for incomes above $505,000, so some clients near that threshold may be able to keep more of the deduction by reducing their income. OBBBA also added a new limit on itemized deductions for taxpayers in the 37% bracket and lowered alternative minimum tax (AMT) exemption phaseout thresholds. RightCapital's tax calculations reflect these changes.
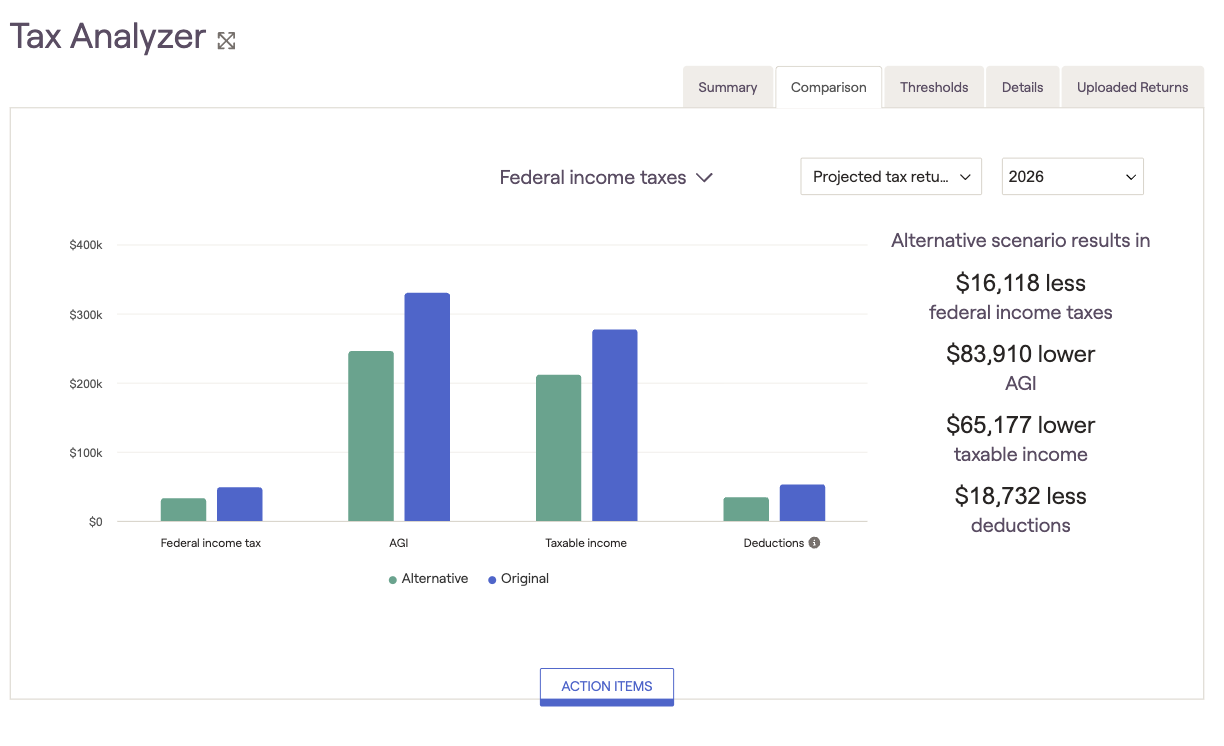
Tax Analyzer presents the results in ways clients can follow:
- A comparison of federal tax, AGI, taxable income, and deductions between the original and alternative scenarios
- Bracket charts showing how close the client is to the next ordinary income or capital gains bracket
- Color-coded indicators showing whether the client is eligible, partially eligible, or ineligible for various contributions, deductions, and credits
- Line-by-line details of the tax return
Williford says this kind of analysis strengthens his work with clients' CPAs:
Having the power to come to the CPA with recommendations with the data to back it up is pretty exciting for me. And then you can actually quantify the tax savings at the end of the day. That shows real value.
For clients who itemize, charitable giving is often the next step.
Tax Analyzer is available on Premium and Platinum subscriptions.
How can advisors model charitable giving strategies?
RightCapital models cash gifts, gifts of appreciated assets, DAF contributions and grants, and QCDs. It automatically itemizes deductions when charitable gifts plus other deductions exceed the standard deduction, so clients see the actual tax effect of their giving.
Advisors can show clients:
- Gifts of appreciated stock that avoid capital gains tax
- Donor-advised funds, with the full deduction in the year the DAF is funded, even if grants go to charities in later years
- QCDs from an IRA, inherited IRA, or qualified annuity, which count toward required minimum distributions (RMDs)
- Charitable trusts, with CRTs and CLTs modeled alongside the rest of the estate plan
Marki described how this works with a real client:
We had a very charitable client donating $100,000 a year. He had highly appreciated stock he wasn't emotionally attached to and a high tax year. So we proposed donating $300,000 of stock to a donor-advised fund, three years of giving in one year. His lifestyle wouldn't change one bit, but he'd get a huge tax break. RightCapital let me show him the savings on the tax page with just a toggle, and that's a win-win for everybody.
How can advisors plan for real estate holdings?
RightCapital models investment properties, vacation homes, and land, including rental income, vacancy rates, depreciation, and passive loss carryovers. These details flow into the client's tax projections, which factor in passive loss and at-risk limits, plus the tax on recaptured depreciation when a property is sold.
Because rental income, expenses, depreciation, and taxes are built into the plan, clients can trust that their cash flows and retirement projections consider their real estate, including the proceeds and taxes in the year a property is sold. Advisors can also model converting a primary home into a vacation home or rental, or relocating to another state, with RightCapital automatically applying the new state's tax law from the year of the move. For clients looking to move real estate out of their taxable estate, a qualified personal residence trust (QPRT) can be modeled as part of the estate plan.
How can advisors plan for equity compensation?
RightCapital models ISOs, NQOs, RSUs, and restricted stock (RS), including 83(b) elections and cashless exercise, with AMT factored in automatically.
In the Stock Plans module, compare a client's current exercise and liquidation strategy with a proposed one to see the effect on invested assets, lifetime taxes, and how much of the portfolio is concentrated in company stock. Advisors can save time entering existing grants in a stock plan by uploading grants by CSV, copying an existing grant, or manually entering the individual grant. Vesting schedules can be built as a template to reuse across clients, or enter a unique custom vesting schedule within a client specific stock plan.
How can advisors plan for business owners?
RightCapital’s Business module has key visuals analyzing clients’ business, with the ability to create different strategies for business revenue, expenses, distributions, and the business sale. Propose an alternative sale tactic, including a lump-sum or installment sale and visualize its effect on the client's invested assets and taxes, then easily apply the curated proposal to the full plan. For business owners whose company makes up most of their net worth, that means planning the exit strategy and the life after it together.
How much life insurance does a high-net-worth family need?
RightCapital's Life Insurance module calculates a protection need, or the minimum death benefit that would keep a surviving spouse from running out of money before the end of the plan. Advisors can compare that need with current coverage and proposed additional coverage.
Advisors can set exactly when a death occurs in the plan and add the goals, expenses, and other changes that would follow. To keep a death benefit out of the taxable estate, an ILIT can be modeled in the estate analysis module.
How can AI help advisors scale planning for high-net-worth clients?
Iris™, RightCapital's AI financial planning agent, helps advisors deliver HNW planning more efficiently:
- Find Opportunities reviews a plan in the focus areas you choose, including Tax, Investments, Retirement, Insurance, Debt, Stock Plans, Business, and Estate. It then suggests strategies tailored to that client.
- Double Check looks for issues such as missing cost basis, duplicated entries, and incomplete data entry.
- Cash Flow Review delivers a prioritized analysis of a client's plan, with key metrics for easy reference such as probability of success, median ending portfolio value, and ending net worth. For HNW households, it might surface issues such as steep spikes in asset withdrawals, show what's triggering them, and identify which parts of the plan have the biggest impact, so you know where to focus before a review meeting.
- Plan Builder lets you set a target probability of success, choose what the client is open to adjusting, and receive multiple options, each with specific changes, key considerations, and the resulting probability of success.
- Document Upload allows you to upload files such as annuity illustrations, stock grant agreements, insurance policies, or statements, then ask Iris to summarize them or answer questions. Iris can also reference documents in the client's Vault.
Iris is available on Premium and Platinum subscriptions.
Where does planning software fit alongside estate attorneys and CPAs?
Financial planning software such as RightCapital models the effects of estate, tax, and trust strategies. It doesn't draft legal documents or file tax returns. For HNW clients, advisors typically use RightCapital to test scenarios, then work with estate attorneys and CPAs to put the chosen strategies in place.
That's where advisors add the most value. Showing a client how a SLAT or CRT changes what their heirs receive (before they pay for legal work) helps them make an informed decision. It also makes the advisor the coordinator of the client's broader team.
The opportunity
High-net-worth households hold a growing share of U.S. wealth, and many still don't have a comprehensive financial plan. Advisors who offer estate, tax, charitable, and business planning can build stronger relationships, keep clients longer, and attract wealthier ones. The right technology makes that work sustainable as your practice grows.
See how RightCapital can help you serve high-net-worth clients. Schedule a demo and start a 14-day free trial.
Frequently asked questions
High net worth usually means at least $1 million in investable assets, not counting a primary residence. Capgemini's World Wealth Report uses this definition and classifies individuals with $30 million or more in investable assets as ultra-high-net-worth. Individual advisory firms often set their own thresholds.
RightCapital supports more than 10 trust types, including credit shelter trusts, CRTs, CLTs, ILITs, SLATs, QTIPs, QPRTs, GRATs, IDGTs, and other irrevocable grantor trusts. Advisors can model existing trusts or propose new ones and compare the results with the current plan.
Yes. RightCapital models cash gifts, gifts of appreciated assets, donor-advised fund contributions and grants, and qualified charitable distributions from IRAs, inherited IRAs, and qualified annuities. RightCapital automatically itemizes deductions when they exceed the standard deduction.
Yes. RightCapital's Tax Analyzer allows advisors to analyze a client's uploaded or projected tax return, then build an alternative scenario line by line. This shows the immediate impact of savings and deduction strategies on the client's taxes and eligibility for key deductions and credits. Uploaded returns are automatically redacted. Tax Analyzer is available on Premium and Platinum subscriptions.
AI tools such as Iris, RightCapital's AI planning agent, review client plans for opportunities in areas such as tax, estate, stock plans, and business. Iris also analyzes cash flows, builds strategy options to reach a target probability of success, flags possible data entry issues, and answers questions about uploaded documents.