Minimizing Retirement Tax Liabilities with Roth Conversions
May 25, 2023
Key Takeaways
- By moving money from traditional retirement accounts into a Roth during lower-income years, clients can pay tax now at a known rate to avoid potentially higher rates later.
- The “sweet spot” for conversions is often the window between retirement and the start of Social Security and RMDs.
- In RightCapital, advisors can model conversions up to ordinary income, capital gains, or specific Medicare premium (IRMAA) brackets, and show clients comparisons of tax savings, retirement income, and ending wealth.
Simply put, a Roth Conversion strategy can reduce clients’ taxes during retirement and add more tax-free assets to a client’s estate. This allows clients to spend their hard-earned money on more fun expenses, such as vacations or spoiling their grandchildren. The concept can almost seem too good to be true, so being able to demonstrate your proposed plan to clients in a way they understand is vital.
As advisors know, traditional IRAs and 401(k) retirement savings accounts build up over time with tax-deferred contributions. When individuals start to receive distributions from these accounts, they are taxed according to their current tax brackets.
The first years of retirement are usually spent in a lower tax bracket since individuals have stopped receiving paychecks but haven’t yet dipped into retirement accounts. This window of time is when advisors may recommend clients pay a portion of those taxes early, by converting traditional funds into Roth IRAs. Roth conversions can be combined with other strategies, such as delaying Social Security, to expand that narrow window. Once RMDs kick in and distributions need to be taken, individuals will be in a higher tax bracket once again.
The optimal Roth conversion timing can be tricky. One reason is that Medicare premiums are based on modified adjusted gross income (MAGI) of the two previous years. Roth conversions increase the taxable income in the years they are taken. Another reason is that to avoid IRS penalties and fees, there should be at least five years before Roth conversions and accessing those funds. It also might be worth looking into conversions during a down market to minimize the taxes, while the account still has a chance to grow further, since the Roth IRA funds will be the last distributed over retirement.
If you have the right financial planning software, getting the timing right can be a little easier. RightCapital, for example, has an option where you can slide to “fill in the tax bracket” to make sure clients are making the most of their time in the lowest tax brackets.
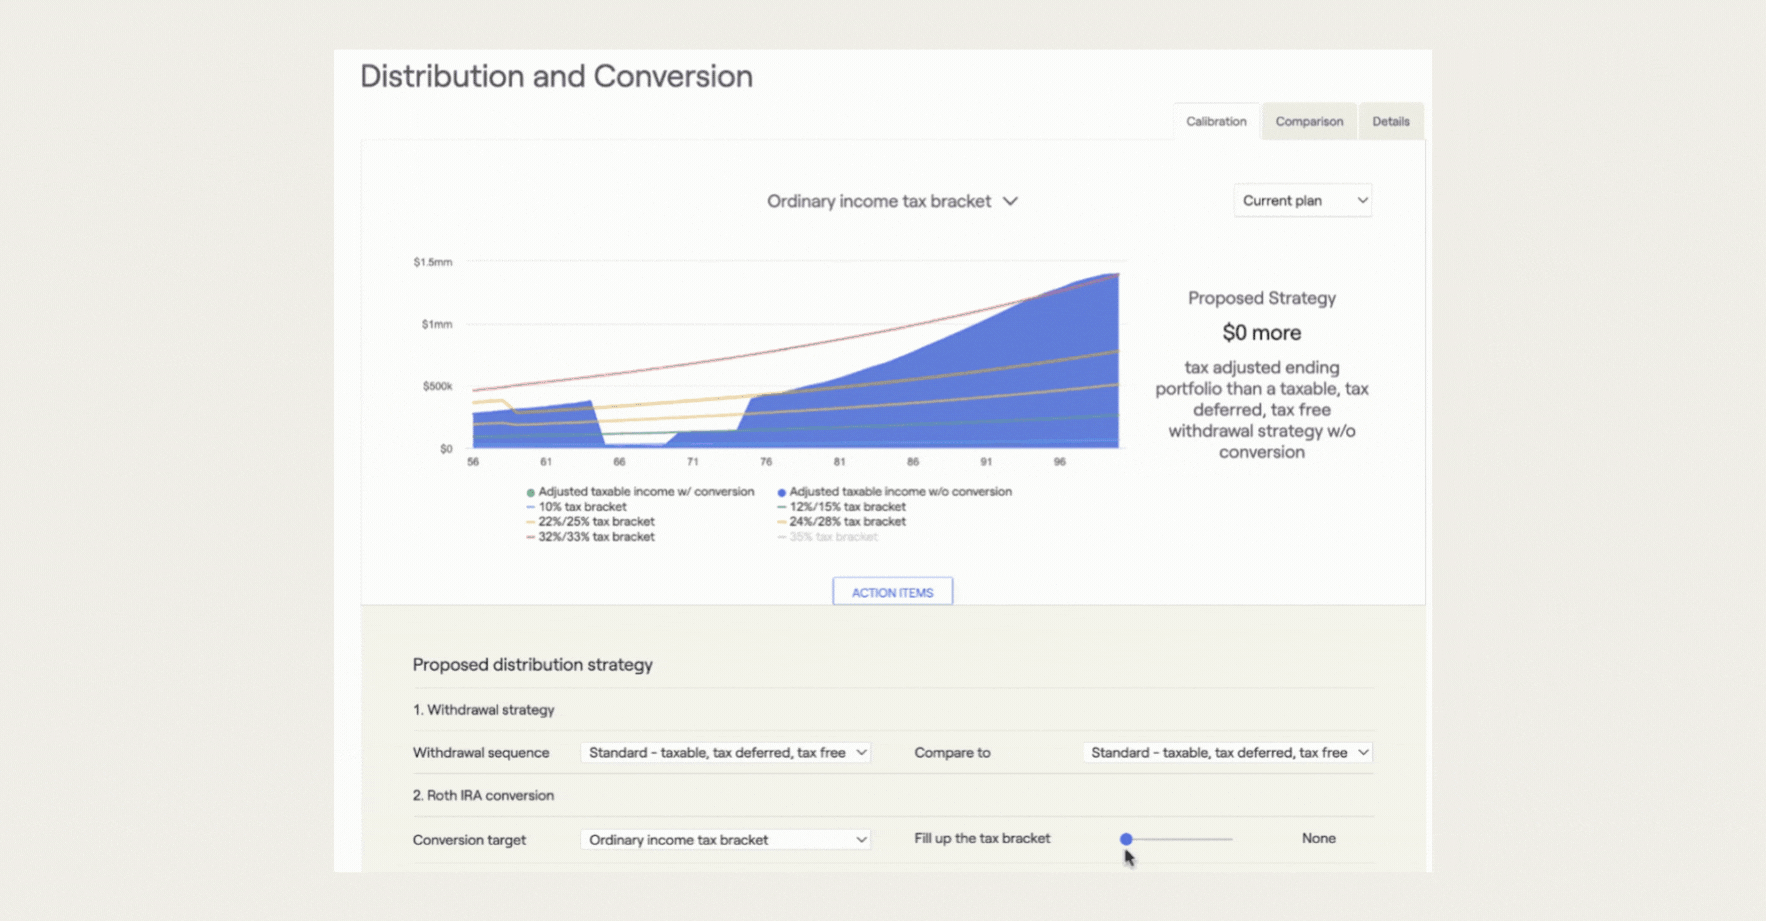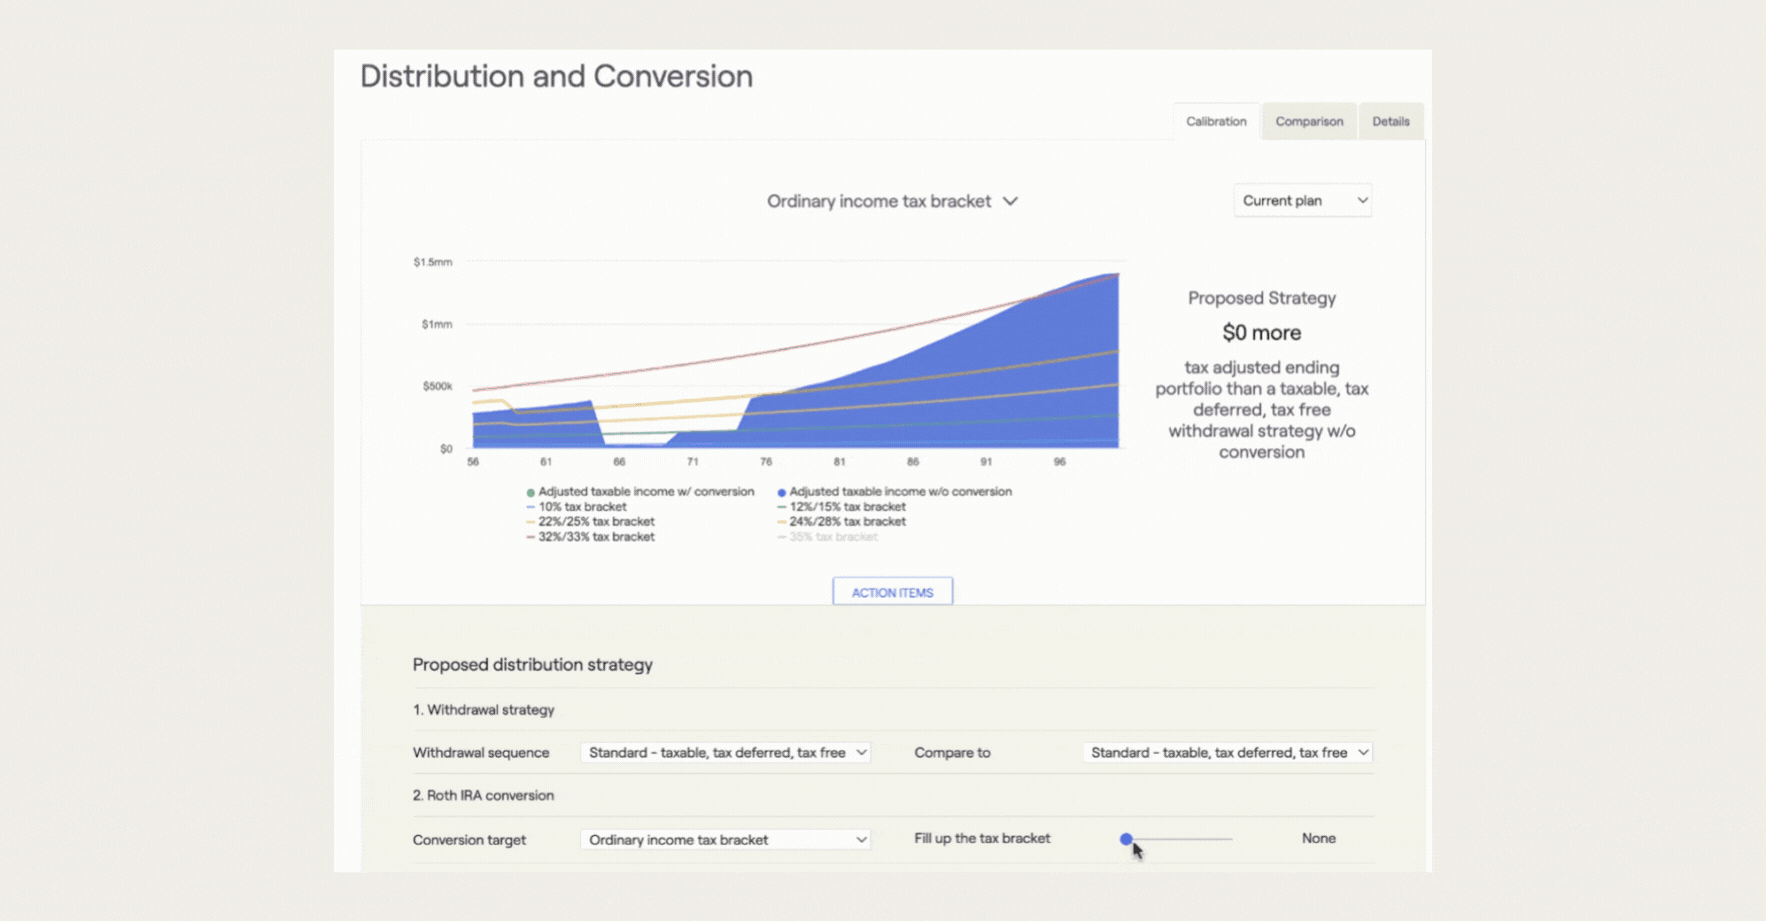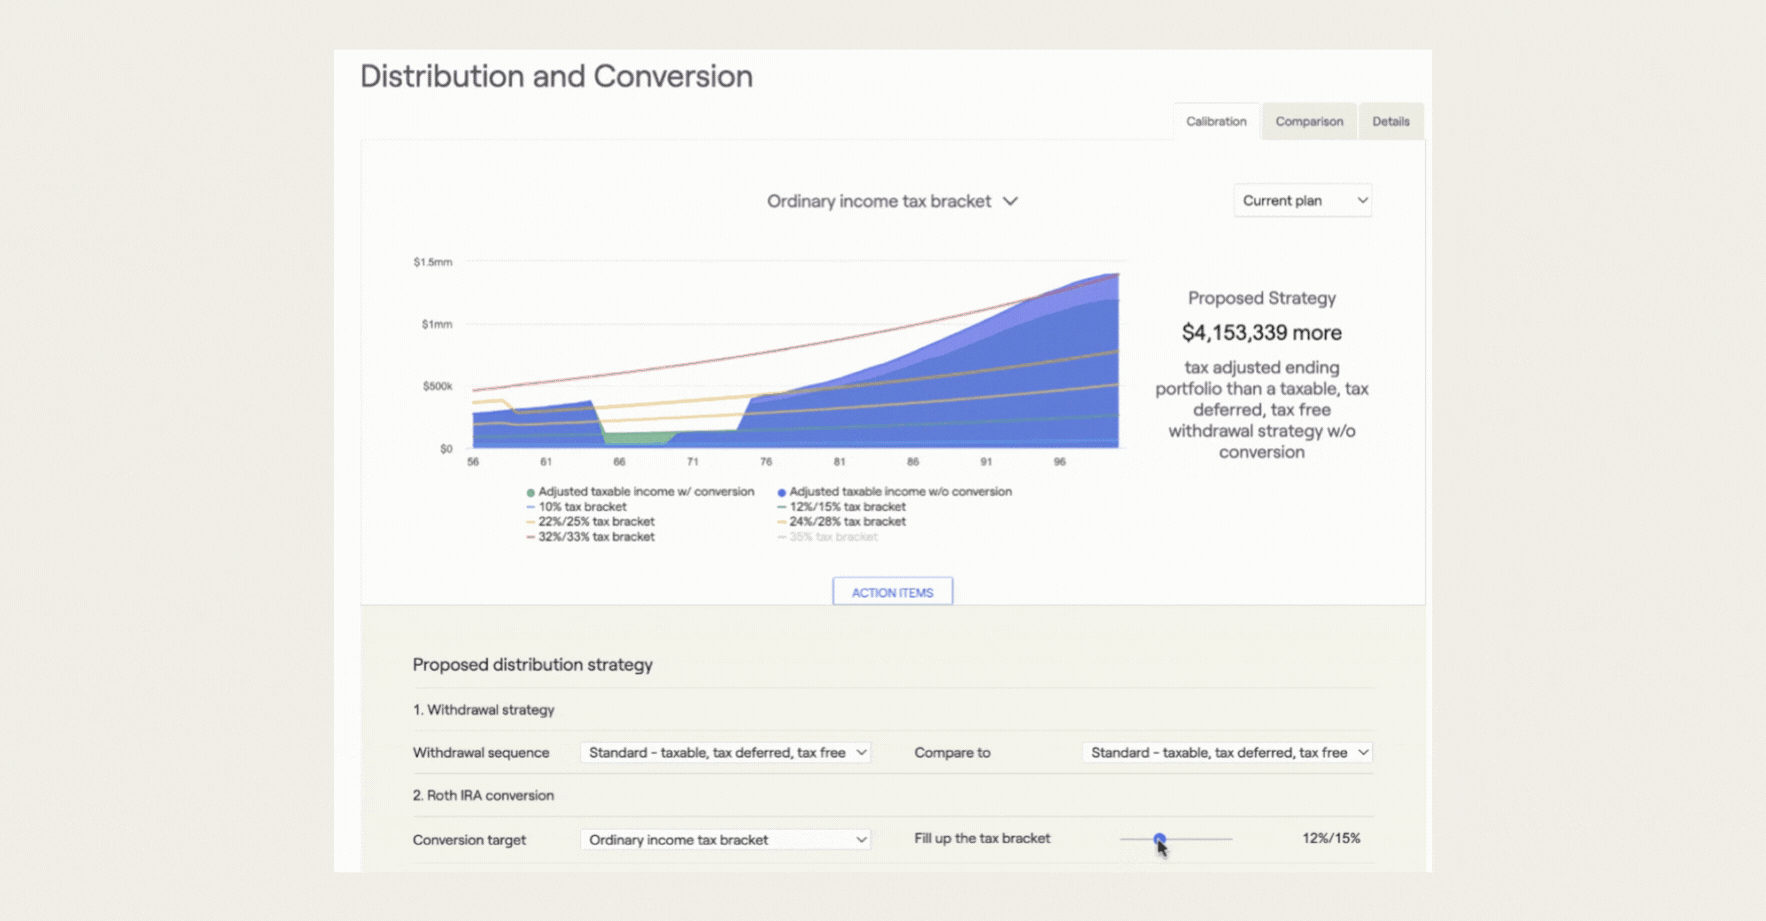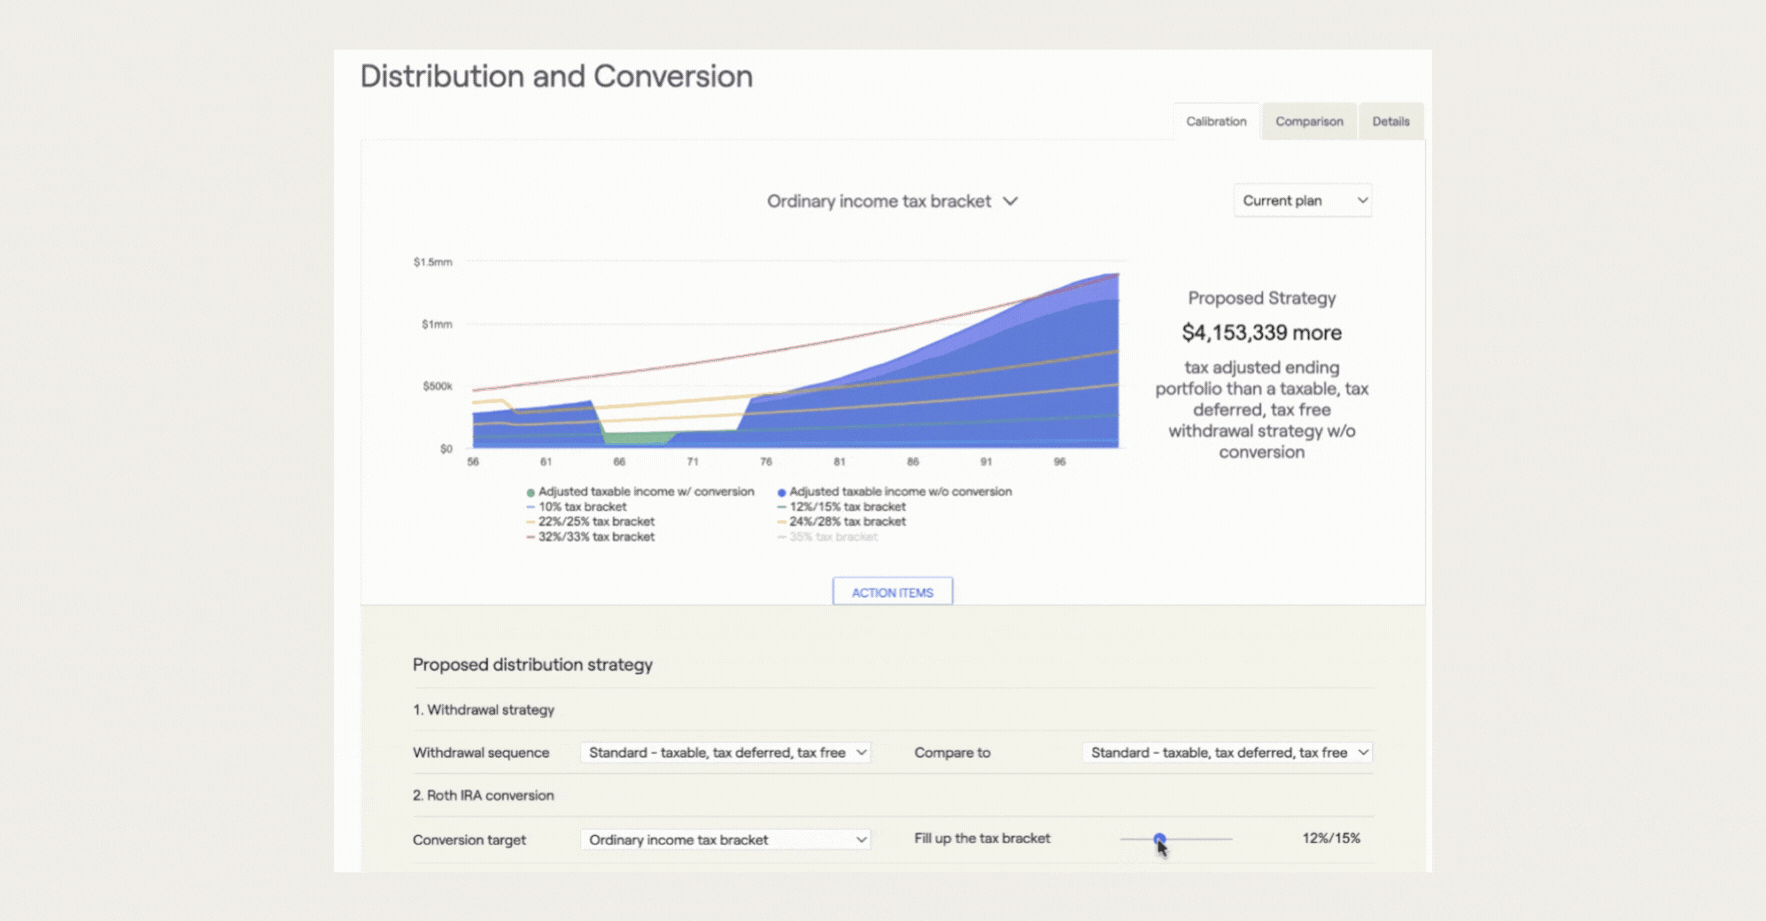
RightCapital can help illustrate your Roth conversion proposals. For example, there are visuals to show what distributions would look like in a variety of tax brackets—ordinary income, capital gains, and Medicare—and graphs comparing the impact on tax-adjusted ending wealth, withdrawal, account balances, Required Minimum Distributions, and federal tax paid for separate strategies. Daniel walks through a number of the visuals in our Tax module in the below video:
So it's all here to tell a story. The story generally is, what is the benefit of potentially executing a Roth conversion in the plan? And we can say, not only is that potentially going to reduce required minimum distributions later on, and maybe save taxes, but it's also going to have you showing more ending adjusted portfolio value than a pro-rata strategy without conversion.
And we can also use the comparisons tab to directly compare those two strategies. So here is the comparison of one strategy versus another. We see the Roth conversion strategy ends with more ending assets. It ends with a higher amount of tax-free assets. And ultimately you can also use these action items to simulate what's the estimated tax rate that might be applied on the tax deferred assets at the end of the projection. So this is where you might be able to say, here's the additional benefit of the tax-free assets. If the beneficiaries of your accounts in the future are being hit with a 22% tax bracket, the account with more tax deferred assets is going to end with less value than the account with tax-free assets that wouldn't be taxed as they're passed potentially to the beneficiary. So this allows you to simulate a 10-year distribution rule for someone who inherits these assets in the future, and you can show the impact of being driven into a higher tax bracket with that.
But ultimately, these graphs are here to help simulate the impact of my proposed strategy on account balances over time. We can see the Roth accounts growing in blue there with the tax-free assets. We can see the impact on required minimum distributions, starting at 75 with those new SECURE Act scenarios. So we can see what that looks like, and we can even see the impact on total federal taxes paid, which is significant. Because we can say there's a fair amount less in total taxes paid with our proposed strategy than with our pro-rata strategy without conversion.
And all of this data is going to react to the information that we align here. So as we toggle these around, we're going to see immediate impacts overall. We can toggle this around and see what it looks like, everything from apples to apples to adjusting different strategies and seeing the impact. So this is a really important opportunity to identify that we can have specific conversations around tax efficient distributions. We can have specific conversations around the client's assets over time and their taxes paid. And it's all designed to be conceptualized here within this tax distributions module, so that you can look at the different options, talk about what might be best for the client, and hopefully help them understand how their future may or may not benefit from these different strategies that they might be considering.
So as I switch back to my calibration tab here again, I'll reiterate, we're comparing these sequences. A standard sequence is being compared, but the only difference is that we're filling up an income tax bracket and we're seeing the benefit over time.
It’s also easy to model existing Roth conversion strategies while creating plans in RightCapital. The below video walks you through it, but essentially, additional distribution cards can be added in the income section during the six-step data-entry process.
If the client is, as of right now, expecting to execute some Roth conversions, we'd be able to see, in the profile income area, the ability to add income and create an income distribution. This is how we would pull money from a specific qualified account to execute a Roth conversion.
So I would click the add income distribution card, which opens up a new toggle here for me to say that Tommy is going to execute a Roth conversion. From a certain timeline, we can say that may be from Tommy's 401K accounts, for example. We might be targeting a Roth conversion from 2033 to 2035, and each year Tommy's converting $50,000. So this is a Roth conversion I could set up. I'm saying that I'm distributing funds from Tommy's 401K accounts, or maybe the IRA accounts, and I'd like to set those to occur over a two or three year timeline here.
For the type, I'm going to indicate that I'm converting this to a Roth IRA. Keep in mind, that's the toggle here, and that's a key, important step. Then I can let the rest stay as is. We don't want to change the taxation on this, but as I hit save, we've locked in a Roth conversion into this client's plan.
And to see that tracking through the future cash flows, I would visit the retirement tab, which allows me to access those future cash flow projections under the retirement subtab, cash flows.
If you’d like to learn more about using RightCapital to help streamline Roth conversion planning, schedule a 1:1 demo today!