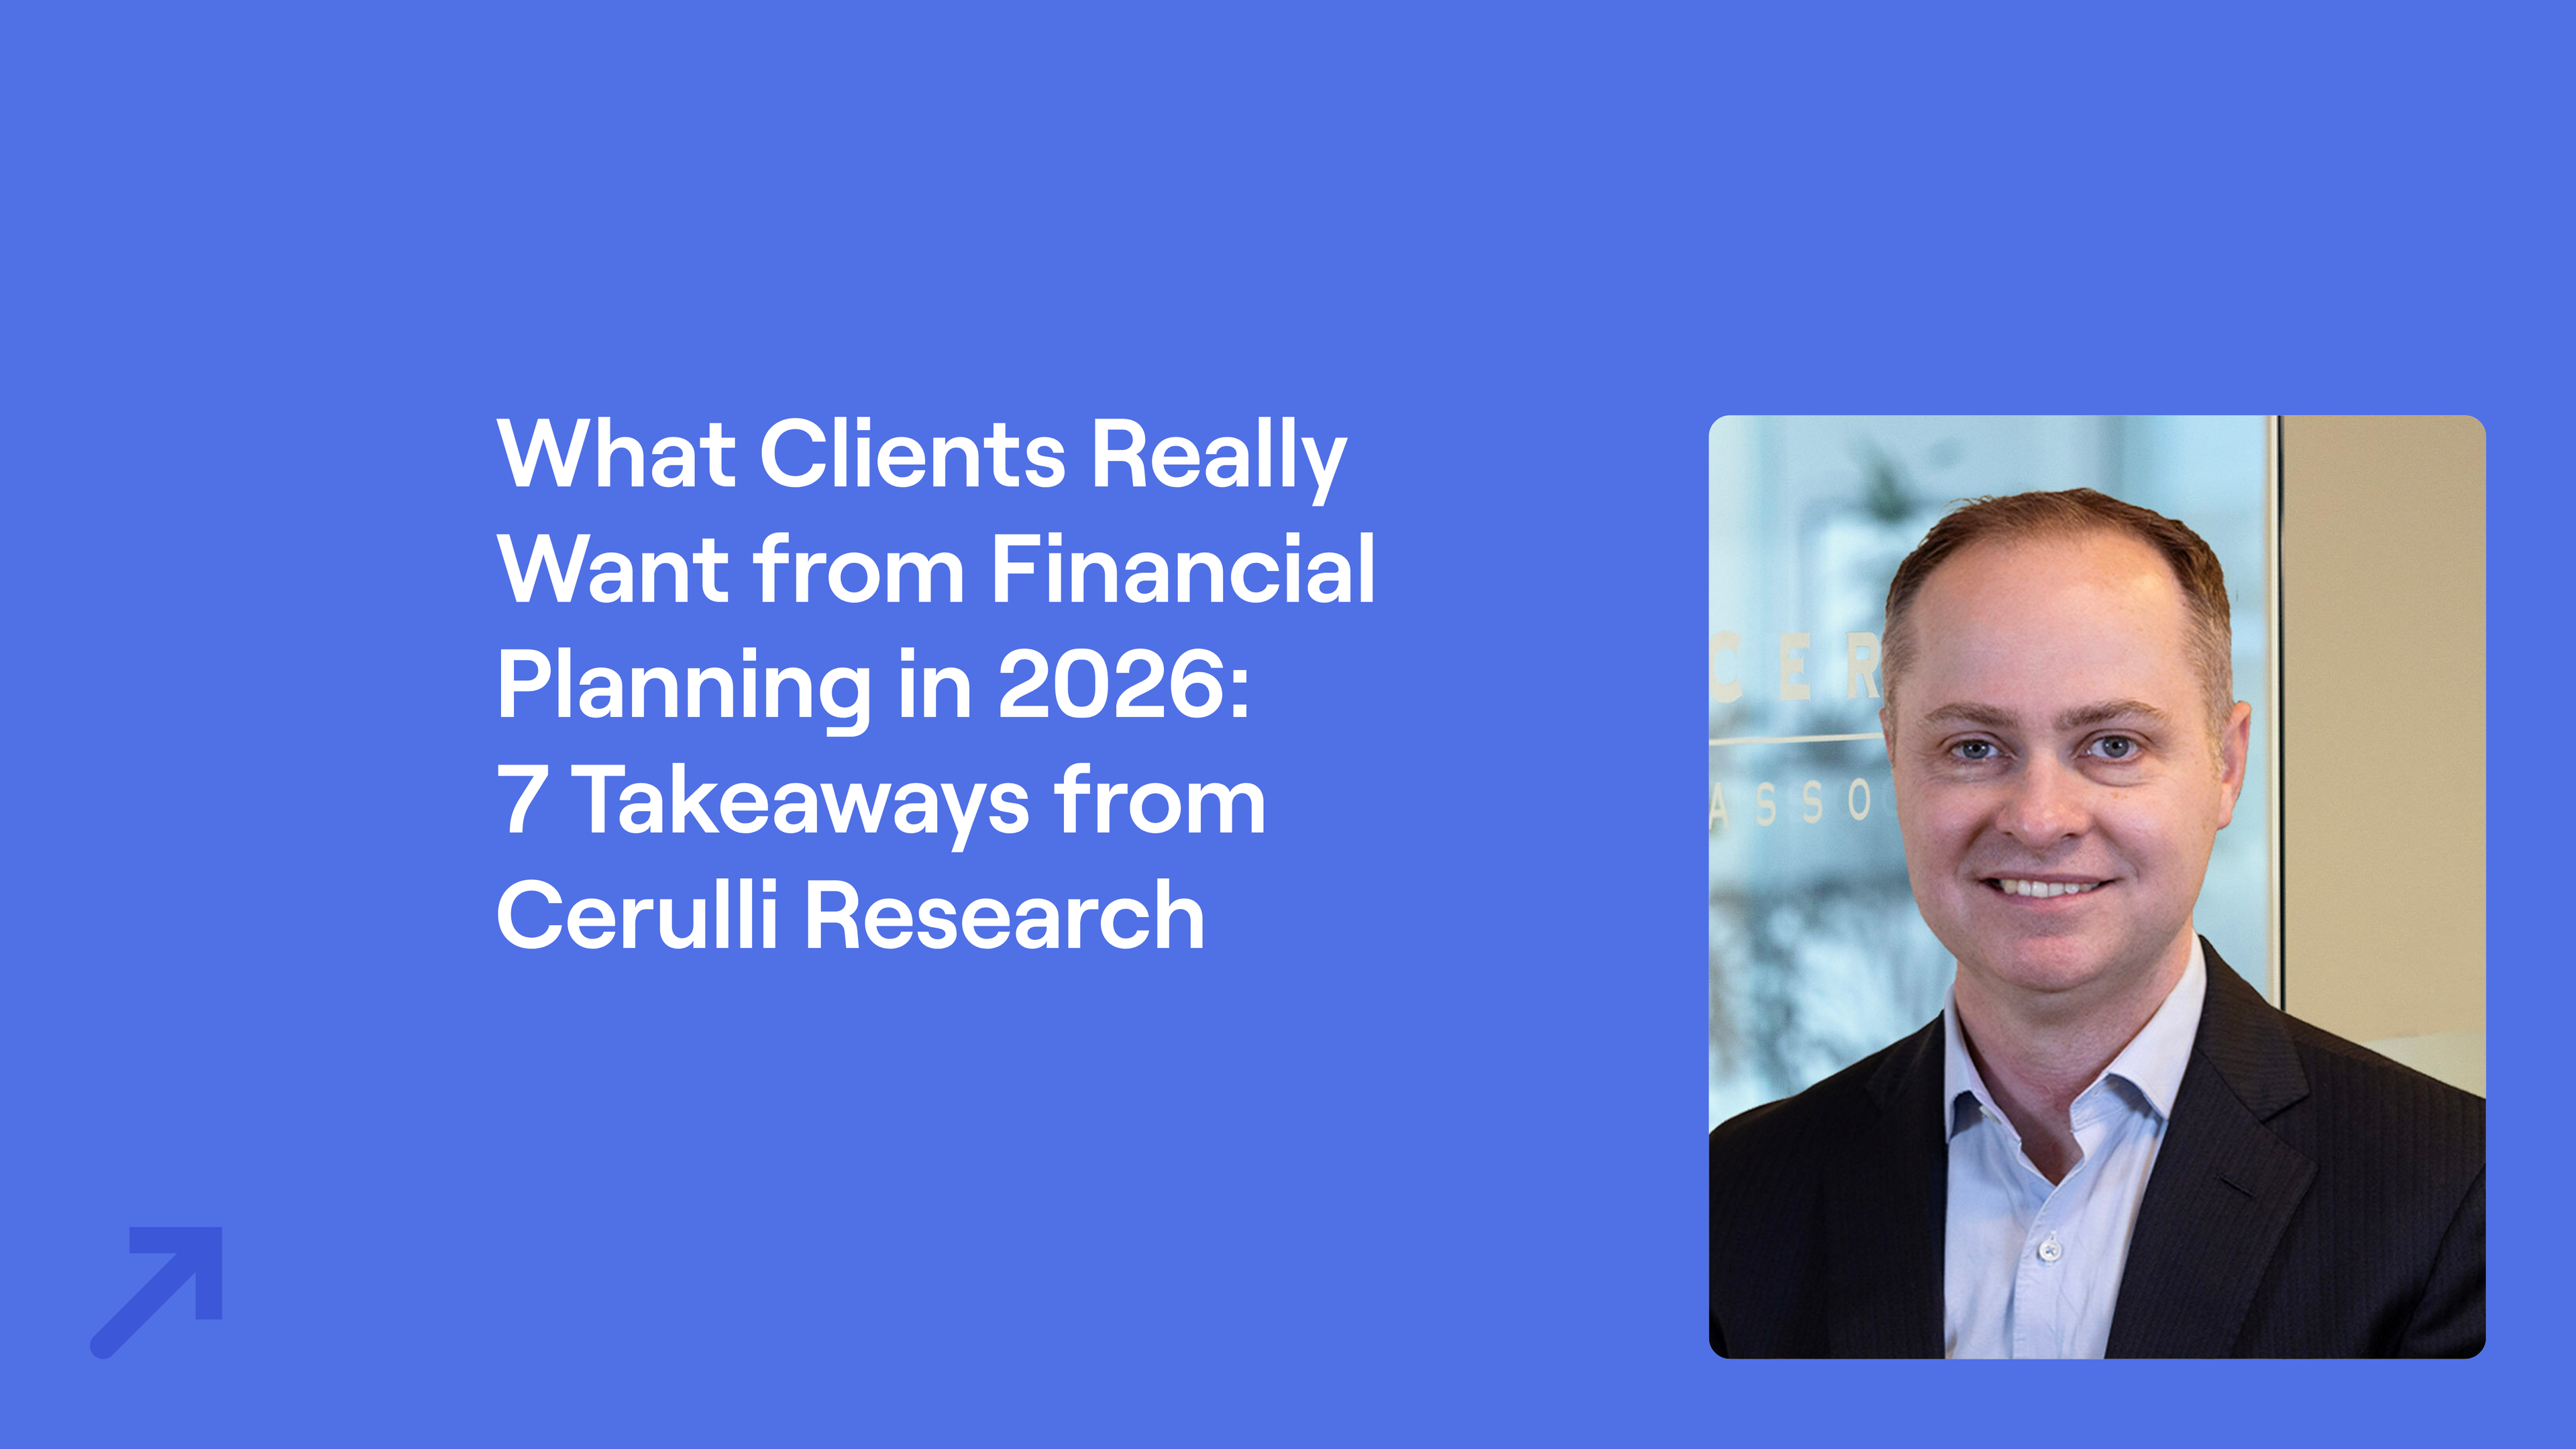
What Clients Really Want from Financial Planning in 2026: 7 Takeaways from Cerulli Research
October 20, 2026
Key Takeaways
- Cerulli's research shows households with more than $5 million now hold 57% of U.S. household financial assets, up from 30% in 2010.
- According to Cerulli's U.S. Retail Investor Solutions survey, more investors are willing to pay for financial advice, and roughly 78% say having a financial plan is important.
- Advisor fees have held steady at around 1% even as the services expected for that fee keep growing.
- Cerulli's data shows 31% of advisors call themselves wealth managers, but only about 7% meet Cerulli's criteria.
- Advisors in Cerulli's survey rank a tedious planning process for clients as their top challenge in delivering financial planning and lack of integration as their biggest technology frustration.
What do clients really want from financial planning in 2026? According to research from Cerulli Associates, they want more of it, they're willing to pay for it, and the wealthiest clients, who now control most U.S. financial assets, expect comprehensive planning well beyond investment management.
At this year's RightInsights virtual event, Michael Rose, CFP®, MST, Director of Wealth Management at Cerulli Associates, shared Cerulli's proprietary research on how client expectations are reshaping financial planning and what advisors need to do to keep up. His main point was simple: "The future of advice belongs to financial advisor practices that deliver comprehensive planning at scale."
1. Wealth is shifting upmarket and planning needs are becoming more complex
Rose called this the data point that "still shocks me": Cerulli's research shows that in 2010, households with more than $5 million held 30% of U.S. household financial assets. By 2025, that share had grown to 57%. Over the same period, according to Cerulli, households with more than $20 million went from holding 10% of all financial assets to more than a quarter.
That means high-net-worth and ultra-high-net-worth households now make up a much bigger share of the market. "They have more wealth and more complex financial needs," Rose explained, "so they need more financial planning services to support those needs."
Cerulli's data also shows that as household assets grow, clients are much more likely to receive comprehensive planning instead of ad hoc or goals-based advice, which raises the bar for any advisor working to move upmarket. When Cerulli compared practices focused on high-net-worth clients in 2017 and 2024, it found they had expanded into estate planning, tax preparation and planning, philanthropic planning, and even helping clients handle their bills. Financial planning itself is now offered by nearly all of these practices. To compete for these clients, you'll need to offer a broad array of services.
2. Clients are more willing than ever to pay for financial advice
Cerulli's retail investor survey shows that investors' willingness to pay for financial advice has grown significantly over the last 15 years. The same research finds that more investors now work with an ongoing financial advisor instead of investing on their own or getting one-off advice.
That's good news for advisors, but it comes with higher expectations. According to Cerulli's most recent data, roughly 78% of retail investors say having a financial plan is important, well above where that number was 10 years ago. Finding clients who want advice isn't the hard part. Meeting clients' rising expectations is the real challenge.
The industry is moving in the same direction. Cerulli's advisor data shows that more clients who historically were not receiving financial planning are now receiving it as part of their ongoing relationship with their advisor and at broker-dealers. Rose described "a monumental shift over the last 10 years away from brokerage and toward an ongoing investment advisory service offering that is fiduciary-based and, frankly, more aligned with the client's interests."
3. Clients value retirement planning almost as much as investment management
When Cerulli asks investors which advisor services they value, investment management still ranks first. But Cerulli's research shows retirement planning ranks almost as high. "I think that speaks volumes about the importance of offering at least core retirement planning as part of an advisor's financial planning repertoire," Rose said.
According to Cerulli's survey, employer benefits analysis, budgeting and cash management, income tax planning, and executive compensation planning also rank well. Michael pointed to employer benefits planning as an especially promising niche: advisors who get to know one employer's benefit plan in depth can build a strong source of new clients while developing real expertise.
4. Advisors are doing more for clients, but fees are steady
In Cerulli's advisor survey, the biggest benefits advisors attribute to financial planning are stronger client relationships, better client retention, and the chance to bring in held-away assets. That matters because, as Cerulli's measurements show, most growth in assets under management across the industry comes from market gains, not new business.
Fees, however, are a different story. Active asset managers have seen significant fee compression, while according to Rose, advisor fees have stayed fairly consistent at around 1%. What's changed is how much advisors deliver for that fee. "They're doing more for the same fee," Rose said, "which is pushing them to think about how to deliver financial planning services more efficiently." Planning is also much harder to scale than investment management, so margins get squeezed.
Rose acknowledged that "it's easy for me to sit here and say, 'Just do more planning.' But you need to find the capacity to do that, and most advisors are capacity-constrained."
His answer is to find that time elsewhere. Cerulli's research shows more advisors are outsourcing parts of investment management, such as using third-party models or TAMPs for portfolio construction, or simplifying trading, rebalancing, and cash raises. In Rose’s words, advisors are looking at their process "to see where they can cut the fat and create efficiency without reducing the value they offer clients." The time saved can go toward planning.
5. Financial planner vs. wealth manager: Many advisors overestimate how much planning they offer
Cerulli groups advisor practices into four personas based on how much financial planning they deliver:
- Money managers focus primarily on investment management, with little financial planning
- Investment planners focus on portfolio management and offer financial planning as needed
- Financial planners lead with planning but tend to offer a narrower range of services than wealth managers
- Wealth managers offer the broadest range of planning services, often including income tax, estate, executive compensation, and stock option planning, and tend to serve high-net-worth clients
Cerulli assigns each practice to a persona based on factors such as the share of clients receiving planning, the credentials on staff, and the range of services offered. It also asks advisors to choose a persona for themselves. "Our data shows that advisors tend to think their practices incorporate more planning than the marketplace would benchmark them at," Rose said:
- 31% of advisors call themselves wealth managers, but Cerulli classifies only about 7% as wealth managers
- 58% call themselves financial planners, but Cerulli classifies only 27% as financial planners
Rose’s advice was to take an honest look at how deep and broad your planning services really are and how they compare with your peers'. The gap isn't a criticism. It's a sign of how much room most practices have to grow, especially as client expectations keep rising.
6. Technology helps, but the planning process and integrations still get in the way
When Cerulli asked advisors about the challenges of delivering financial planning, they ranked "the process is too tedious for some clients" first. Close behind were limited staff and clients who don't have the time or willingness to take part.
Because the barrier is the experience itself, anything that makes it easier for clients to get started directly increases how many of them take you up on planning. "The only way to solve it is to make sure clients see you as a trusted advisor and to grease the rails so the planning process is as simple as possible," Rose said. A client portal where clients can enter their own information and upload documents, such as the one in RightCapital, is one way to take some of that work off their plate.
Technology has been, in Rose’s words, "a game changer in helping deliver planning at scale and improve the client experience." Cerulli's data shows nearly every planning-focused practice uses general financial planning software, and adoption of specialized tools, especially for estate and income tax planning, is growing. Cerulli has also tracked a major shift away from static PDF reports toward interactive conversations, where advisors adjust scenarios in real time during meetings. Either option is available in RightCapital.
Of course, more tools can also complicate things, and in Cerulli's advisor survey, lack of integration is by far the biggest technology challenge. When Rose addressed this point during the RightInsights webinar, he said, "I'm pretty confident a lot of people on the other end of the screen are nodding their heads right now.”. According to Cerulli, integrations are improving, and many wealth management firms are building shared data platforms, with AI potentially tying applications together.
7. Teams, talent, and AI will shape the future of financial advice
Team-based practices are growing faster
Cerulli's practice-level research shows team-based practices can hire specialists (CIOs, paraplanners, CPAs), offer more services, and grow faster organically than solo practices. According to Rose, "bringing that expertise in-house is a significant competitive advantage," which helps explain the industry's shift toward team structures.
More advisors are retiring than entering the industry
Cerulli's data indicates the industry is reaching an inflection point where more advisors will retire than enter the business, and according to Rose, traditional rookie training programs fail 70% or more of the time. He expects more new advisors to start on teams as paraplanners or client service reps, where they can add value right away and learn the business from senior advisors.
AI will support advisors, not replace them
Rose doesn't see AI as a threat to advisors the way robo-advisors were once expected to be. Instead, it's already helping them work more efficiently.
Cerulli's recent benchmarking study of AI use at enterprise RIAs found that AI notetakers are the most widely used AI tool among those firms. According to advisors, they're cutting the time it takes to follow up with advice after a meeting, which used to take as long as a week or two.
Rose believes the industry is "in the bottom of the first inning" with AI: "I don't think it's very likely that AI will replace the advisor. I think it will empower advisors and enable them to deliver their services more efficiently."
The bottom line
Cerulli's research paints a clear picture: clients want more advice, their needs are getting more complex, and they're willing to pay for it. The advisors who succeed will make planning central to their value, then use technology, team structure, and operational efficiency to deliver it at scale without hurting margins.
Want the full session? Watch the recording of What Clients Really Want from Financial Planning in 2026.
Cerulli Associates is a market research and consulting firm specializing in asset and wealth management. The research Rose shared draws on Cerulli's annual surveys of financial advisors, its retail investor survey of about 4,000 investors per year (with consistent questions for more than a decade), its bottom-up market sizing research, and a recent benchmarking study of AI use at enterprise RIAs.
Frequently asked questions
According to Cerulli Associates, clients increasingly are looking for comprehensive financial planning, not just investment management. Cerulli's research shows growing willingness to pay for advice, roughly 78% of retail investors saying a financial plan is important, and retirement planning valued almost as highly as investment management.
In Cerulli's advisor survey, the top challenge is that the financial planning process is too tedious for some clients, followed by limited staff and clients lacking time or willingness to participate. On the technology side, advisors cite lack of integration as their biggest frustration.
Michael Rose, Cerulli Associates, doesn't expect it to. He said AI is more likely to "empower advisors and enable them to deliver their services more efficiently." Cerulli's research shows AI notetakers are already the most widely used AI tool in advisory practices, helping advisors follow up with clients faster.