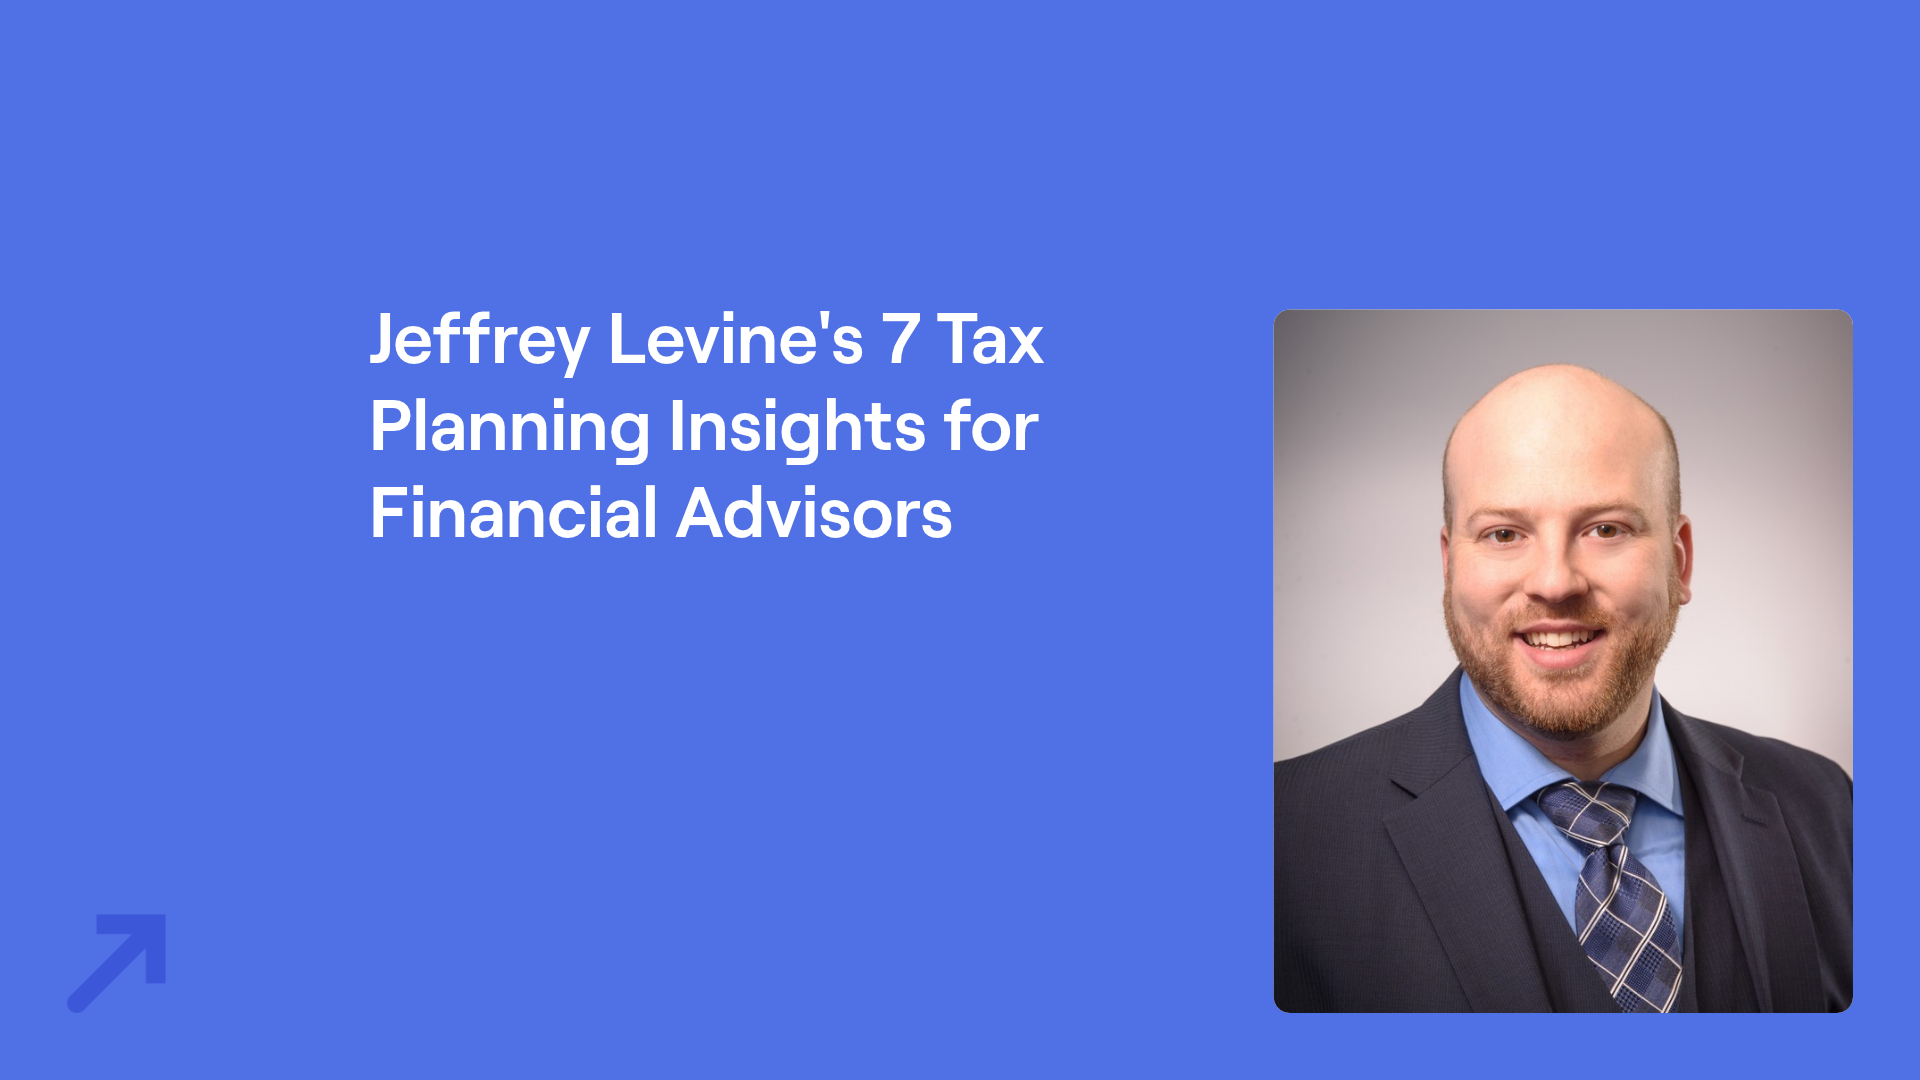
The Lowest Lifetime Tax Bill for Clients Is the Goal & 6 Other Tax Planning Insights from Jeffrey Levine
October 14, 2026
Key Takeaways
- More and more clients want tax planning from their financial advisor, and it's one of the few services that can show value both this year and over a lifetime.
- Jeffrey Levine argues advisors should manage a client's adjusted gross income (AGI), the "halftime score" of the tax return, and aim for the lowest lifetime tax bill, even if that means paying more tax in some years.
- Outside of a few hard lines, such as representing clients before the IRS or writing tax opinion letters, advisors have the ability to plan, project, and educate clients on taxes.
Tax planning for financial advisors has quickly moved from a nice-to-have to one of the most requested services in financial planning. The question for most advisors is no longer whether to offer it, but how to do it well without overstepping or getting buried in manual work.
At RightInsights, RightCapital's virtual event, Jeffrey Levine, CPA/PFS, CFP®, Lead Financial Planning Nerd for Kitces.com and Chief Planning Officer at Focus Partners Wealth, discussed “Integrating Tax Planning Across the Financial Plan.” He describes himself as "a financial advisor who's also a CPA, not a CPA who's a financial advisor."
Here are seven of the biggest takeaways from Levine’s RightInsights session, from AGI and lifetime tax bills to asset location and what advisors can legally say about taxes.
1. Clients increasingly want tax planning
More and more clients are seeking tax planning from their financial advisor, and Levine sees it quickly becoming a core part of comprehensive advice.
For a long time, advisors kept careful boundaries around anything labeled "tax" or "legal." Levine understands that instinct, but he pointed out that tax planning is part of the curriculum for CFP® certification and a core part of being an advisor. When thinking about comprehensive financial planning, Levine called out, "How can you do that without taxes?"
"You don't have to do tax planning to be a successful financial advisor today, but it sure helps," he said. "It is where the industry is trending, and it's what clients want." And when clients don't get it, Levine says they're inclined to "vote with their feet"—in other words, leave for another advisor who can provide what they’re looking for.
Tax planning is also one of the rare goals nearly every client shares. He joked, "I've never had someone walk into my office and say, 'I'm really looking for your help, Jeff, to pay a little bit more in taxes than I did last year.'"
Most importantly, tax planning proves its value in a way a portfolio often can't. A well-built portfolio may take decades to pay off, and being down just 8% when the market is down 10% "might really be a win, but it sure doesn't feel like a win to the client." Tax planning offers both immediate value ("I saved you $1,000 on your taxes this year") and long-term value in the form of more money to spend and pass on.
2. AGI is the "halftime score" of a tax return
According to Levine, most surtaxes, phaseouts, and Medicare premium thresholds are based on adjusted gross income (AGI) or modified adjusted gross income (MAGI), not taxable income. That makes AGI the number to manage.
"Income" means a lot of different things on a tax return: gross income, AGI, MAGI, taxable income, provisional income for Social Security, and more. Levine's favorite way to sort through it is a sports analogy.
In most games, nobody cares about the halftime score. On a tax return, though, "that halftime score, which to me is AGI, is really critical." (For anyone who remembers the old two-page Form 1040, AGI literally sat at the halfway point.)
Here's why. Taxable income, the "final score," really only matters for two things: tax brackets and the qualified business income (QBI) deduction. Nearly everything else is tied to AGI or some version of MAGI. That's where "bad things start to kick in on a tax return, like a surtax, or good things go away, like a credit or a deduction."
So much depends on AGI that the most effective strategies are often the ones that lower AGI, not just taxable income. Levine's example is charitable giving for clients who owe required minimum distributions (RMDs). When a client gives appreciated stock instead of using a qualified charitable distribution (QCD), their RMD still flows into AGI. Anything tied to AGI, such as the 3.8% surtax, Social Security taxation, and Medicare premiums, "might go up." The stock gift may earn an itemized deduction, but "that's only happening after AGI," he said. A QCD sends money directly from the IRA to charity and can count toward the client's RMD, so the donated amount stays out of AGI entirely, lowering both the halftime and final scores.
Levine added that for clients 70½ and older, which is the minimum age for a QCD, a QCD is typically the better choice. Appreciated stock that's held until death generally receives a step-up in basis, which erases the built-in capital gains tax. Money left in the IRA, on the other hand, will eventually be taxed as it's distributed. The difference is also easy to show: "I can show a client with software, if you give the appreciated stock, here's what your tax liability is going to be this year. By contrast, if you give via a QCD, here's how much lower it's going to be."
In RightCapital's Tax Analyzer, you can model this by reducing the client's taxable IRA distributions by the amount of the QCD. The comparison then shows the change in AGI and taxable income side by side, and the Thresholds tab shows whether the lower AGI shows keeps the client under any income limits for contributions, credits, or deductions.
3. The goal is the lowest lifetime (and multi-generational) tax bill
The best tax plan minimizes taxes over a client's lifetime, and sometimes across generations, even if that means paying more tax this year.
Levine draws a clear line between how CPAs and advisors tend to think. CPAs, he said, often look at the past and record what already happened. That's valuable work, but it naturally focuses on this year's return. "The realm of the financial advisor is the realm of the long term."
That long-term view is what makes strategies such as Roth conversions work. A conversion raises this year's tax bill by design. "But if more tax means lower tax overall in your lifetime, that's still a good move," Levine said. "He or she who pays the lowest lifetime tax bill wins the game."
For some clients, even a lifetime isn't a long enough horizon. Appreciated assets such as stocks and real estate generally receive a step-up in basis at death, which erases the built-in capital gains tax. Traditional retirement accounts don't get that treatment. Heirs generally owe income tax on distributions, so, as Levine put it, "that tax bill lives on for the next generation." For clients unlikely to spend everything they've saved, the goal becomes the lowest multi-generational tax bill.
That's why Levine sees tax savings as so valuable. A dollar saved in taxes is "even better than a dollar earned in the market, because if you earn a dollar in the market, usually some of that's gonna go to taxes."
4. Life events can create tax planning opportunities
Lowering a lifetime tax bill means smoothing income across the years, and life events often create the low-income years that make that possible.
Levine suggests picturing a bar chart of a client's income over the years. "The idea would be, how do we take the years that are a little bit higher, and transfer some of that to some of the years that are a little bit lower, and smooth out the bar chart."
The low years often come with life events. A large deductible medical expense, such as an entry fee for a continuing care retirement community, can open room for extra income. Marriage and divorce dramatically change how much income fits within each bracket. After a spouse's serious diagnosis, Levine has even accelerated Roth conversions or moved assets into the ill spouse's name to capture a step-up in basis. Age matters too. Converting a bit more at 62 can be smarter than spreading it into 63, when Medicare premiums start coming into play.
Levine believes advisors are uniquely positioned to catch these moments. A CPA may meet with a client once or twice a year, while an advisor often meets quarterly. "Who typically knows sooner when someone leaves their job? It's gonna be the financial advisor. Who knows when there's a birth or a death sooner? It's the financial advisor."
5. Tax planning vs. tax advice
Advisors who aren't CPAs, attorneys, or enrolled agents shouldn't represent clients before the IRS or write tax opinion letters. Outside of those limits, Levine says, most tax planning and projections are fair game.
When it comes to tax planning versus "tax advice," Levine separated two questions: what your firm allows and what the law allows. If your firm's policy is more conservative, follow it.
Legally, though, there are only a few hard lines. Showing a client how a Roth conversion might help, or how much more would be tax-free if they held qualified small business stock for five years instead of four, is allowed. As Levine put it, when advisors ask whether they can bring up tax-saving ideas and show projections, "from a legal perspective, the answer is absolutely yes."
He did add two important caveats. First, as a fiduciary, you owe clients competence, so you need the right knowledge, whether from the body of knowledge set by the Certified Financial Planner Board of Standards (CFP Board), programs such as RightInsights, or additional tax education. Second, if you're a solo advisor or small firm, check with your errors and omissions (E&O) insurance carrier to see where they draw the line and whether you need a specific endorsement or rider.
He also offered a handy reframe. When an advisor tells him they don't think they can show a Roth conversion projection, he asks whether their financial plans assume the client dies at some point, often at 95. "Is that giving the client actuarial advice? No, it's a projection." As long as you frame things as "here's what we project," you're on solid ground from a legal perspective (though, again, more restrictive firm-level policies should always be followed).
That's also where software comes in. "One of the things RightCapital is great at is incorporating tax projections into the overall financial planning process," Levine said. "When I talk to advisors who use RightCapital, one of the things that they always tell me they value the most is those integrated tax projections."
6. Asset location: Taxable, tax-deferred, and tax-free accounts
Asset location is the strategic placement of investments (such as equities and fixed income) across taxable, tax-deferred, and tax-free accounts to minimize tax drag without changing the client's overall asset allocation. Levine calls it “about as close to a free lunch as you can get.”
"If you're gonna own things, own them in the right accounts," he said.
Before deciding what goes where, advisors need to pick a method. Imagine a client with $500,000 in a Roth IRA, $500,000 in a traditional IRA, and a 50/50 target. Putting stocks in the Roth and bonds in the traditional IRA looks balanced, but the client doesn't really own all of that IRA money. In a 25% tax situation, their share is closer to $375,000, so on a net basis they're overweight in stocks.
Levine understands the logic of that "net" method but generally prefers the "gross" method, which simply uses account balances. Regulators tend to look at gross numbers and can be confused by an investment policy statement (IPS) that says 50/50 when the gross numbers say 60/40. Clients feel gross numbers too: "I've never had a client see their total portfolio go from a million dollars to $900,000 and walk in and go, 'Well, it's not so bad, it's only in the traditional IRA.'" Once taxable accounts with embedded gains are added in, the net math gets unruly fast.
After you've chosen a method, the question becomes what to put where. Many clients have some mix of taxable accounts, tax-free Roth accounts, and tax-deferred traditional IRAs, and Levine's framework covers all three:
Account type | First priority | Second priority |
|---|---|---|
Taxable account | Tax-efficient investments (ex. municipal bonds) | Low expected return |
Roth IRA | Highest expected return | Tax in-efficient investments |
Traditional IRA | Whatever is left over | n/a |
Even a heavily taxed investment doesn't cost much in a taxable account if it barely earns anything. If cash is earning half a percent, even a 50% tax rate only costs a quarter of a percent.
For the Roth, the logic flips: "If you're going to have something that grows tax-free, you might as well make it the thing that is growing the most."
As Levine emphasized that asset location isn’t necessarily an exact science. "It requires a lot of assumptions, and reasonable, well-educated advisors can, at times, disagree about those. So, it's really more, 'can we go in a directionally positive way for the client?'"
If you want to test this ordering with a client, RightCapital's Asset Location strategy lets you compare the default pro-rata split with filling one account type before moving to the next.
7. Tax planning is year-round
Levine's most practical tip for advisors building a tax planning practice was to block the calendar and batch the work into four windows:
- After filing season: Email every client who has filed and ask them to book 15 to 20 minutes and send their return. "The first one may take you a little bit longer, but by the second, the third, the fourth, it's going a lot quicker."
- After extension season: Repeat the process once October filers are done.
- Year-end: "The biggest time from a tax planning perspective is always at the end of the year," when income, gains, charitable plans, and fund distributions are mostly known.
- Early in the new year: Connect with the client's tax preparer so nothing falls through the cracks. "The less the client has to feel like they're schlepping information to the CPA…the more the client is going to appreciate that advisor's services."
For those post-filing reviews, clients can simply send a PDF of their return. In RightCapital, for example, Tax Analyzer reads it, redacts sensitive data, and surfaces last year's rates and key thresholds, turning a stack of returns into a series of quick conversations.
For more on building tax planning into client conversations, see 5 Insights from Michael Kitces on Tax Planning.
How RightCapital can help with tax planning
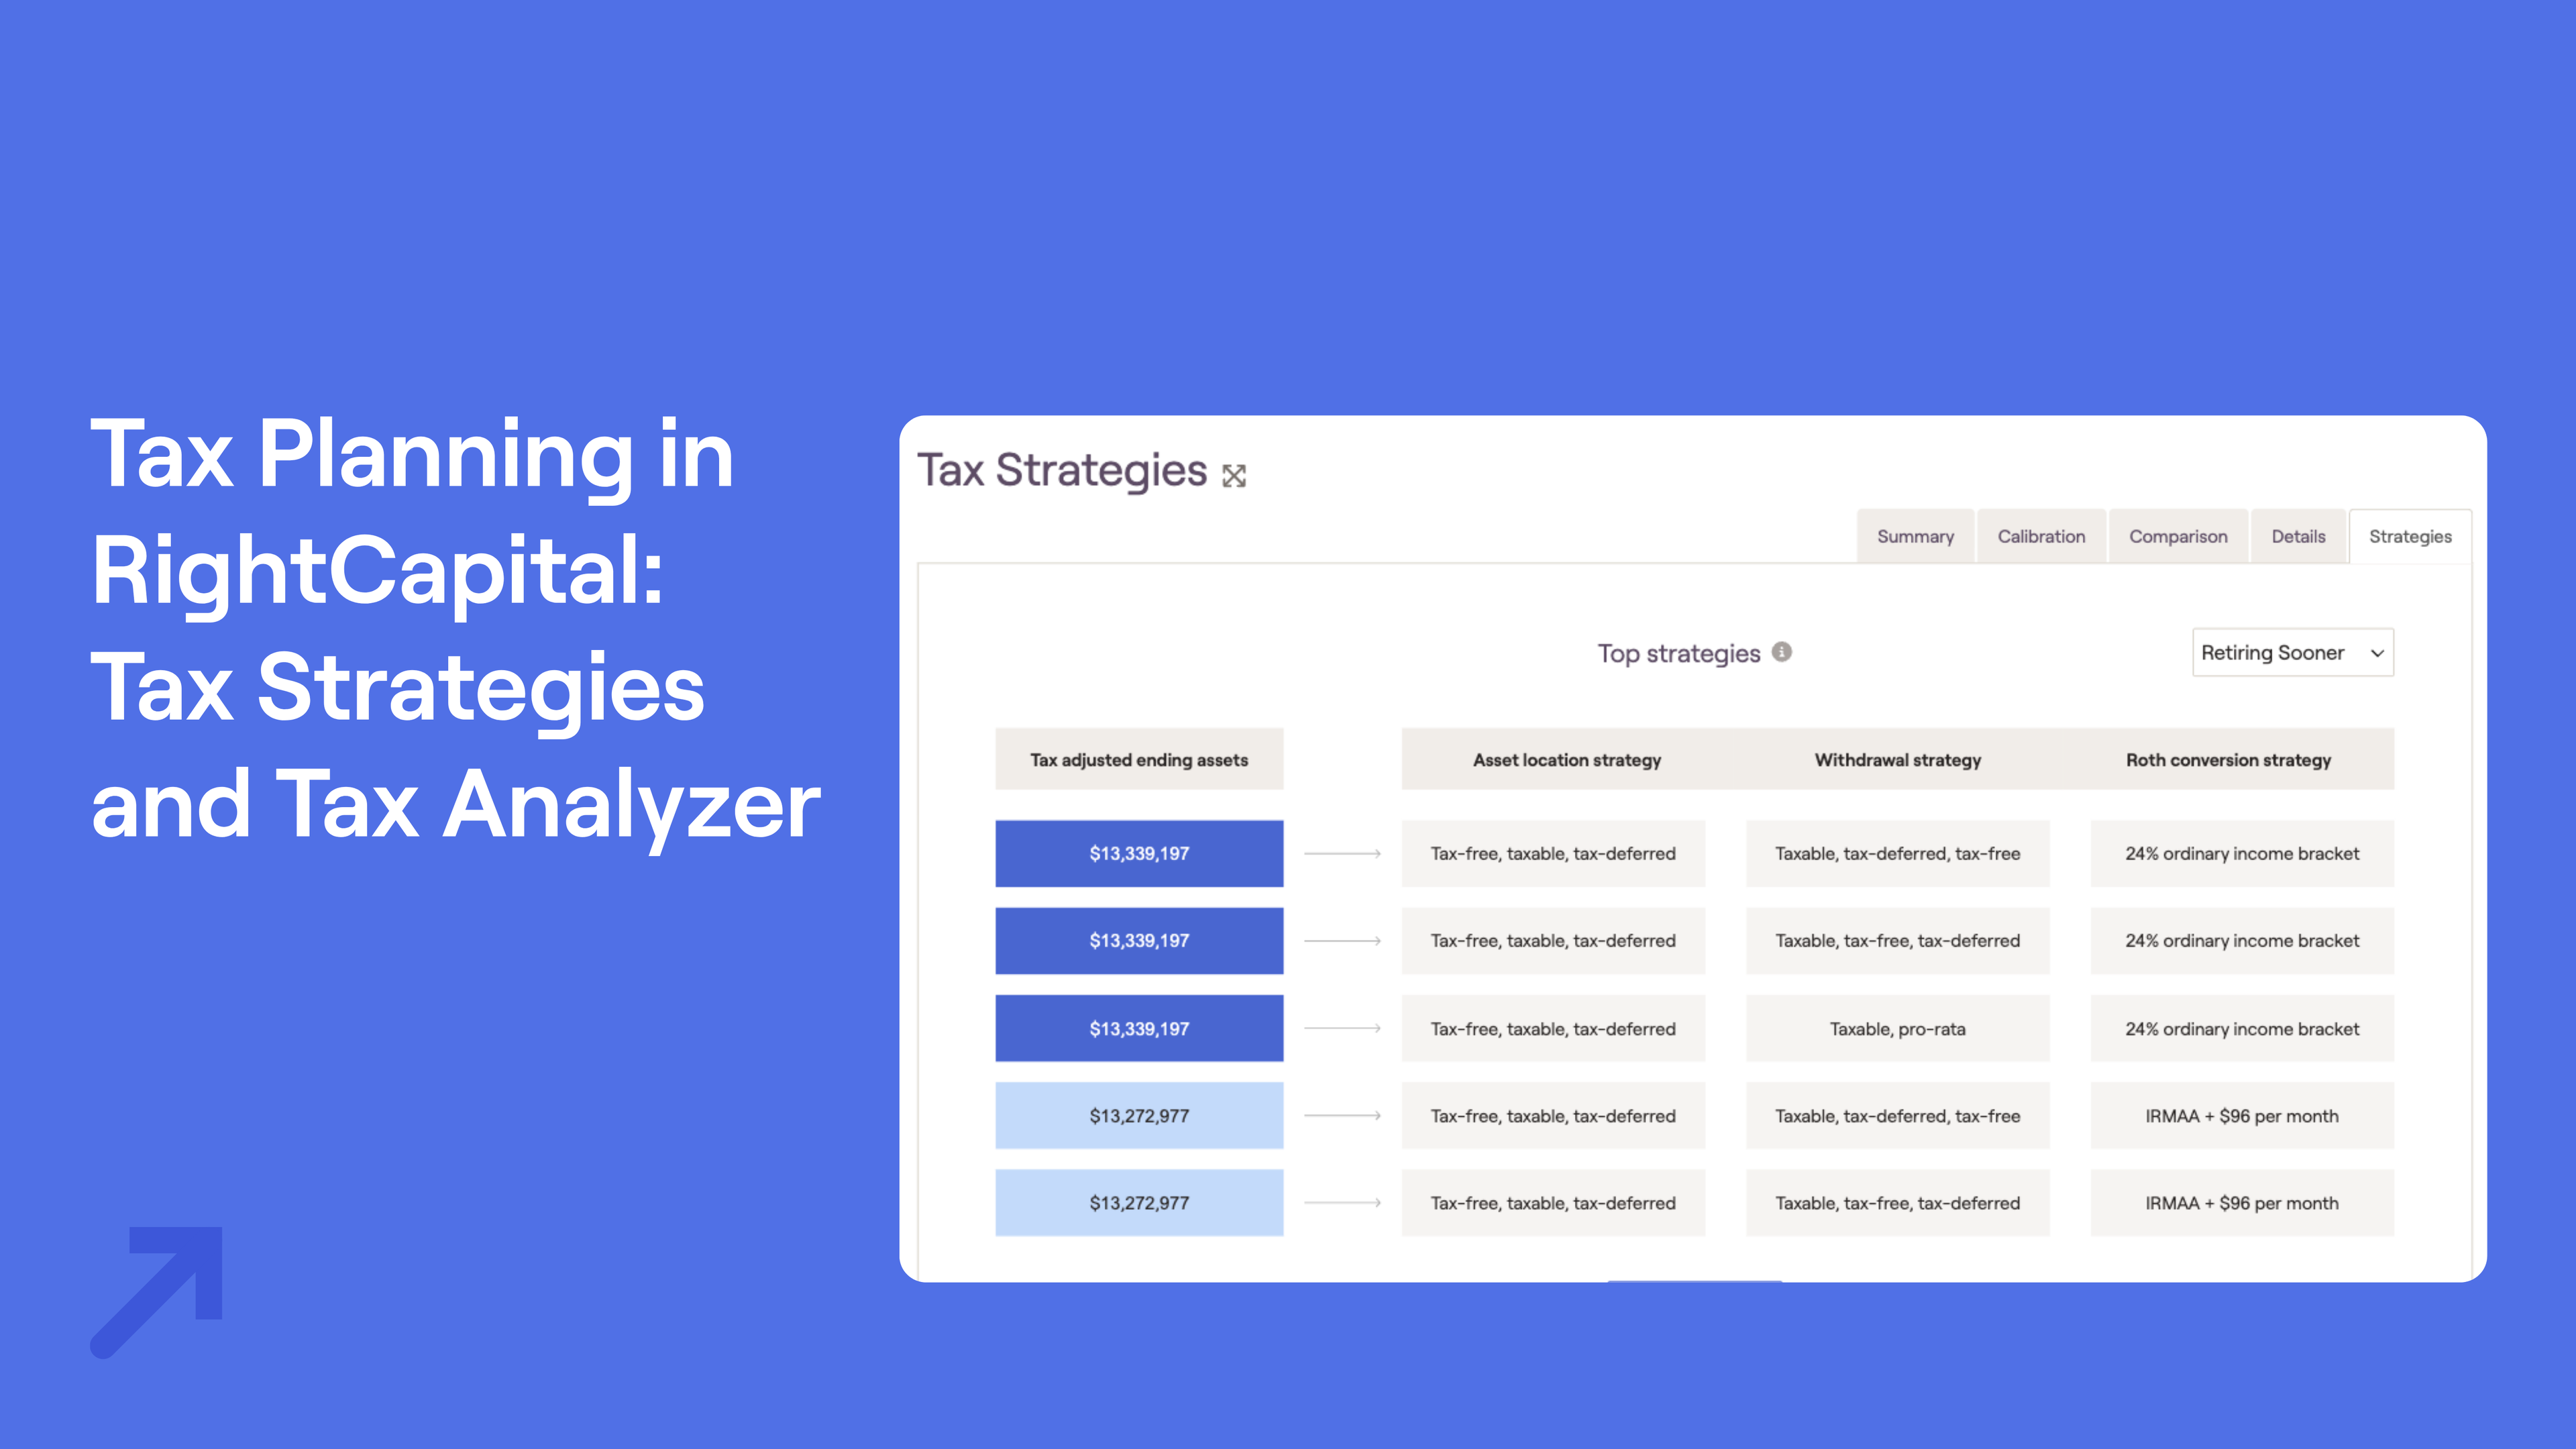
RightCapital's award-winning tax planning tools are built for the kind of work Levine described: looking back at what happened and projecting what comes next. For a closer look at how they work, read Tax Planning in RightCapital: Tax Strategies and Tax Analyzer.
Tax Strategies, available across RightCapital plans, models asset location, withdrawal sequencing, and Roth conversions across the life of the plan. Conversions can target ordinary income, capital gains, or Medicare premium brackets, known as Income-Related Monthly Adjustment Amount (IRMAA) thresholds.
Tax Analyzer, included with Premium and Platinum subscriptions, reads uploaded or projected tax returns so you can review a client's rates and thresholds and propose line-item changes, such as reducing IRA distributions to model a QCD.
Interested in more? Gain access to a full recording of Jeffrey Levine's RightInsights session, or schedule a personalized 1:1 demo to see RightCapital's tax planning tools in action.
Frequently asked questions
More and more clients want tax planning from their financial advisor. According to Kitces.com’s Jeffrey Levine, it also demonstrates value faster than portfolio management: advisors can show tax savings in the current year while also reducing a client's lifetime tax bill.
Taxable income mainly determines tax brackets and the qualified business income (QBI) deduction. Most other surtaxes, phaseouts, and Medicare premium thresholds are based on adjusted gross income (AGI) or modified adjusted gross income (MAGI), so strategies that lower AGI, such as qualified charitable distributions, can have a bigger impact than deductions taken later on the return.
Advisors who aren't CPAs, attorneys, or enrolled agents shouldn't represent clients before the IRS or write tax opinion letters. Outside of those areas, Kitces’ Jeffrey Levine says advisors generally have flexibility to provide tax planning and projections, as long as they follow firm policy, have the appropriate knowledge, and confirm their errors and omissions (E&O) coverage.
Jeffrey Levine recommends placing tax-efficient or low-return assets in taxable accounts, the highest-expected-return and tax-inefficient assets in Roth IRAs, and whatever remains in traditional IRAs.