How to Build a Debt Repayment Strategy for Financial Planning Clients
August 27, 2026
Key Takeaways
- The average U.S. consumer owes about $105,444 in total debt, of which roughly $21,603 sits outside a mortgage in credit cards, student loans, car notes and personal loans (Experian, 2025).
- Ordering debt repayment priority by highest interest rate costs the least in the end, though four separate research groups have found that starting with the smallest balance gets abandoned by clients less often. Which order suits a client depends on how that client behaves over a payoff that takes years.
- A debt strategy that never touches the retirement projection is only half an answer. An important point of clearing a balance early is what the freed-up payment does next.
- RightCapital's Debt module runs the whole workflow: build payoff scenarios, run comparisons side-by-side, and carry the winner into the retirement plan to see what it changes.
Why debt deserves its own conversation
Two things decide whether a debt strategy works. The first is the math, which your financial planning software will handle. The second is whether the client stays with the plan for the number of years it takes, which is a harder problem and the one most payoff advice skips.
The average American owed about $105,444 as of September 2025, going by Experian's consumer debt study, and the pile keeps growing. Household debt has grown by $4.6 trillion since 2019, with about 4.7% of it in delinquency. The categories climbing fastest are auto loans, credit cards, and home equity lines that have now risen seventeen quarters in a row (New York Fed, 2026 Q2). For a single client, that can mean about $1,256 a month of cash flow is going toward paying it off. (Experian Consumer Credit Review).
That monthly cost is where financial planning runs into debt. Money leaving to pay off interest never reaches a 401(k), a 529, or a savings account, so debt and retirement are drawing down on one pool of cash. Among people who wish they had saved more for retirement, 46% point to non-housing debt as the reason, and that rises to 56% among millennials (Allianz Life, 2024). Four in ten worry their debt will hurt their future quality of life, though only 14% of those working with a financial professional have raised it with their advisor.
Handling debt and retirement in separate conversations hides the tradeoff from the client. It also means you never find out whether an aggressive payoff schedule quietly wrecks the plan it was supposed to help, which happens more often than advisors expect.
Debt repayment achieves a few jobs at once. The first is getting balances down without leaving somebody short every month. Another starts when a balance clears and that payment becomes available for another goal, which is the part that belongs in a financial plan. A third is alleviating the mental burden for clients, as debt is a source of stress for many who carry it, a concept that feels simple but can be powerful.
Framed that way, a client meeting sounds different. Instead of lecturing about taking on that debt, you are showing someone what $500 a month can turn into once it stops going to a lender. For this example, $24,000 over four years, can be pointed somewhere useful, such as saving for a sports car or a family vacation.
Avalanche vs. snowball approach: what the research says
Two of the most popular approaches for debt repayment are called avalanche and snowball. Each involves the client covering the minimum on every debt, then setting aside a fixed amount on top of that. Where the extra money goes is what separates the approaches. Avalanche sends it to whichever debt carries the highest rate, and once that balance hits zero that surplus amount moves to the next highest interest rate. Snowball ignores rates and goes after the smallest balance on the list, working upward from there until nothing is left.
Ordering by highest interest rate costs the least in interest. Ordering by smallest to highest balance gets finished more often, and the evidence for that second claim is stronger than most advisors expect. Four research groups have separately landed on some version of that second finding.
Debt avalanche | Debt snowball | |
|---|---|---|
Order | Highest interest rate first | Smallest balance first |
Optimizes for | Total interest cost | Motivation and completion rate |
Best fit | Clients comfortable with a slow grind for long-term benefit | Clients who feel buried and need visible wins faster |
Tradeoff | Progress feels slow when the high-rate debt is also large | Often costs more in interest over the life of the plan |
Behavioral researchers have poked at this since 2012, in lab experiments and in field data from thousands of real borrowers, and the same result keeps turning up. People who clear whole accounts stay with a payoff plan longer than people who spread their extra money around. Closing an account gives someone progress they can point to. The researchers are careful about where it stops working: once the rates are far enough apart, the interest swamps whatever motivation was gained.
So the spread decides it. A few points apart and behavior wins. A 24% credit card next to a 4% car loan and the math wins. A workable compromise is to clear a couple of small balances for momentum, then re-sort by rate.
Whichever way it goes, what you are offering to clients is a future with less debt. A payoff date suddenly 47 months earlier than the original date holds attention in a way that general advice does not.
Four ways to manage a debt
Every payoff plan is built from four moves.
- Leave it alone: Often right for a 3% mortgage while the cash works harder somewhere else.
- Pay more on one debt: Nothing else in the plan changes.
- Utilize a payment strategy roll: Each cleared payment moves to the next debt down, which is what makes the back half of a plan run so much faster than the front.
- Refinance: Watch the payoff date, because a lower monthly payment usually means a longer loan and more interest.
A fifth mechanic often gets missed. There is a difference between raising the amount a client puts toward debt each month and sending a separate payment straight to principal. Raise the monthly budget and the extra dollars get split between principal and interest like everything else. Send the same money as a dedicated principal payment instead and all of it lands on the balance. Modeling the second type of payment as the first will understate what your clients are pulling off.
Clean data comes before strategy
One caveat before any of this works. Strategy sits on top of whatever you entered, so a debt missing its parameters gives you less to work with than you might think. All data is valuable, including original amount, current balance, interest rate, and loan term. It’s worth cross-checking anything that arrived through account linking, since aggregation tends to bring over just the current balance.
Present a debt strategy so clients act on it
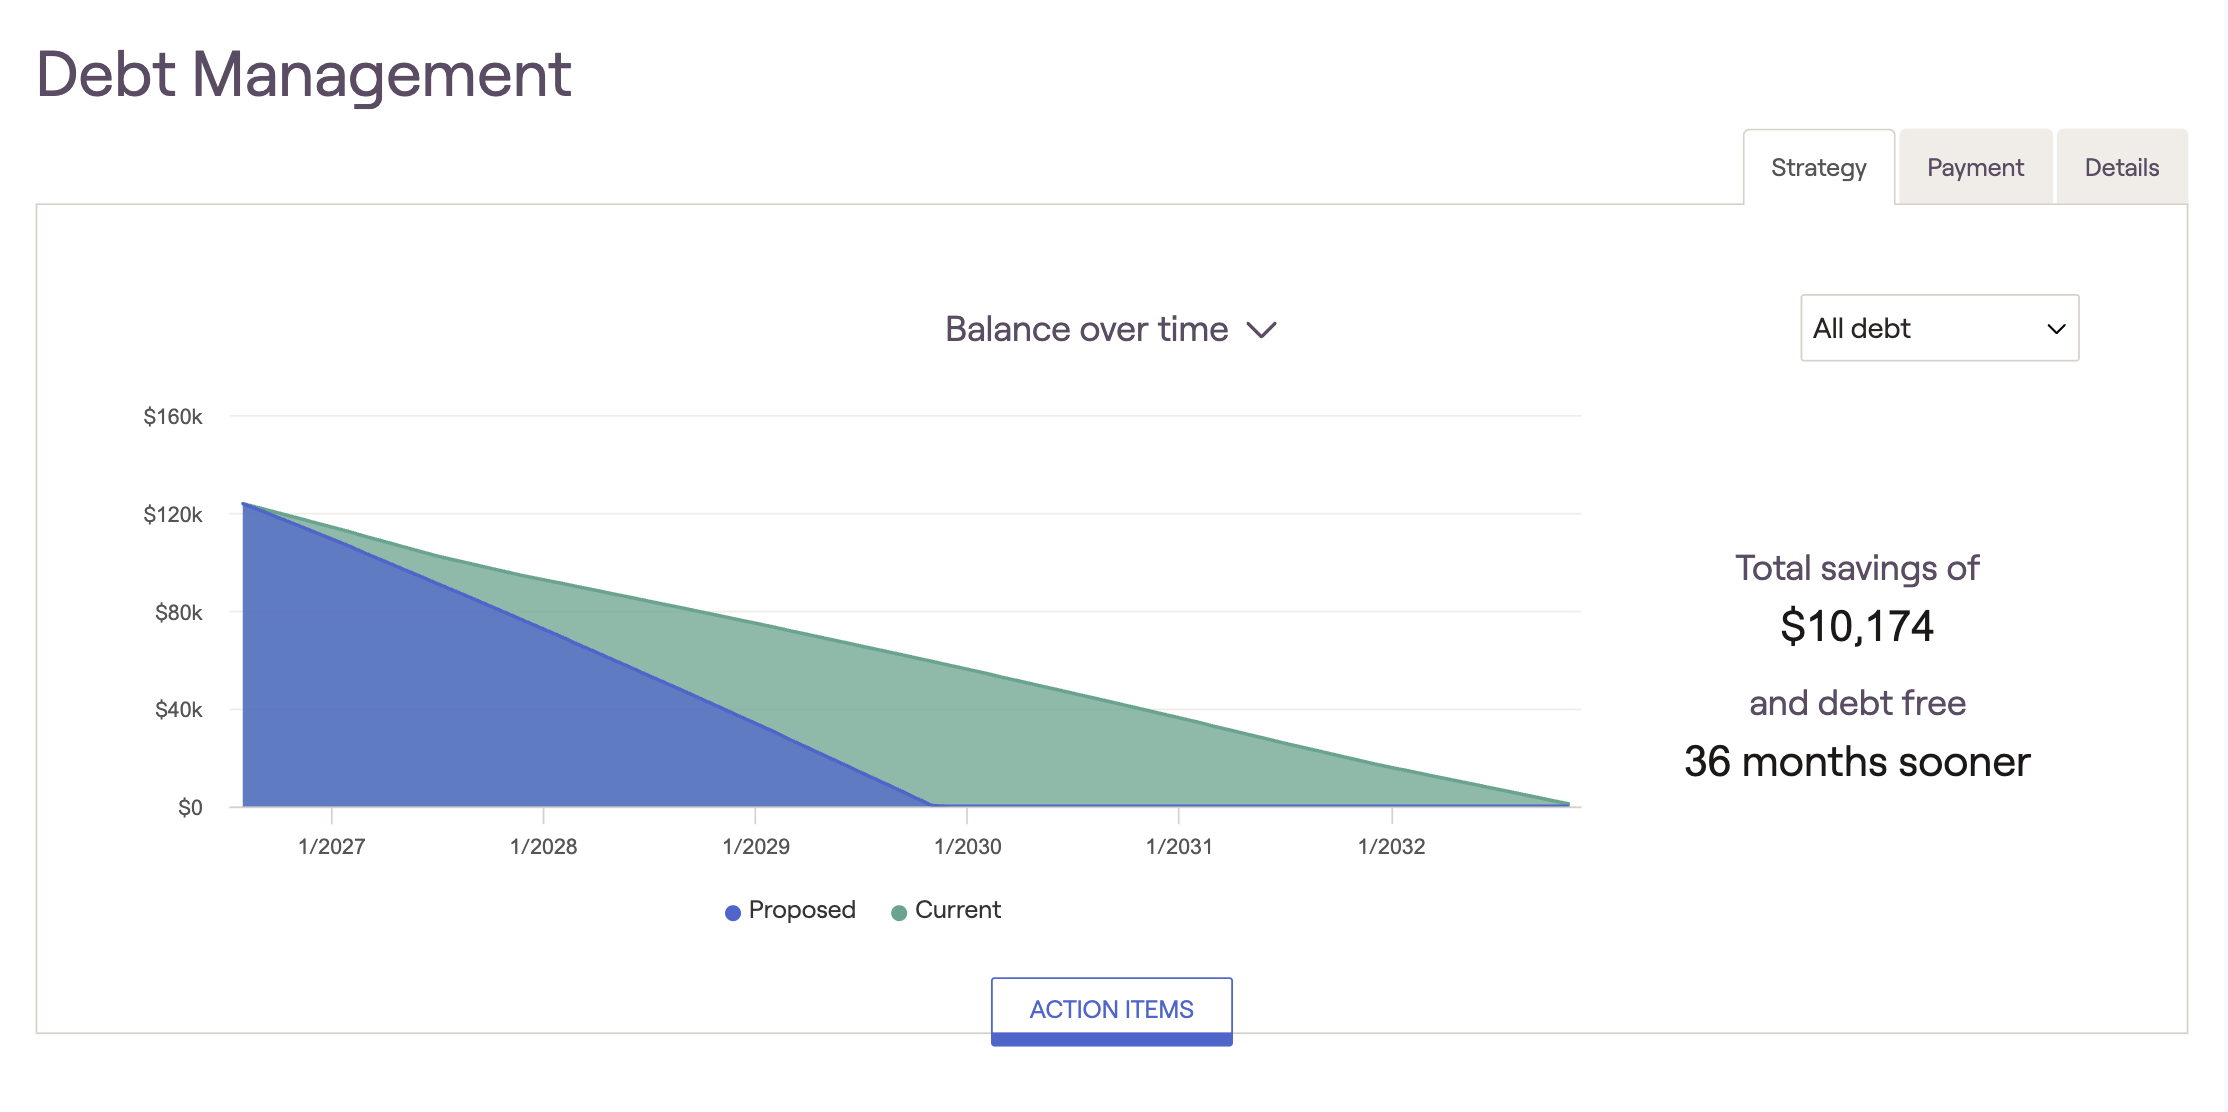
The numbers land harder when a client can see them. Charts do the convincing, and the detailed schedules underneath them are what make the recommendation credible once someone starts asking questions.
- Open with the result: "This saves you $12,000 and you're done 47 months sooner." Everything after that is support.
- Break the payment into principal and interest: A 24% rate is abstract until somebody sees how much of their payment is rent on the balance rather than progress against it. Put the current strategy beside the proposed one and the case for attacking that credit card first makes itself.
- Chart the current plan against your proposal: Show balances and payments over time, total saved, and a payoff date that moves up by a couple of years. That view does most of the persuading.
- Check it against cash flow: Push the strategy into the projection and compare cash flows year by year, since that is where an aggressive paydown shows up first if it leaves the client short. Probability of success is worth a look too, though it sits at a higher altitude and moves for lots of reasons. The cash flow comparison gives you a more granular perspective on how the debt strategy is working in relation to the client’s full financial plan.
- Then hand over the schedule: Once somebody has agreed to the direction, give them the month-by-month or year-by-year plan, either for one account or across all of it.
Debt planning within RightCapital
Here’s how debt planning works in RightCapital, following this summer’s Debt module update.
Assigning a strategy to each debt
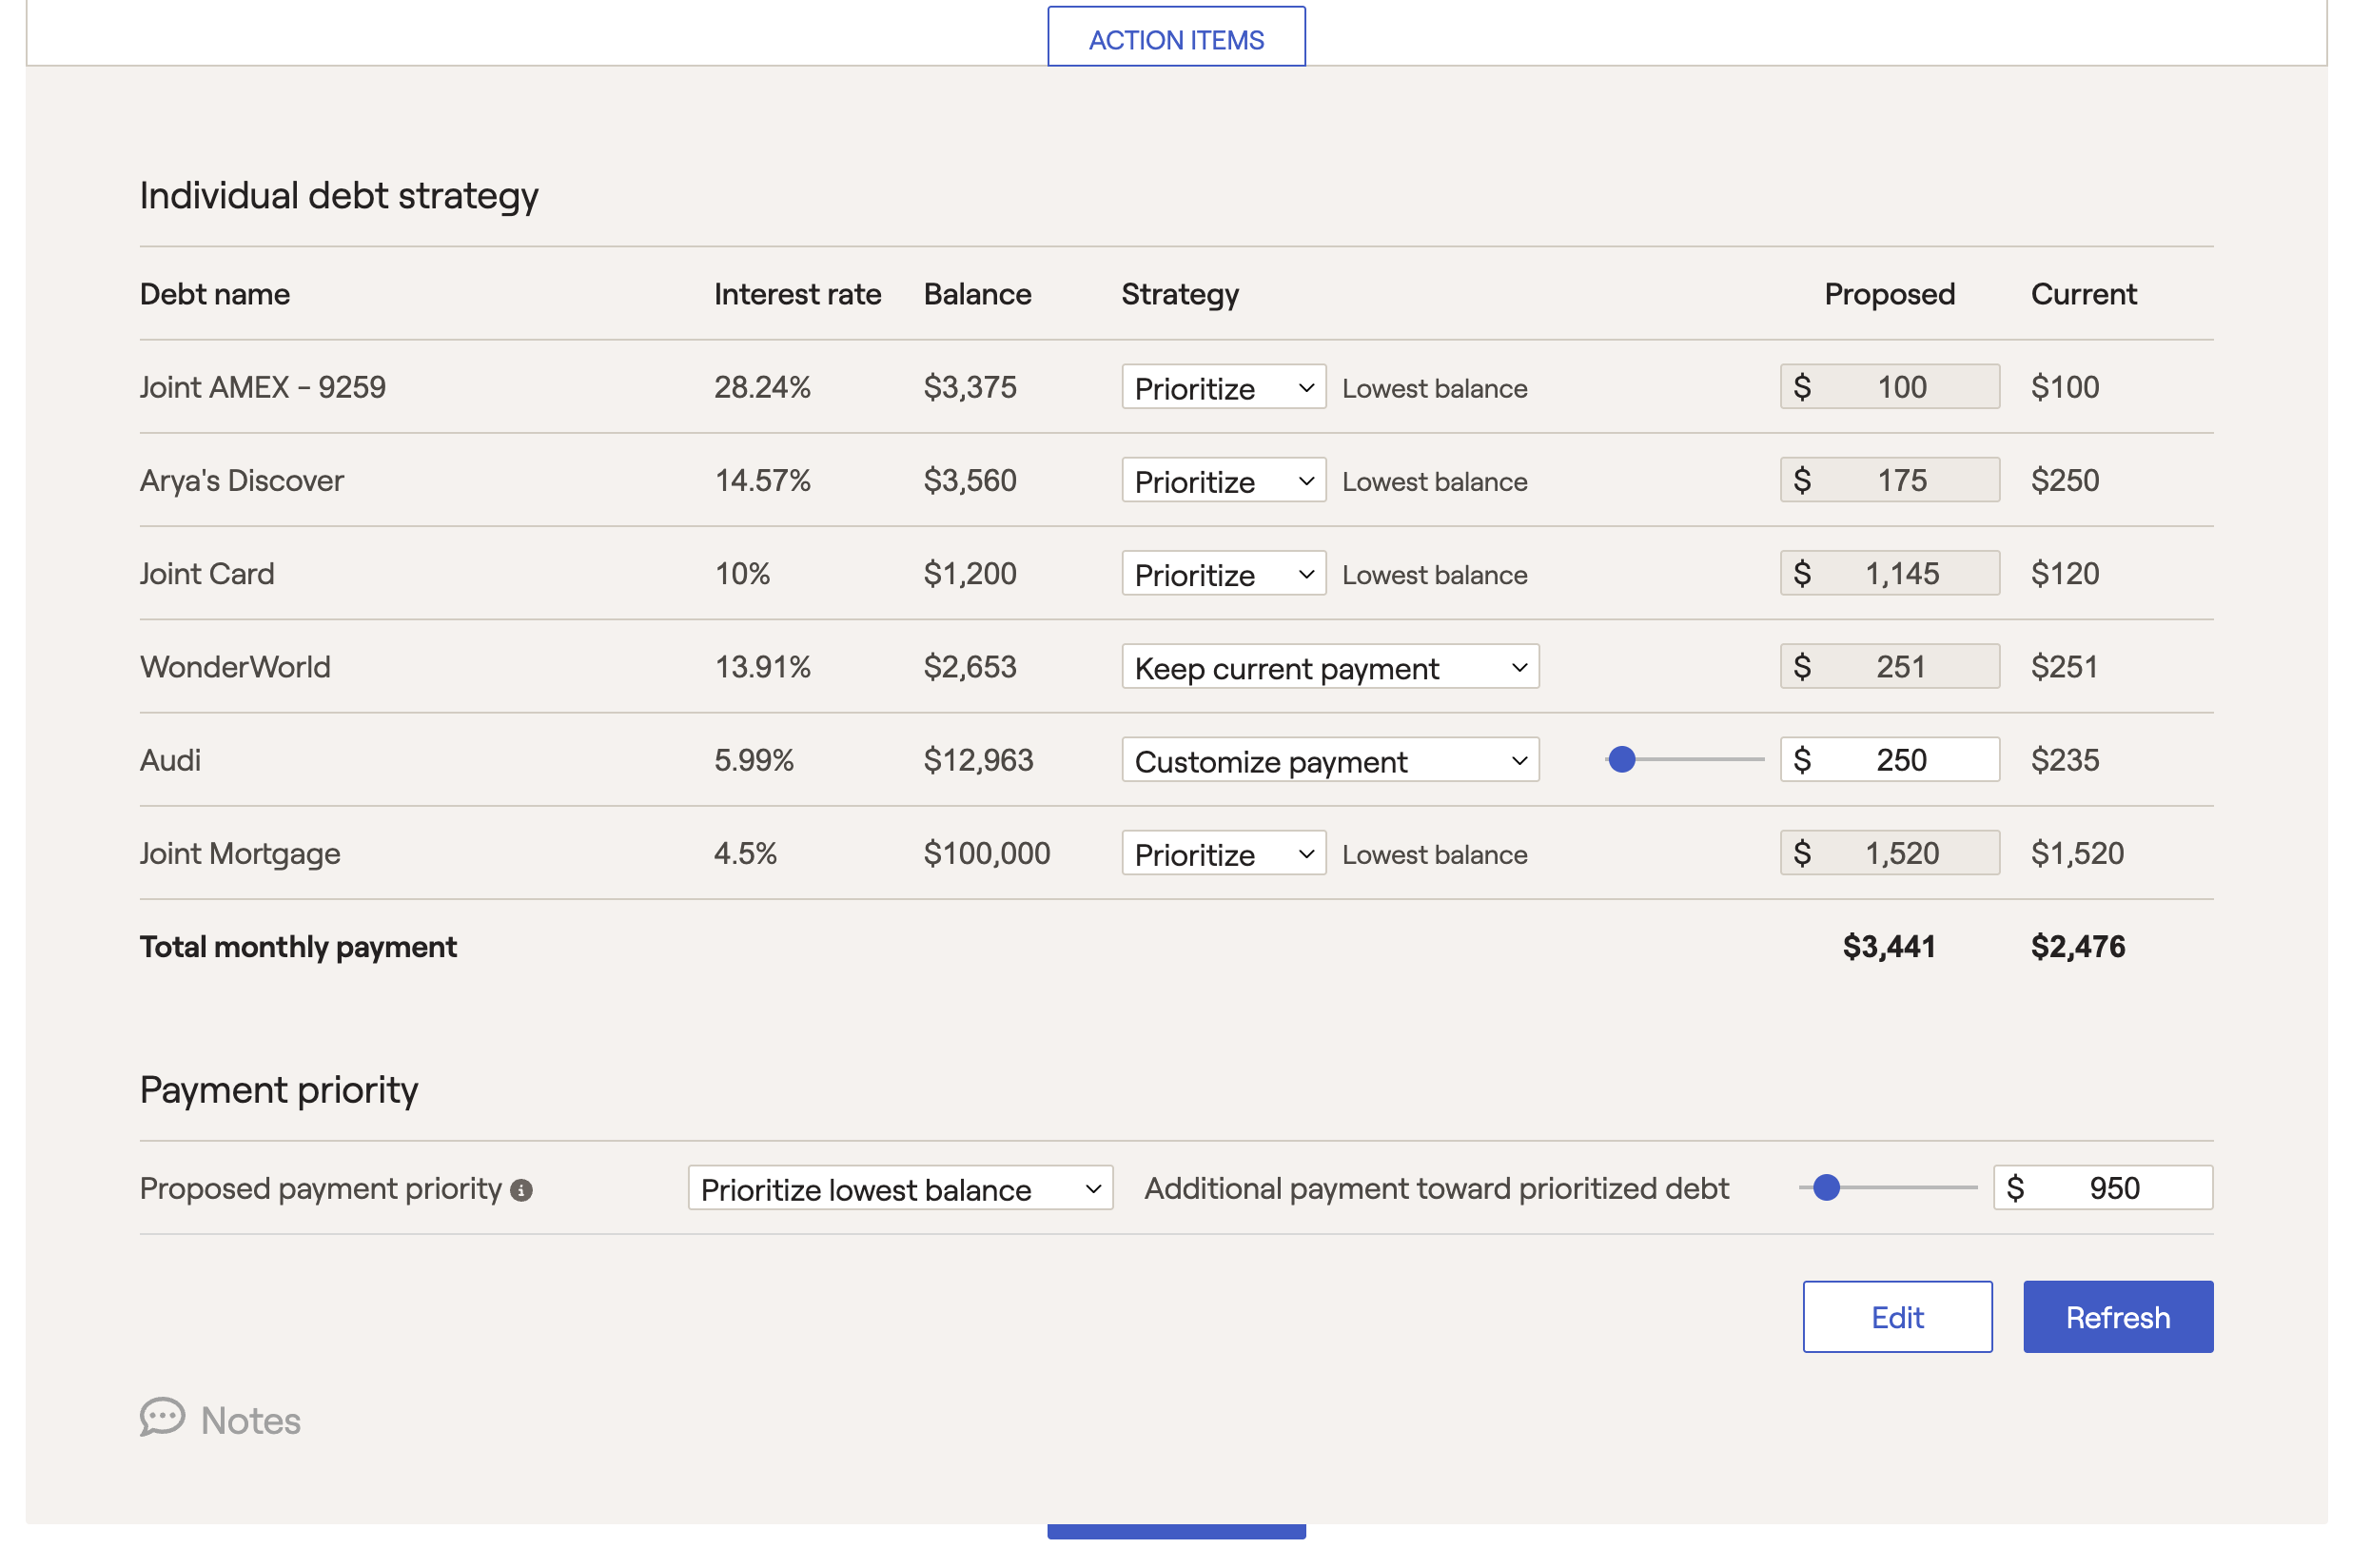
A couple of things are worth knowing before you start. Setting a customized payment on a debt pulls it out of any prioritized sequence, so an avalanche or snowball order will skip past it.
Selecting prioritize opens a payment priority table where you pick the highest rate or lowest balance, and there is a slider for adding an amount on top of the sequence. That slider is the fastest way to answer "what if they found another $200 a month." Refinancing opens a drawer for rate, length, closing costs, and a balloon payment if the client plans to clear it early.
Modeling an extra debt payment
You can model a principal payment directly in the Debt module, as either a short-term recurring payment or a one-time lump sum. It stays separate from the scheduled payments, so the full amount hits principal the way it would in real life.
It’s worth noting that you can manually exclude certain debts from the Debt module strategy and visuals, such as more complicated student loans or loans with unique schedules.
Putting certain student loans in a separate module
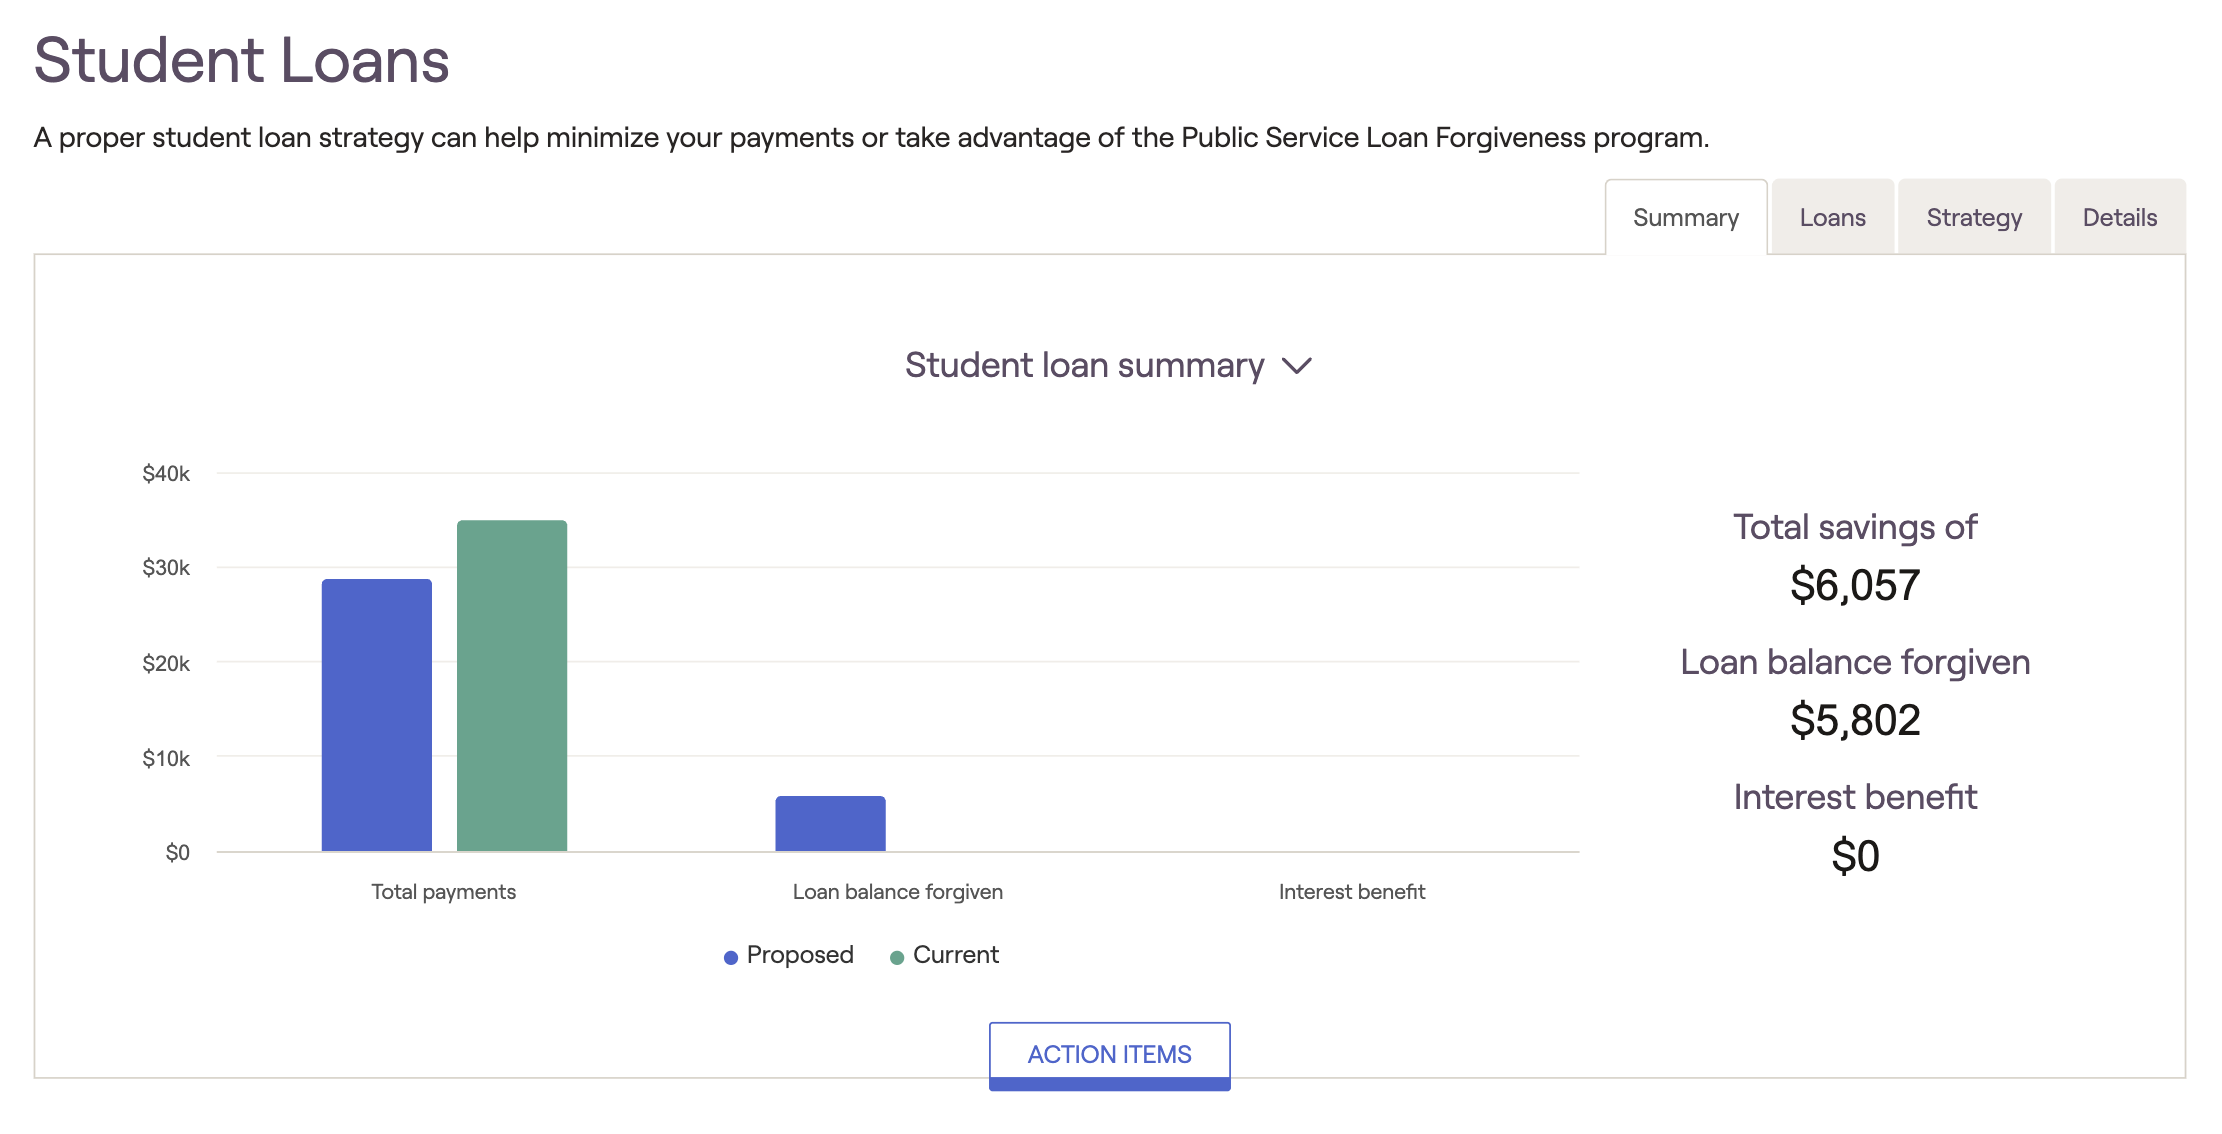
Visualizing current vs. proposed plans
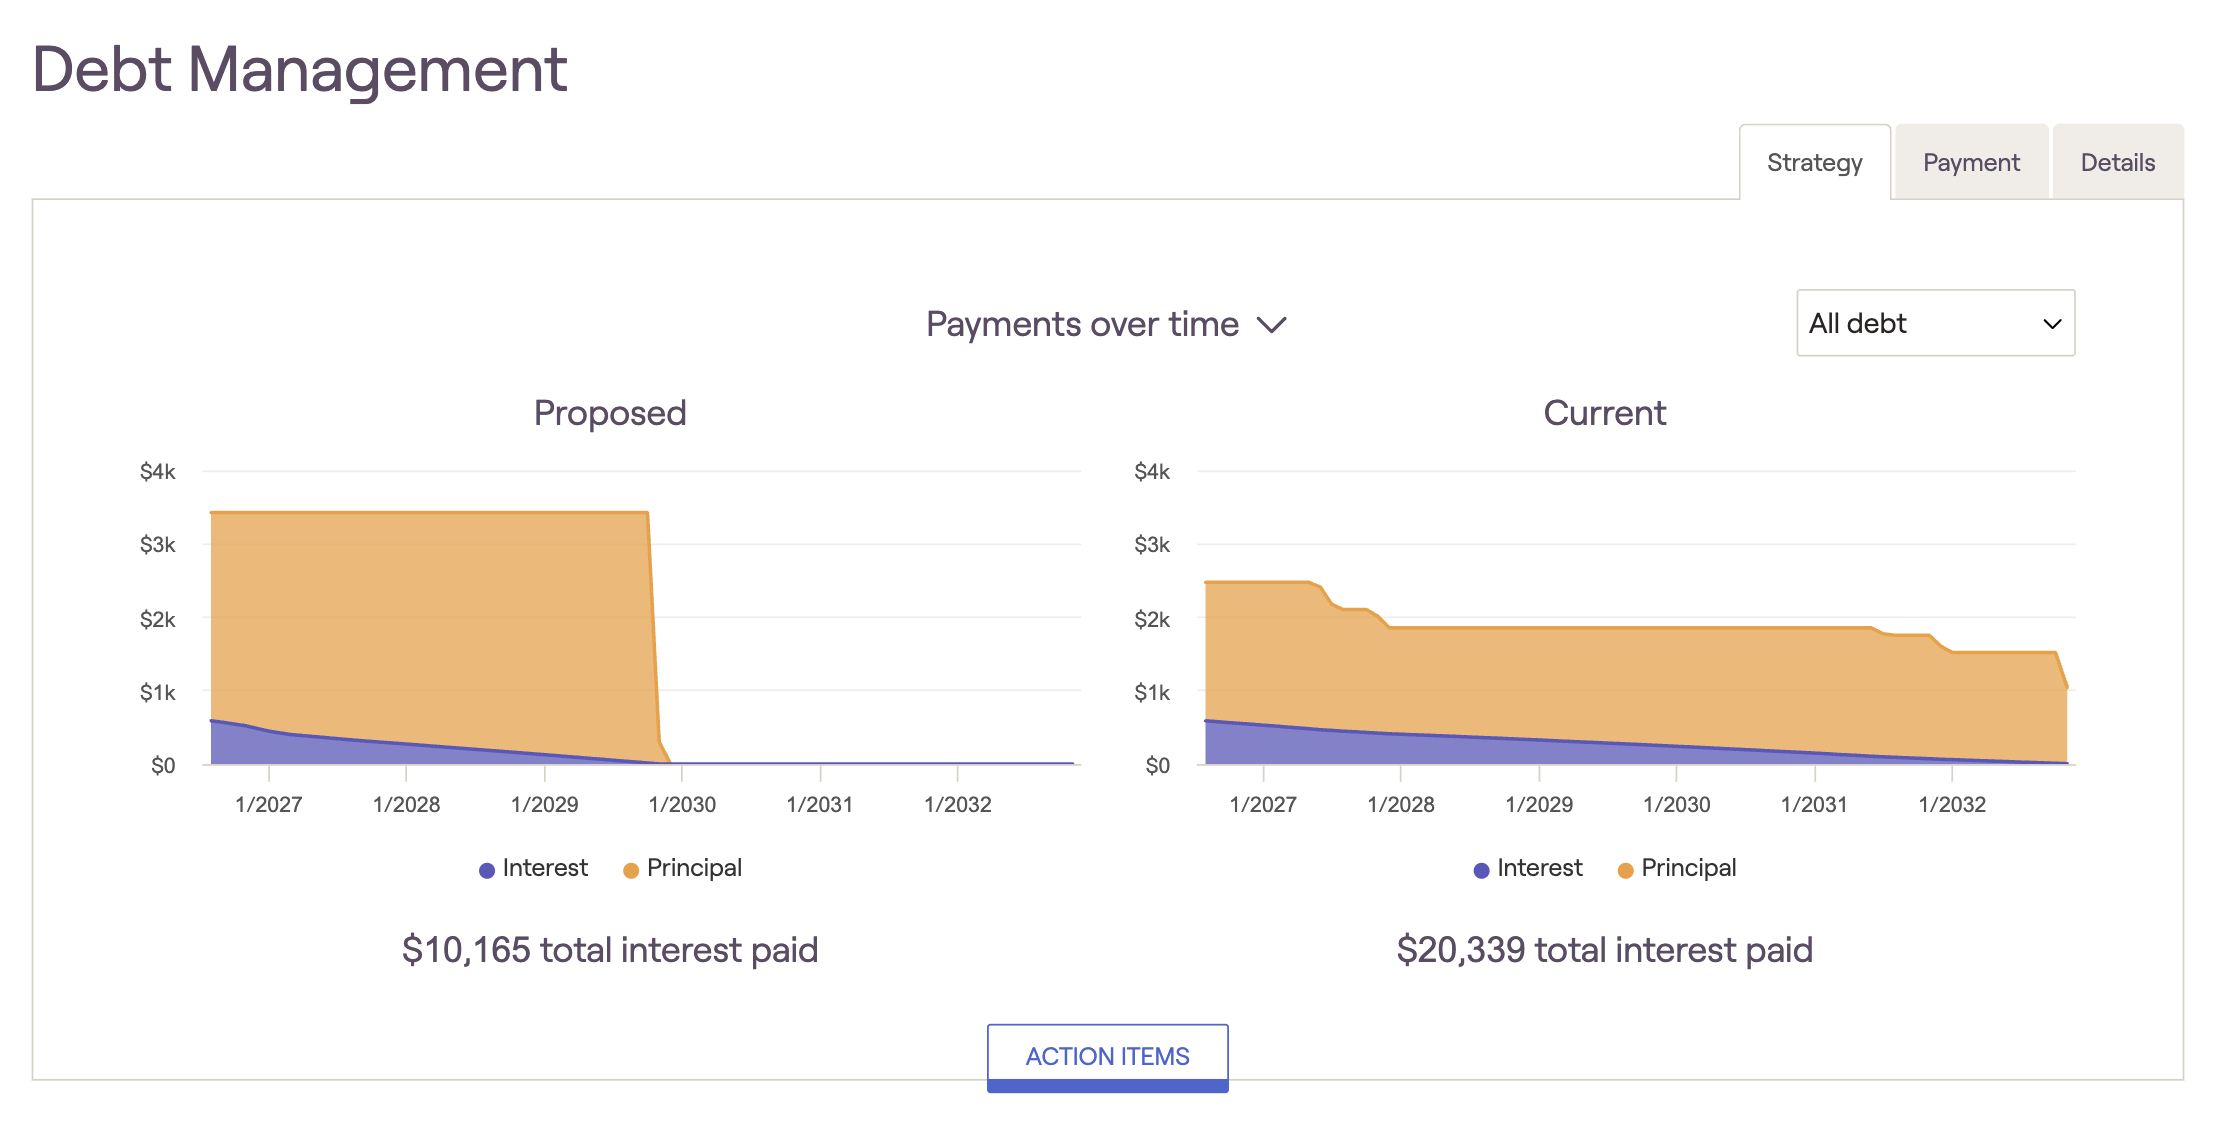
When somebody starts asking for specifics, the Details tab has the full amortization schedule behind all of it. Beginning and ending balances, interest, and payments, on a monthly or annual basis, for a single loan or across every debt in the plan.
Connecting to the retirement plan
Turn on the debt proposal in the retirement analysis and the whole strategy carries into that proposed plan. Start with the cash flow comparison. That is where a payoff schedule shows its cost, year by year, and where you find out whether the client goes short in 2029 to be debt-free in 2031. From there you have invested assets, tax payments, net worth, and probability of success against the current plan, though probability of success moves for plenty of reasons that may have nothing to do with debt unless it’s the only difference between the two plans. This is the step that turns isolated debt management into full financial planning.
Debt management is about as concrete as planning gets. Balances are real, interest is countable, and the payoff date goes on a calendar. The weight a client carries alongside those numbers is the part that never shows up in a projection, and it is often the reason they came to you. Getting them to commit comes down to whether they can see the tradeoff clearly enough to believe it.
Want to see this with one of your own client plans? Schedule a demo and we'll build a payoff scenario together.
Frequently asked questions
Managing debt effectively can improve a client's cash flow, lower the total interest they pay over time, reduce financial stress, and free up money for other goals such as retirement, education, or building an emergency fund. Addressing debt is often a key step toward overall financial stability.
Avalanche often saves more in interest. The research favoring snowball is not about math. It is about whether people stick with a plan. Closing an account shows someone visible progress and that’s what keeps them going through a payoff that could take years. So the question is partly about what you perceive about your client’s own behavior. The spread between the rates matters too. A credit card with 24% vs. a 4% car loan hands it back to the math. Running both approaches and letting the client see the difference beats picking one on principle.
Refinancing often lowers the minimum payment, which stretches the loan across more years and raises total interest. Monthly cash flow improves while lifetime cost climbs. Whether that trade makes sense depends on what the client needs from their budget right now, which is a conversation better had over two scenarios on screen than in the abstract.
It depends. Model both in your financial planning software. Watching the probability of success move under each version settles arguments faster than a rate comparison does.