Tax Planning in RightCapital: Tax Strategies and Tax Analyzer
September 22, 2026
Key Takeaways
- Tax planning is one of the few planning deliverables a client sees pay off within a year. Most planning advice is a promise about decades from now; an opportunity found on this year's return shows up on next year's.
- RightCapital’s Tax Analyzer reads a single year's tax picture from an uploaded or projected return. Tax Strategies models asset location, withdrawal sequencing, and Roth conversions across the life of the plan.
- IRMAA is a cliff, not a ramp. Conversions can be modeled to stay under it entirely or filled up to a specific Medicare premium bracket when accepting one tier unlocks meaningfully more conversion room.
- RightCapital’s expanded tax-planning features were named the winner in the Financial Planning category at the 2026 Wealth Management Industry Awards.
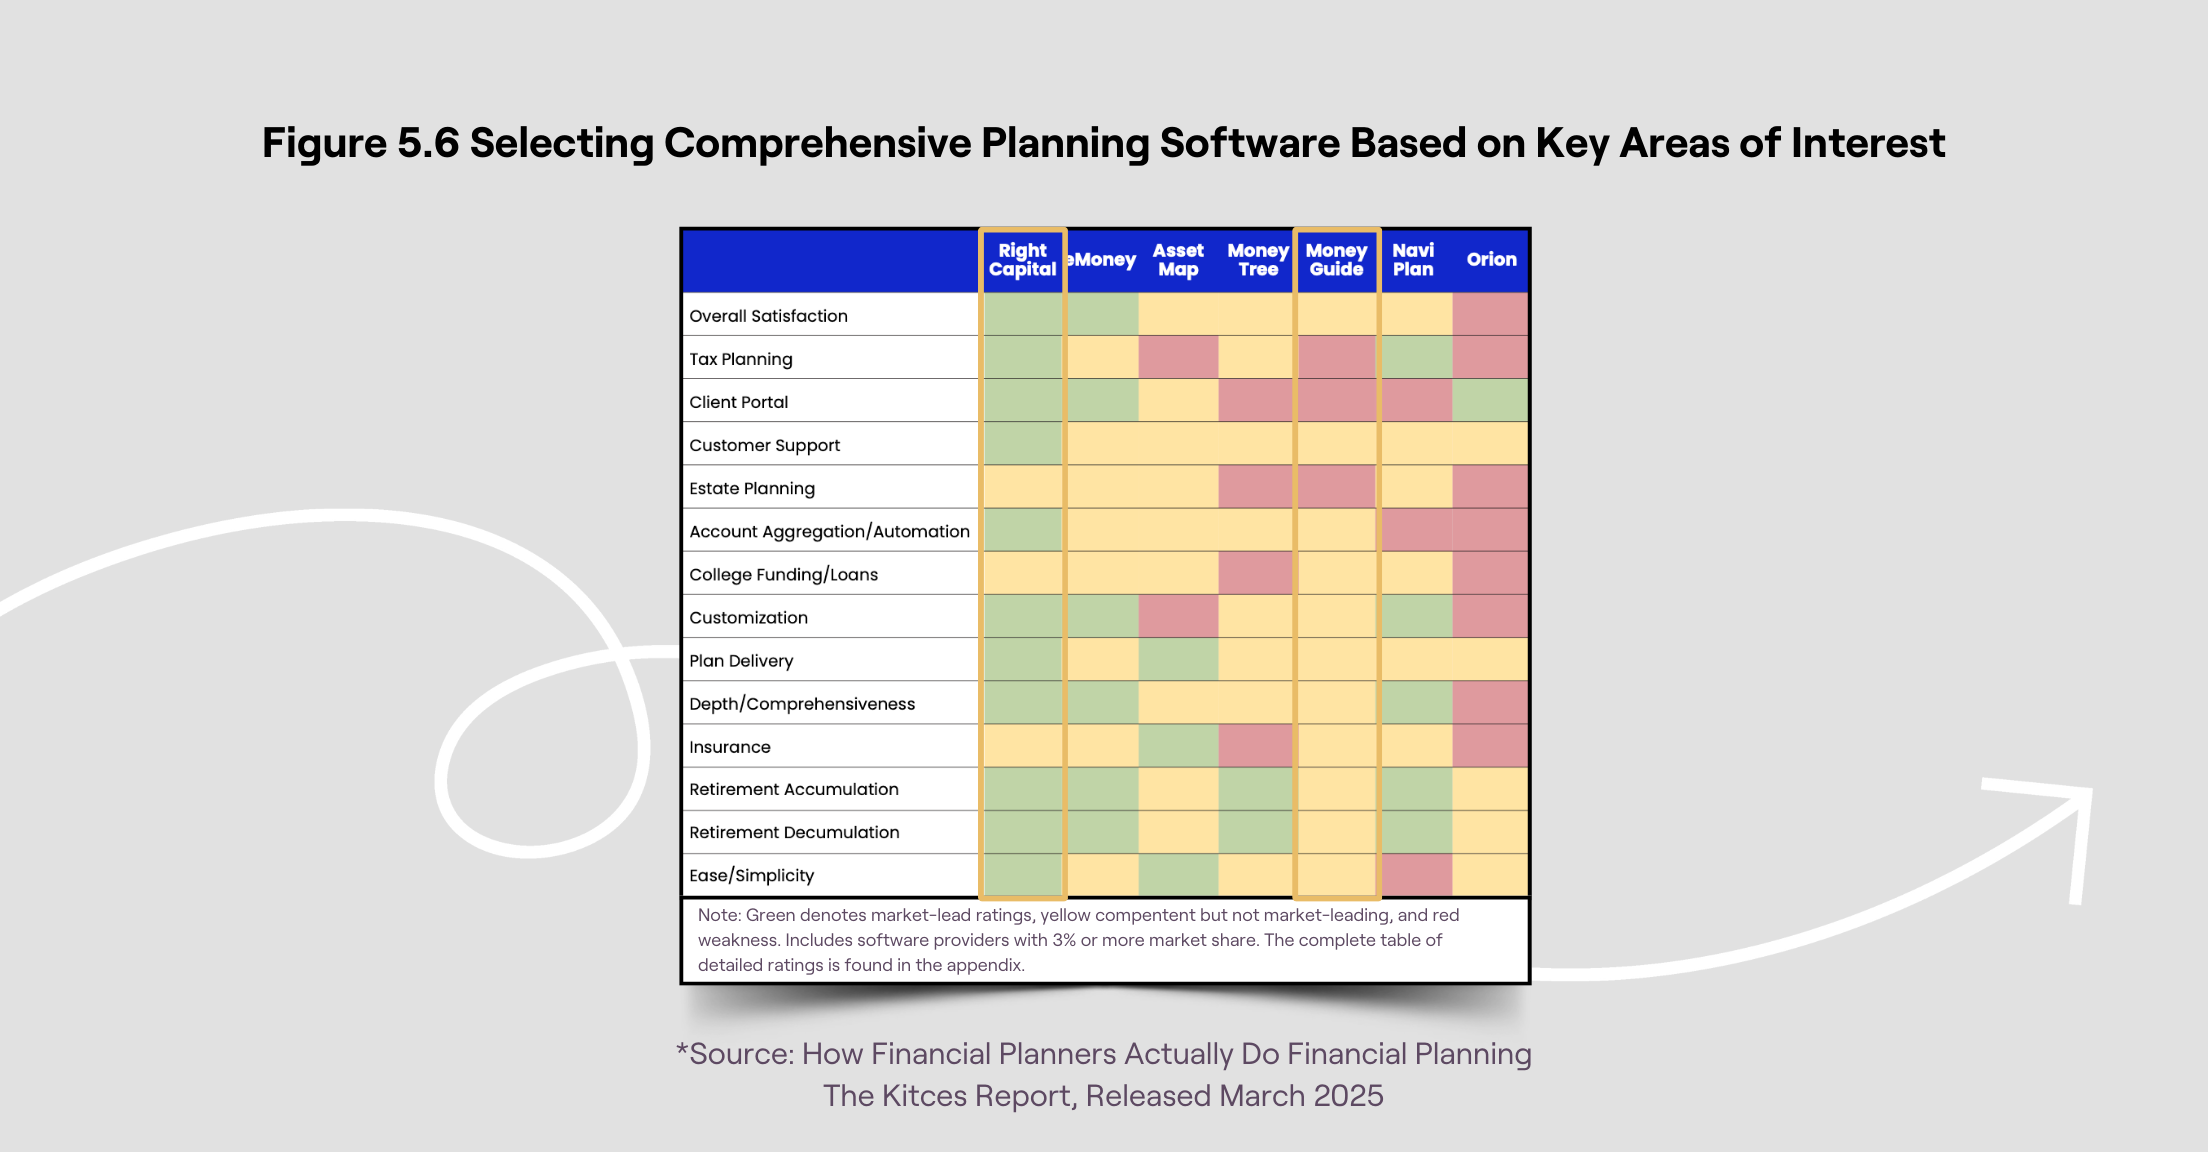
- Advisors also gave RightCapital the highest tax planning rating among the three most widely used comprehensive planning platforms in the March 2025 Kitces Report.
With tax-planning becoming more important in financial planning, two independent measures have recognized those features within RightCapital. Advisors gave RightCapital the highest tax planning rating among the three most widely used comprehensive planning platforms in the Kitces Report, “How Financial Planners Actually Do Financial Planning” (released in March 2025). In September 2026, RightCapital's expanded tax-planning features (specifically the Tax Strategies module and Tax Analyzer) were named the winner in the Financial Planning category at the Wealth Management Industry Awards.
Why tax planning became one of the advisor's most visible deliverables
More than 90% of advisors say they do tax planning, and Michael Kitces has said that figure has held steady for about eight years. What's changed isn't whether advisors do it—it's what "it" means.
The old version was tax planning attached to a product: here's the annuity, here's how it's taxed. The new version starts with the client's actual 1040. As Kitces put it at RightInsights in February 2025, "We've gone from, 'I do tax planning around what I'm implementing for you' to this realm of 'I'm going to pull out your tax return and see if I can find opportunities and ideas that might lay some additional value on you.'"
That's a harder service to deliver. It's also the one clients notice.
Tax planning is one of the few parts of financial planning where the client sees a result within a year. So much of what planners do is a promise about the future—you build the plan, the client follows it, and in a few decades everyone finds out whether it worked. Kitces described a potential client interaction: "We're going to give you all this great advice and 30 years from now you are so going to thank me for this."
With tax planning, you could find an opportunity on a return that the client will see on next year's return. Kitces gave another hypothetical client conversation: "I would just like to point out to you that I literally saved you $3,722 in actual taxes last year by finding this opportunity on your tax return."
It also creates a natural annual touchpoint. A retirement projection doesn't need rebuilding every year, but a tax picture changes constantly—income shifts, brackets inflate, laws change, or a client sells a property.
Doing that well takes two different skills: reading what's in front of you, and modeling what to do about it.
Tax planning tools in RightCapital
RightCapital's tax planning tools help advisors with both of these challenges. Tax Analyzer tells you more about a client’s tax situation in a specific year. Tax Strategies models what to do about it across the life of the plan. Together, these make up the expanded tax-planning Features that won the Financial Planning category at the 2026 Wealth Management Industry Awards, aka “The Wealthies.” Separately, in the Investment module, Tax Allocation breaks out accounts into the three tax buckets.
Tax Analyzer
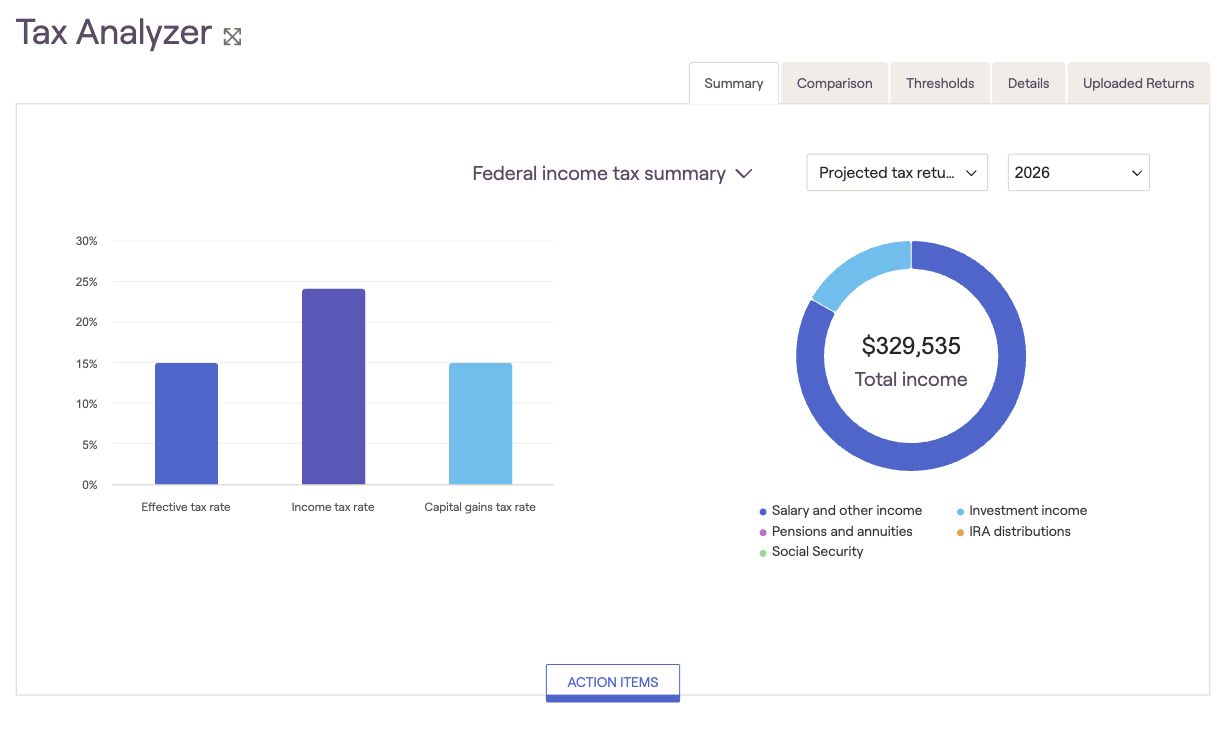
No upload? No problem. Tax Analyzer also builds a projected tax return for any year in the plan, drawn from the client’s actual profile data. The projections update as the plan changes so you can analyze years ahead, then propose line-item changes against it.
From there, evaluate the tax picture through key charts.
- Federal Income Tax Summary: Shows the income sources contributing to the client's taxable picture alongside the three rates that apply to it—capital gains, income tax, and effective tax rate
- Investment Income Efficiency: Backs into how the portfolio itself is driving the tax bill, separating taxable from tax-exempt interest, ordinary from qualified dividends, and short-term from long-term capital gains
- Ordinary Income Bracket: Lists the income range for each bracket next to how much of the client's income falls into each one, making conversations about marginal versus effective rates simpler
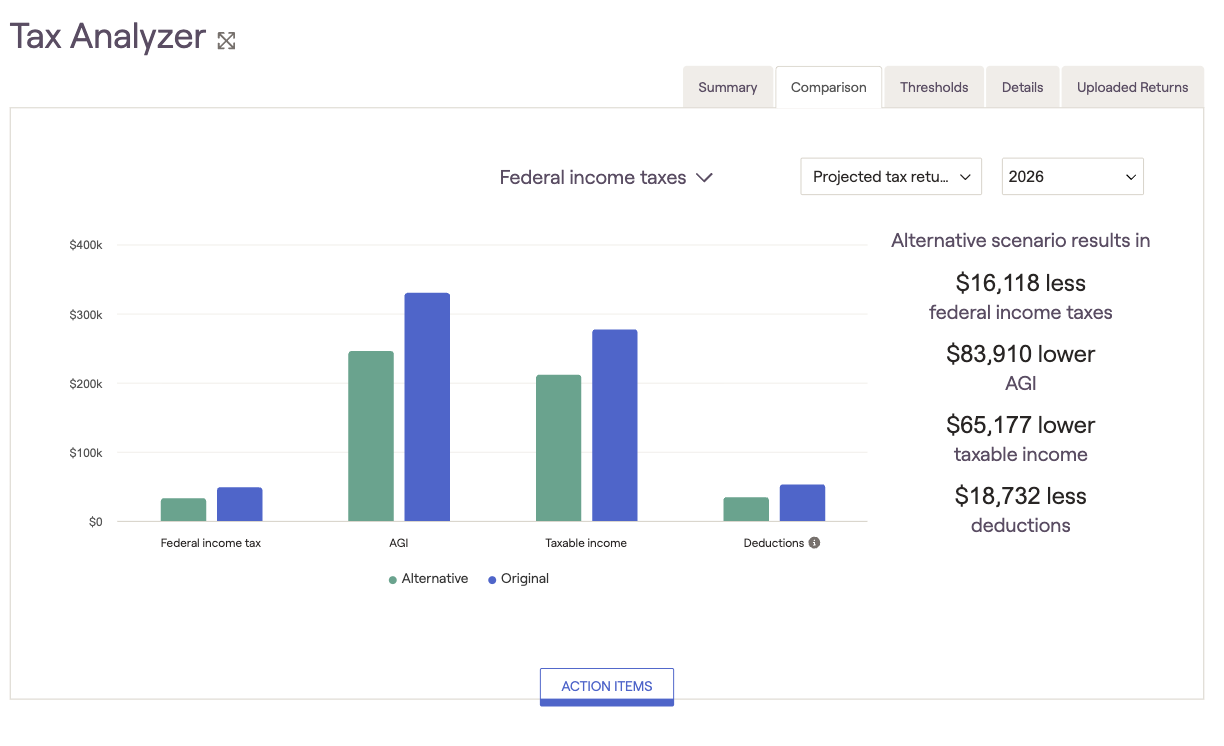
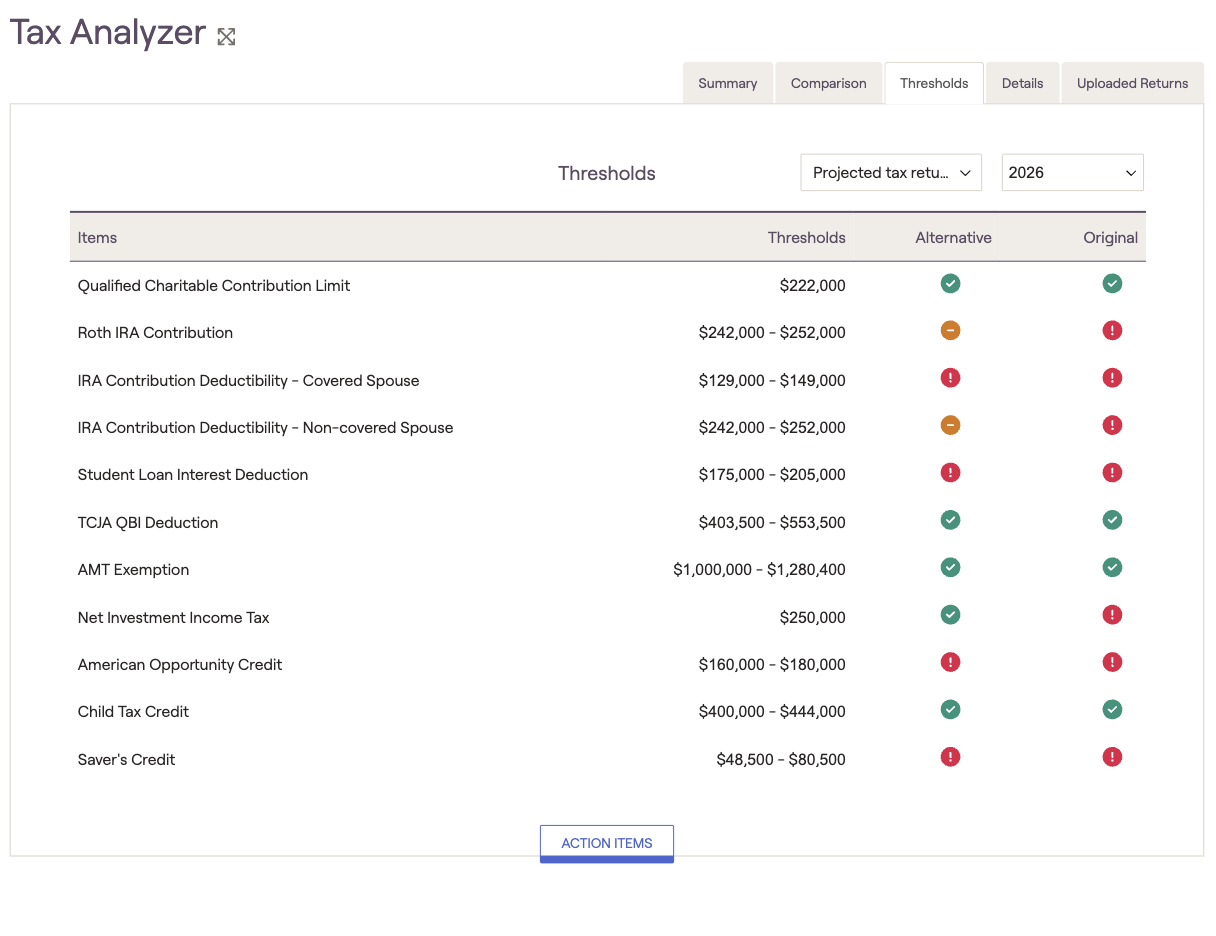
RightCapital’s Tax Analyzer is included with Premium and Platinum subscriptions.
Tax Strategies
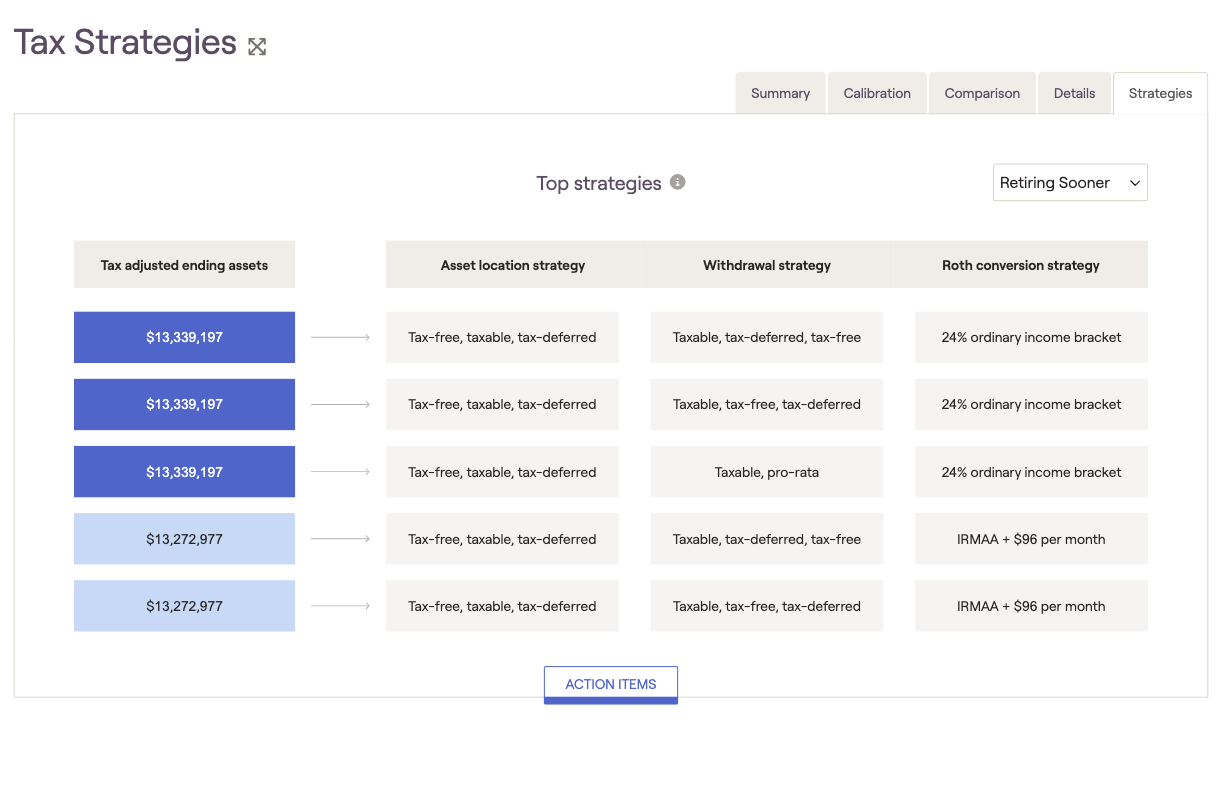
- Asset location: Shows how much fixed income versus equity each tax bucket holds based on the client’s investment asset allocation. Create a proposal controlling how the equity portion of a client's asset allocation spreads across taxable, tax-deferred, and tax-free accounts. The default is pro-rata, spreading equities proportionally across all three buckets. The alternatives fill each bucket completely before overflowing into the next.
- Asset withdrawal sequencing: Shows which tax bucket the client pulls from to fund negative net flows, and in what order. Model different tax-efficient withdrawal sequences and see how it impacts the plan. The default is taxable, then tax-deferred, then tax-free.
- Roth conversions or normal distributions: Focuses on how much to convert and in which years. Use the slider to fill up a specific tax bracket, and the platform converts or distributes as much as possible each year without having the client jump into a higher tax bracket. Tax bracket options include converting or distributing up to certain ordinary income brackets, capital gains brackets, and Medicare premium tax brackets for Income-Related Monthly Adjustment Amount (IRMAA) adjustments.
That last target is worth calling out. IRMAA is a cliff, not a ramp. Next year's IRMAA is based on the previous two years' income, and if you cross a threshold by a dollar, the full Medicare surcharge applies.
That makes it a real decision rather than a rule. For many clients, the right move is keeping conversions under the first threshold so IRMAA is never triggered, which you can model by filling up to the lowest Medicare premium bracket. A client with a large traditional IRA and a decade of required minimum distributions (RMDs) ahead is sometimes better off accepting one surcharge tier in exchange for converting substantially more at a lower rate. Instead of guessing, you can model each approach. An option within the Calibration tab charts Modified Adjusted Gross Income (MAGI) against the IRMAA thresholds so you can see exactly where conversions land.
Tax Allocation
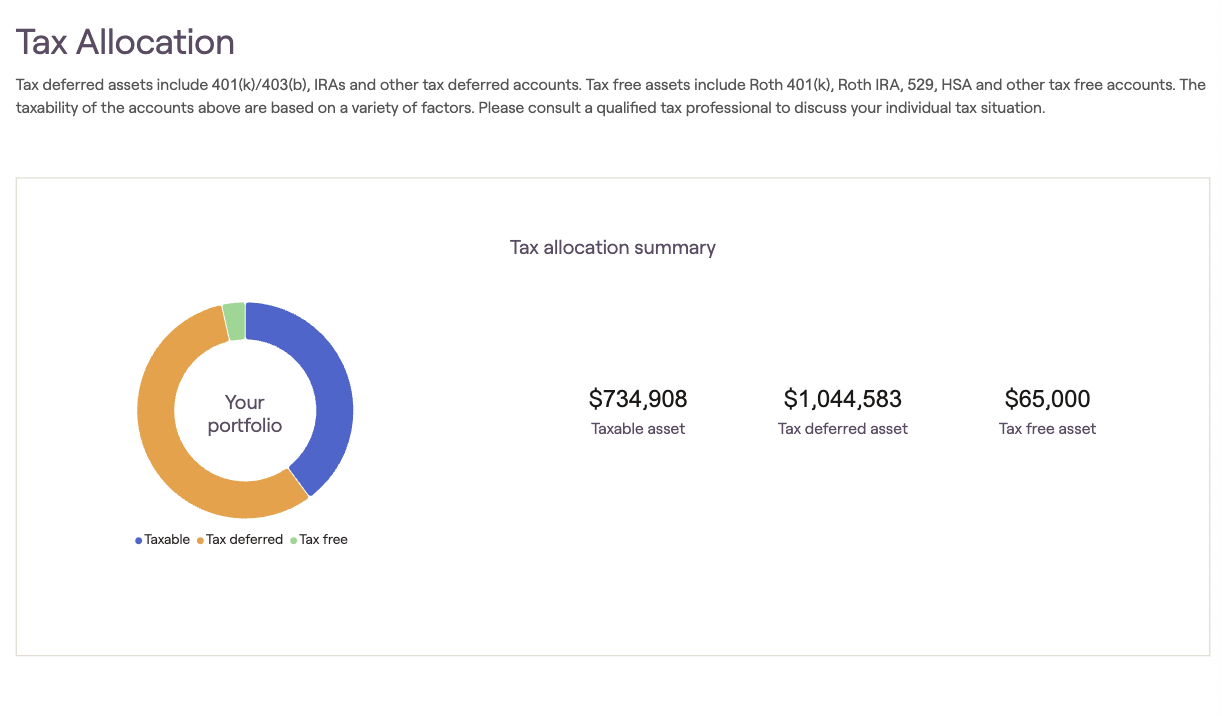
That diagnosis is also what makes the CPA conversation productive. "Having the power to come to the CPA with recommendations with the data to back it up is pretty exciting for me. And then you can actually quantify the tax savings at the end of the day."
Solving for top strategies instead of guessing
Tax strategies interact. A Roth conversion changes taxable income, which changes the optimal withdrawal sequence, which changes the balances asset location is allocating across, which changes future RMDs, which changes how much room the next conversion has.
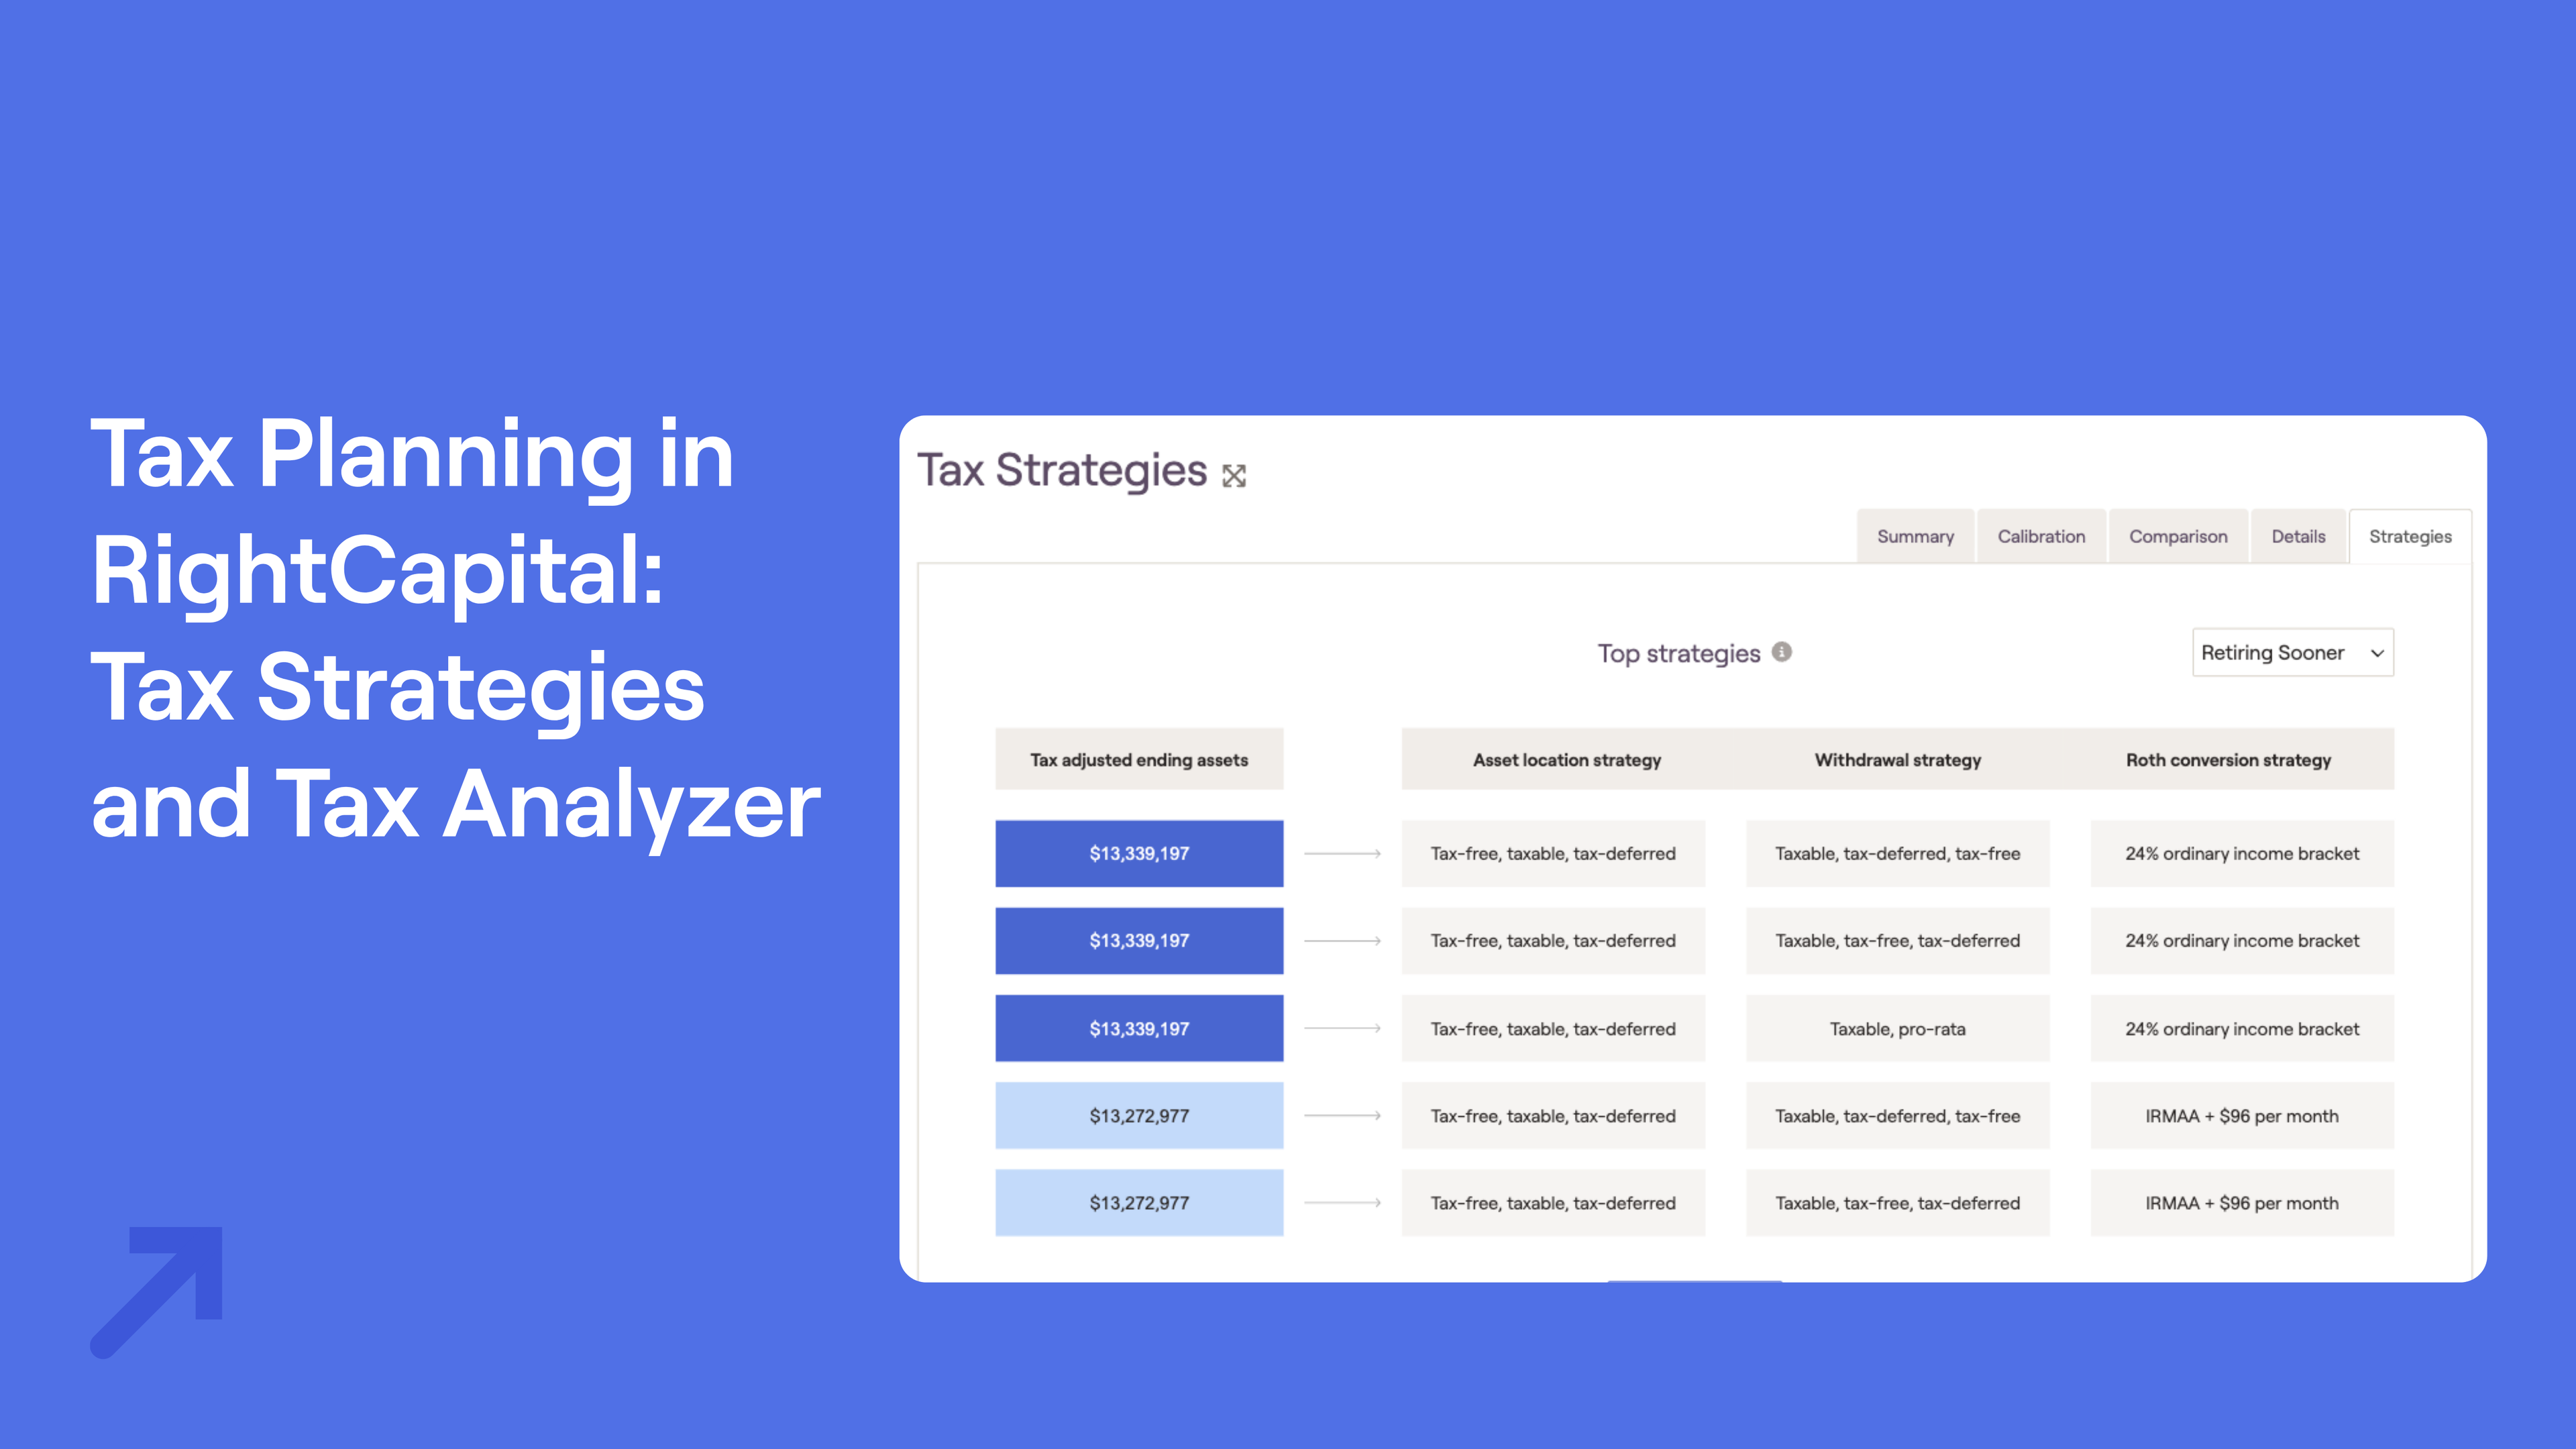
“Solve for Top Strategies” within the Tax Strategies tool mixes and matches every option within those three toggles and returns the five combinations with the highest tax-adjusted ending wealth. The result is a color-coded table showing the ending asset values and the selections behind each. You also have the option to pick and choose which strategies to explore, or to isolate one lever, such as to show a dedicated Roth conversion analysis without asset location or withdrawal sequencing.
You can now walk into a client meeting with five options and compelling visuals to back them up.
One plan, several strategies
A client weighing retirement at 62 versus 67 isn't looking at one tax situation. Retiring earlier and delaying Social Security opens up more low-income years before benefits and RMDs begin—conversion room a single strategy can't reflect for both paths at once.
You aren't limited to a single Tax Strategy proposal. Create additional tax proposals or copy an existing one, then toggle between them as you work. Each is independently customizable across all three levers, and each appears in the Retirement Analysis module alongside the original current and proposed strategies, so you can attach different tax proposals to different proposed plans or compare two side by side within the Monte Carlo simulation analysis.
How RightCapital’s tax-planning tools look in practice
Consider a hypothetical 75-year-old widow with a substantial traditional IRA she isn’t going to rely on for post-retirement income. Her RMDs are pushing her taxable income up each year, and because IRMAA uses a two-year MAGI lookback, those RMDs will drive her Medicare premiums higher two years down the line.
Tax Strategies models the phased conversion—how much to convert each year, which IRMAA tier to fill up to, and how the added tax and premium costs affect her cash flow. The output is a comparison she can follow: what happens if nothing changes, and what happens under the proposed strategy. This includes what her heirs inherit, since a traditional IRA passing to an adult child carries more exposure than a Roth IRA does.
Tax Analyzer shows a clear picture of where this client’s tax return stands. Perhaps she is interested in giving to charity. Create a proposal in the tax return line items to see how a Qualified Charitable Distribution (QCD) would change that picture. A QCD counts toward her RMDs while staying out of adjusted gross income, so it serves her philanthropic goals and eases the income pressure driving up her Medicare premiums.
Being able to show that comparison, rather than describe it, is what tends to move the conversation. Thomas Marki, CPA, CEPA® of AXIOM Founders Family Office Inc. works with small business owners on tax, business exit, estate, and charitable planning. He describes a charitably inclined client already giving $100,000 a year, who was holding highly appreciated stock he wasn't emotionally attached to in a high tax year.
"So we proposed donating $300,000 of stock to a donor-advised fund, three years of giving in one year. His lifestyle wouldn't change one bit, but he'd get a huge tax break. RightCapital let me show him the savings on the tax page with just a toggle, and that's a win-win for everybody."
See it for yourself
To see how Tax Analyzer and Tax Strategies could fit into your workflow, schedule a 1:1 demo or start a 14-day free trial.
Frequently asked questions
Tax Analyzer works with a client's actual tax return (uploaded or projected) to show what's happening in a single tax year and what a specific line item change would do to it. Tax Strategies models forward across the life of the plan, dynamically calibrating selected strategies of asset location, withdrawal sequencing, and Roth conversion strategies with each other. Tax Strategies is available across RightCapital plans while Tax Analyzer is included with Premium and Platinum subscriptions.
Yes. In RightCapital, Roth conversion and normal distribution targets include ordinary income brackets, capital gains brackets, and Medicare premium tax brackets. For those worried about triggering IRMAA, there is an option to indicate No IRMAA, which will calculate how much can be distributed without triggering IRMAA.
Yes. Within RightCapital you can build multiple dedicated tax strategy proposals within a single plan, each independently customizable and attachable to a different retirement proposal.